What It Actually Takes to Pass the Florida Adjuster Exam
The Florida public adjuster license exam isn't rocket science, but it's also not something you blow through with two hours of cramming. The state requires you to complete a 40-hour pre-licensing course before you're even allowed to sit for the test. That course covers Florida insurance statutes, ethics, contract law, and the mechanics of how claims work. Most people who fail do it because they skipped the statute sections and went straight to the flashcards. I spent seven years doing hurricane claims in South Florida before I ever touched the adjuster side of things. When my firm started needing in-house public adjusters, I took the course at a local prep school in Miramar. The instructor was a retired FDIV examiner who barely concealed his boredom. He made one comment that stuck with me: the exam tests whether you can read a statute and apply it, not whether you memorized definitions. That distinction matters more than people realize.
How Hard Is The Florida Adjuster License Exam
On a relative scale, the Florida exam sits somewhere between easy and moderate. The pass rate hovers around 65 to 70 percent depending on the quarter. That's higher than the adjuster exams in New York or Texas, which makes sense because Florida's insurance code is shorter and less tangled than some states. But don't let the numbers fool you. The questions are deceptively tricky. They'll give you a scenario where two statutes appear to conflict, and you have to pick the one that actually controls based on hierarchy and effective date. The exam itself is 75 multiple choice questions. You get two hours. You need 70 percent to pass, which means 53 correct answers. The testing vendor is PSI, and you schedule through their website. The cost is roughly $65 when I took it, though fees adjust annually. You bring two forms of ID, one must be photo-based. They scan your palm and take a screenshot at the desk. Standard stuff. Here's what trips people up: the questions are written in a very specific Florida administrative code style. They'll quote a statute verbatim and ask which action is permissible under that exact wording. If you've only studied from third-party summaries, you'll second-guess yourself. I saw a candidate last year who knew every flashcard in the deck but blanked on question 34 because the answer required reading the actual statute language, not the paraphrase. He failed by four points.
What the Course Actually Teaches You
The 40-hour requirement isn't filler. It covers the Florida Public Adjuster License Law, which is Chapter 626. that's the big one. It also goes into the Florida Insurance Code, contract formation and elements, the Statute of Frauds as it applies to insurance contracts, and ethics standards set by the Florida Office of Insurance Regulation. There's a section on claims handling procedures that most people skim too fast. One thing the course doesn't emphasize enough is the difference between a public adjuster and a staff adjuster. The exam will throw questions about scope of practice, and you need to know exactly what a public adjuster can and cannot do. They can negotiate claims on behalf of policyholders. They cannot practice law, give legal advice, or represent anyone in court. Cross that line and you're looking at felony charges, not just a revoked license. I had a client once who asked me to draft a demand letter that essentially constituted legal advice. I handed him a referral to a bad faith attorney instead. That boundary saving you from a disciplinary complaint is worth more than any exam score.
Get the Full Details
Study Strategy That Actually Works
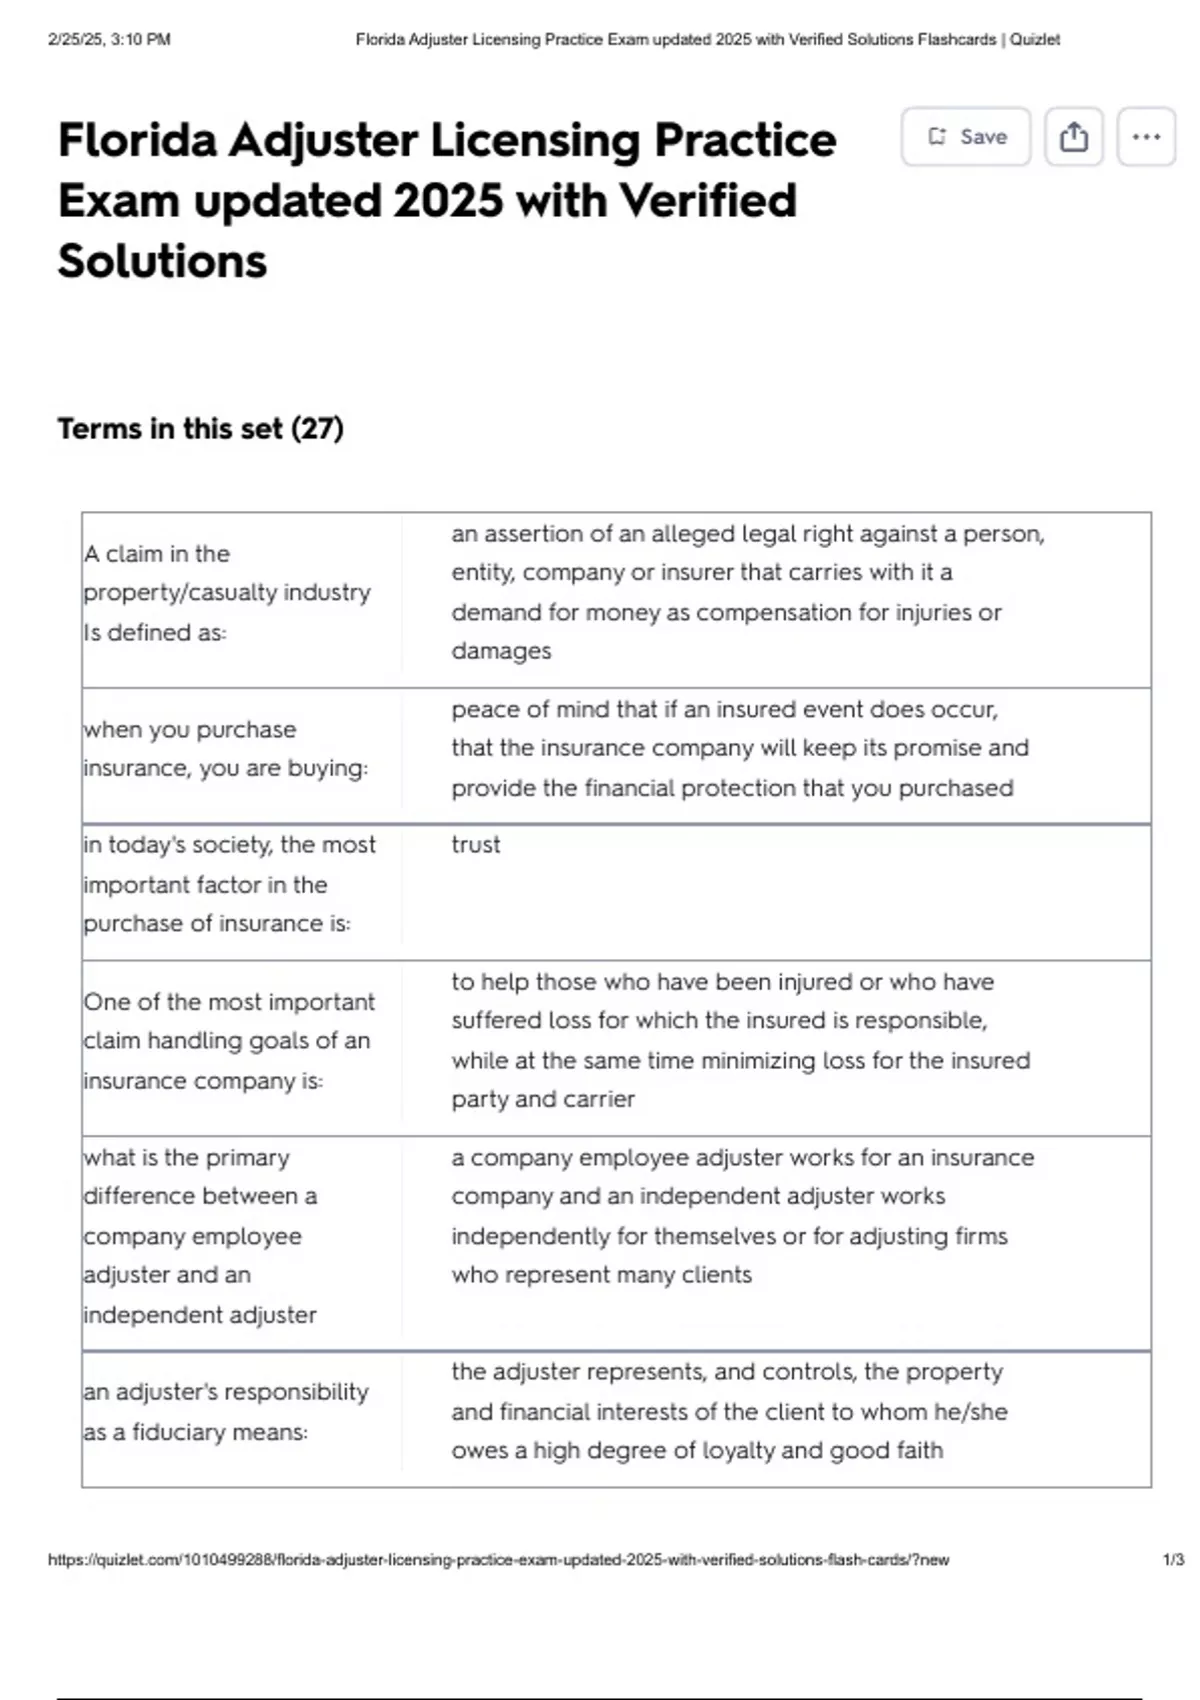
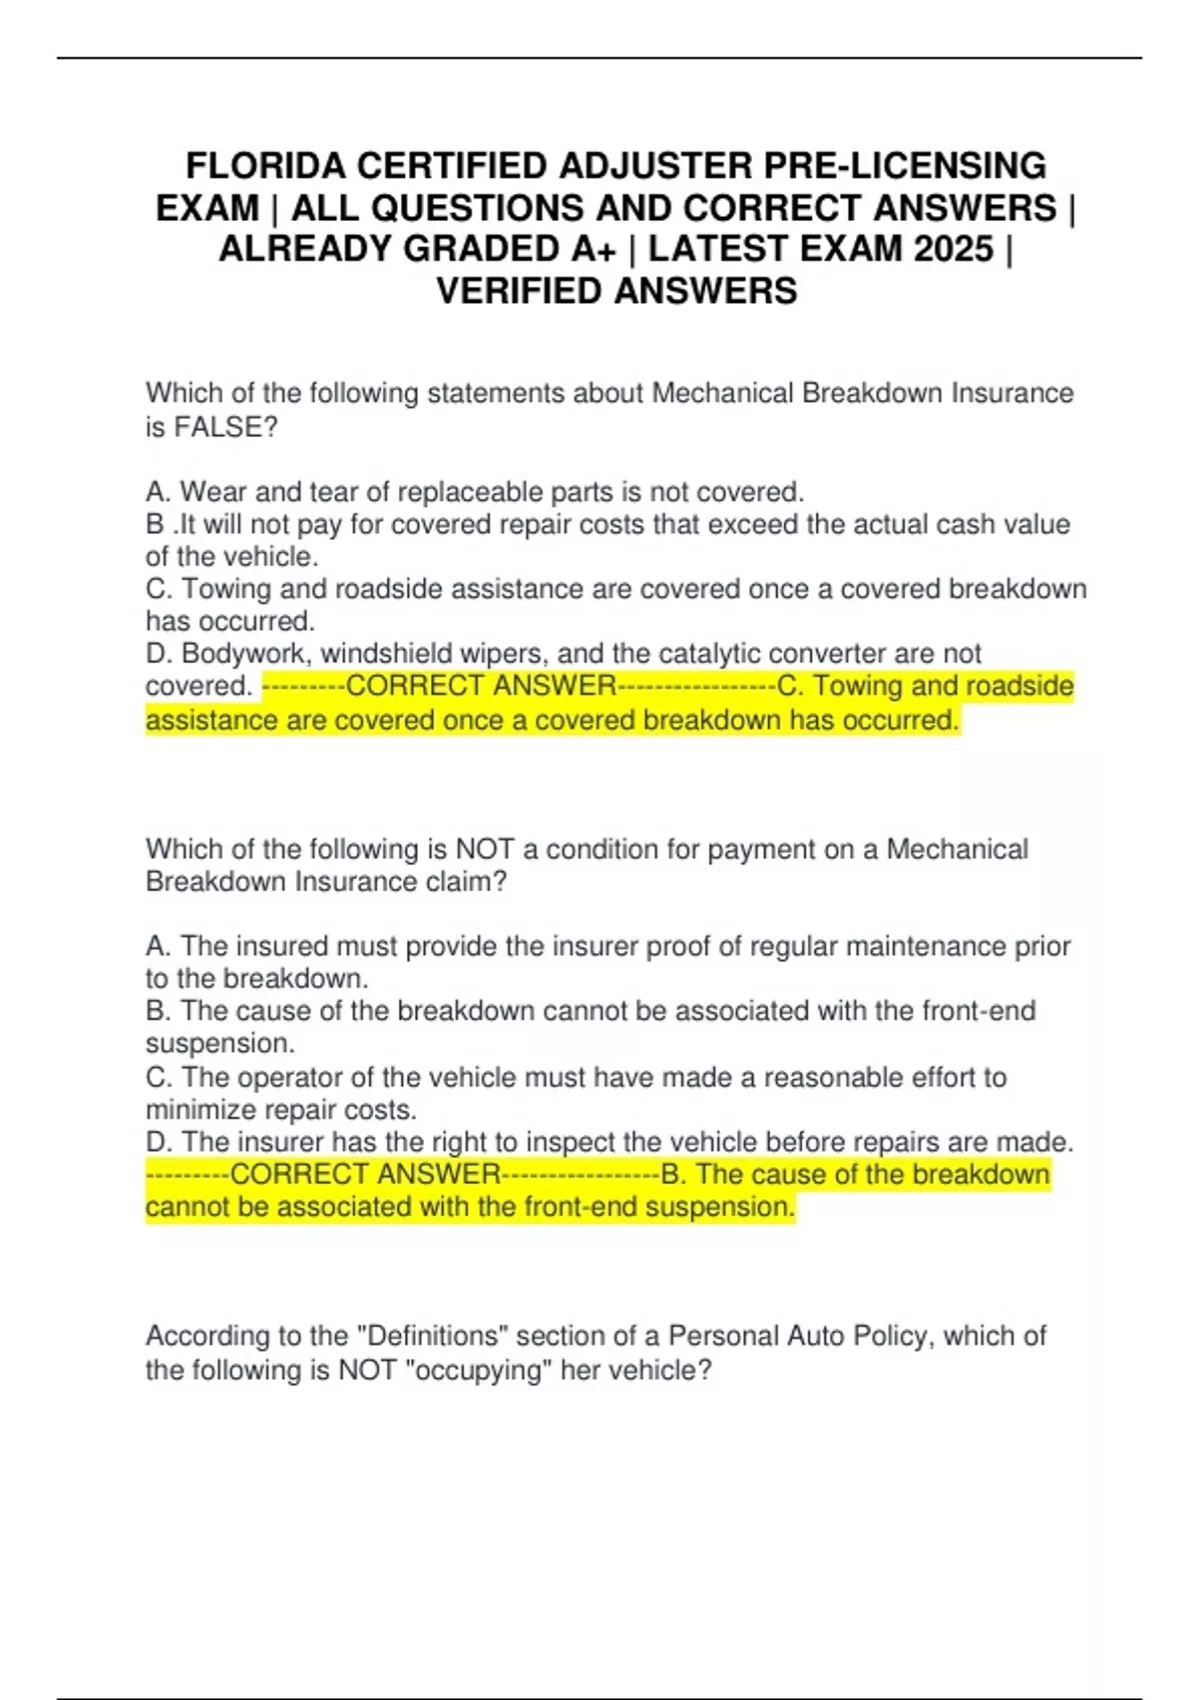
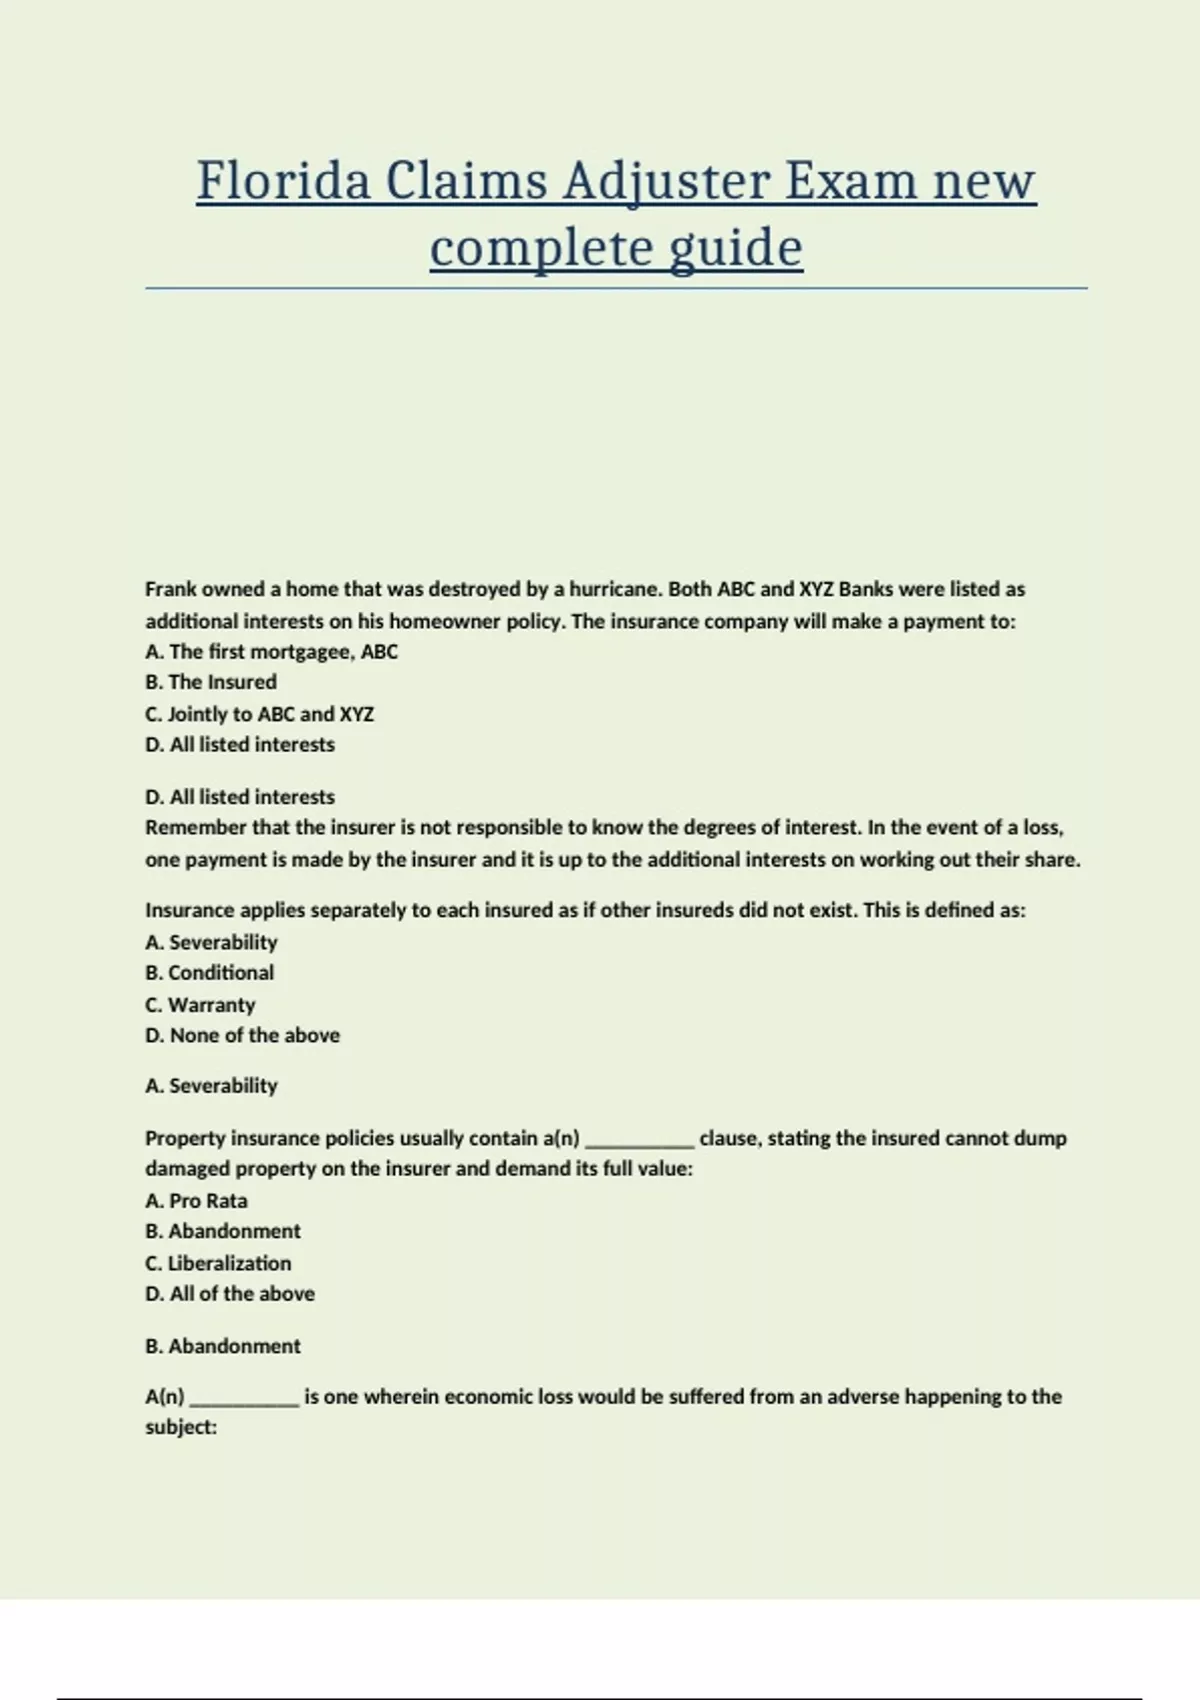
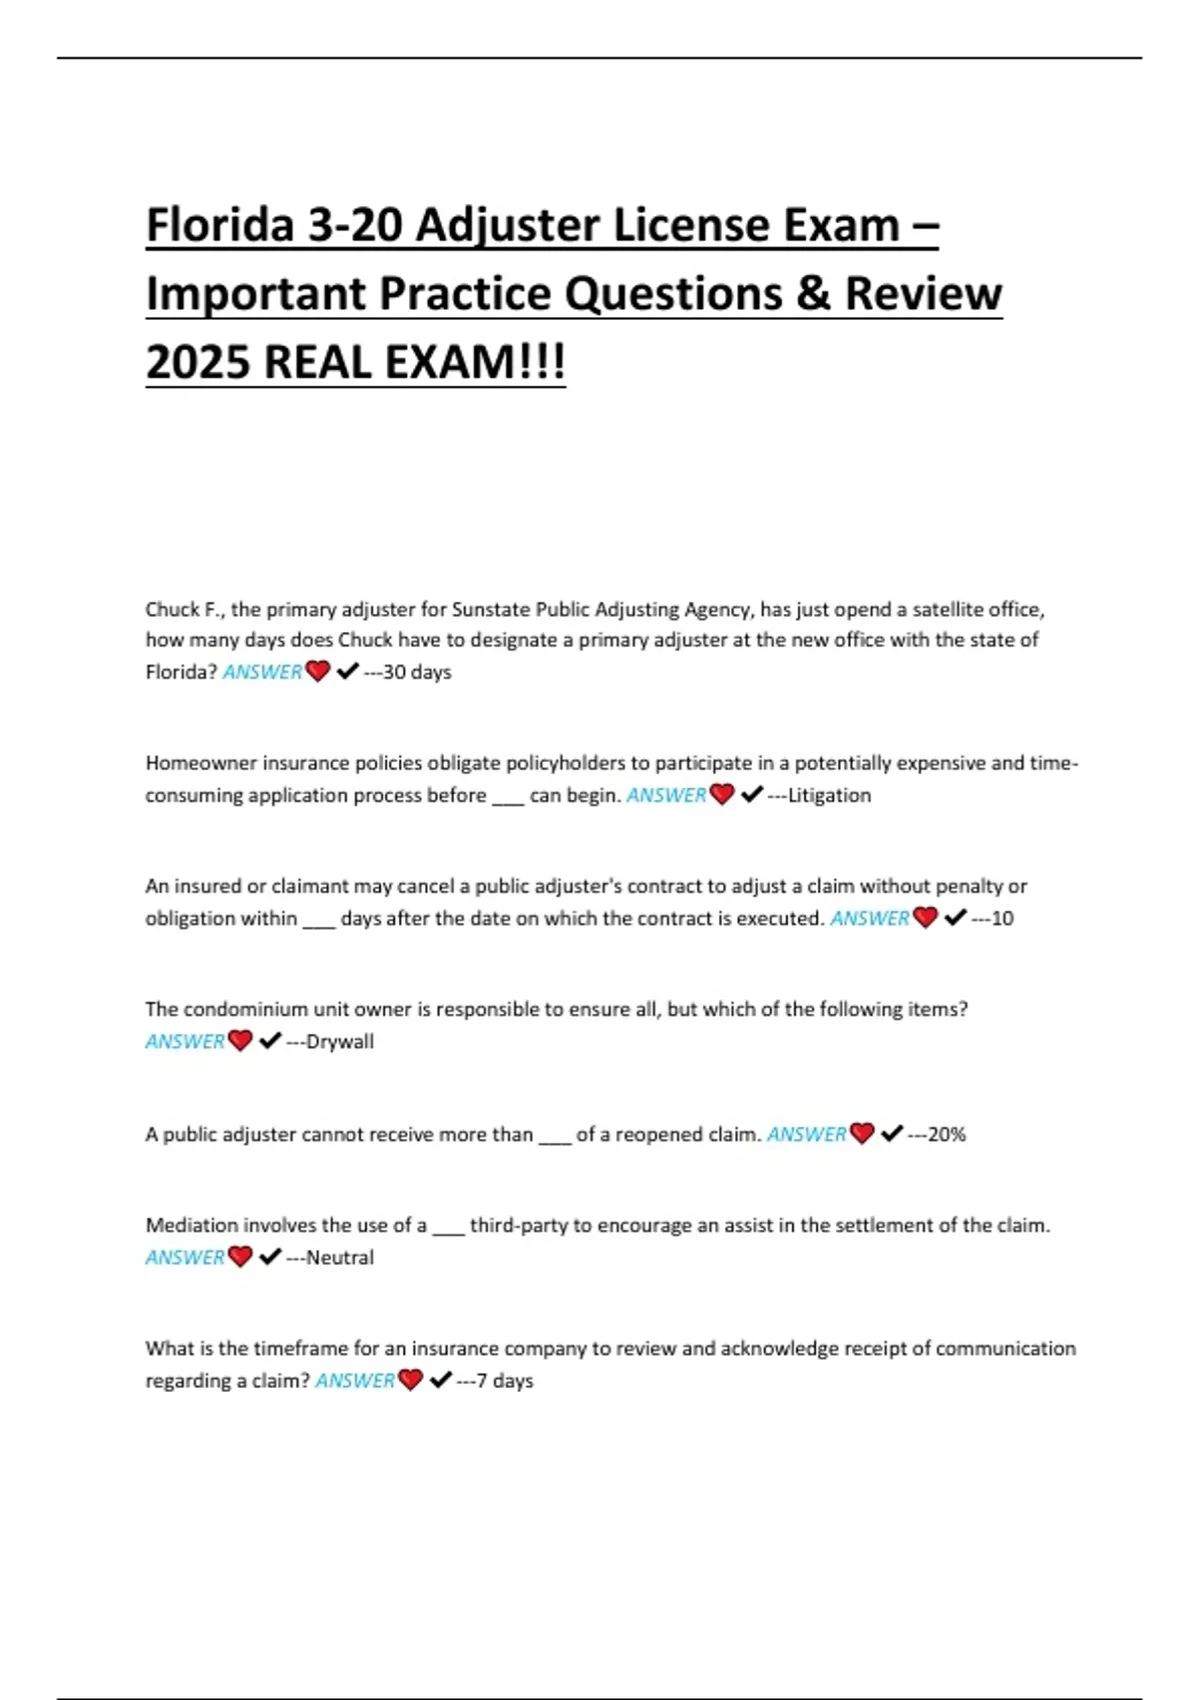
Most prep courses hand you a question bank of about 500 to 800 questions. The trick is doing them under timed conditions at least three times. The first pass you'll score maybe 50 percent. The third pass you should be clearing 80. If you're not at 80 on practice exams, you're not ready for the real thing. Here's the counter-intuitive part: don't focus on memorizing the questions. Focus on understanding why the wrong answers are wrong. The exam loves to put two plausible answers and make you pick the better one. For example, a question might ask about the deadline for a public adjuster to file a bond. Both 30 days and 60 days could sound reasonable if you're guessing. But the statute says 30 days from issuance of the temporary certificate, and if you know the source, you won't waver. I also recommend pulling the actual Florida statutes from the online code and reading them alongside your notes. It takes longer, but it builds the muscle memory you need for those verbatim quote questions. The Florida Legislature website has the whole code searchable. Spend an hour going through 626. and 627. and it will pay off on test day.
A Realistic Edge Case You Won't Find in Prep
During my own exam, I ran into a question about concurrent licensing. The scenario described someone who held both a staff adjuster credential and was applying for a public adjuster license. The question asked about the examination waiver provision. The statute says you can waive the exam if you've held a staff adjuster license for at least two of the last five years and are in good standing. But there's a catch: the waiver only applies if you're applying within 12 months of your staff license expiration. If you let it lapse and come back two years later, the waiver is gone. I caught that detail because I'd actually dealt with a licensing edge case at my old firm. A adjuster let their credential expire, took a year off, and came back thinking the waiver still applied. We had to walk them through the re-examination process. That experience made the question feel like a review of something I'd handled, not a brand new puzzle. I answered it confidently and moved on.
What the Exam Doesn't Tell You About Practicing
Passing the exam is the easy part. Maintaining the license is where people struggle. You need 24 hours of continuing education every two years, including three hours on Florida-specific law changes. The state sends reminders, but they're easy to ignore if you're busy with claims. I've seen adjusters let their CE slip for two cycles and end up with a lapsed license they couldn't reactivate without retaking the exam. There's also the bonding requirement. You need a $50,000 surety bond before you can activate your license. The annual premium runs anywhere from $300 to $800 depending on your claims history and credit profile. If you've got a DUI on your record or a prior disciplinary action, expect the high end. Some carriers won't even bind a public adjuster with a clean record for less than $500 a year now, given the litigation environment. The fee structure matters too. Florida charges an initial application fee plus an annual renewal fee. As of my last check, it was around $100 for the application and $60 for renewal, but these shift with legislative budget cycles. Don't assume the numbers stay static.
When the Exam Isn't the Right Path
Sometimes the Florida exam simply isn't worth your time. If you're based in another state and only occasionally handle Florida policies, it might be cheaper and faster to partner with a licensed public adjuster rather than invest 40 hours and exam fees. Multi-state licensing adds up quickly, and Florida isn't reciprocal with many states. Similarly, if you're already a licensed attorney in Florida, you don't need a public adjuster license to negotiate claims on behalf of clients. You'd be operating under your law license instead, which has different rules and different limits. The overlap between what attorneys and public adjusters can do is narrow but real, and confusing the two has gotten people in trouble with the Florida Supreme Court's oath and admissions division. And if you're only interested in property and casualty adjuster work for an insurance company, you want a staff adjuster license, not a public adjuster one. Those are separate tracks with different courses, different exams, and different scope. I know people who paid for the public adjuster course when they should've taken the staff adjuster path. Waste of money and time.
The Bottom Line
The Florida public adjuster exam is passable with serious study. The 40-hour course gives you the foundation. Practice exams build your speed. Reading the actual statutes builds your accuracy. If you can clear 80 percent on timed practice tests, you're in good shape. The real challenge starts after you pass, when you're balancing continuing education, bond maintenance, and actual claim work that tests your knowledge in ways no multiple choice question ever will. I've watched people breeze through the exam and then struggle with the practical side because they never really internalized the statutes. I've also seen people who scored barely above 70 percent on the exam go on to run very competent practices because they understood the material deeply enough to apply it. The score matters less than the habit of reading the code itself.