The Actual Timeline Depends on How You Structure Payments
A standard 30-year fixed mortgage at 6.5% on a $300,000 loan means about $1,896 a month in principal and interest. That doesn't mean you actually owe the bank for 30 years though. The amortization schedule is what determines when the loan clears, and it works against you in the early years. Most of your first dozen years of payments go toward interest, not principal. You could make every payment on time for eight years and still owe nearly the full original balance.
What Actually Determines How Long To Pay Off Mortgage
The core variables are the interest rate, the loan term, and whether you're making extra payments. A 15-year loan at the same rate pays off in half the time but costs roughly 50% more per month. The monthly payment difference on a $300,000 loan jumps from about $1,896 to $2,533. That's the tradeoff most people calculate incorrectly because they focus on total interest savings without checking if the monthly cash flow actually works for them.
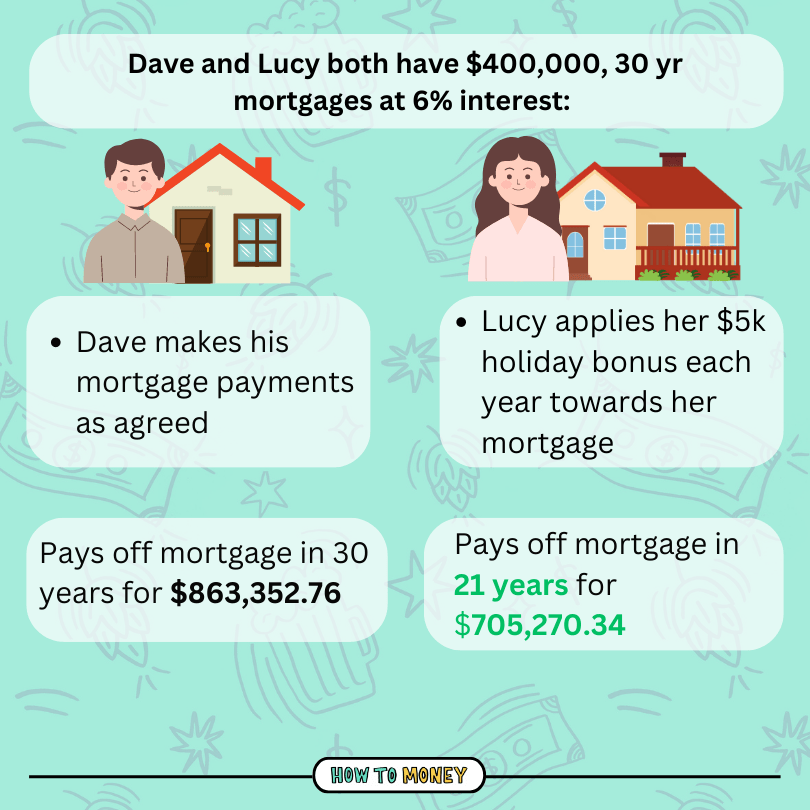
Extra payments change everything. One additional monthly payment per year, applied directly to principal, typically cuts a 30-year mortgage down to roughly 23 or 24 years. Two extra payments per year pushes it closer to 20 years. The timing matters enormously. An extra payment made in year three saves far more interest than one made in year twenty-five, because each extra dollar paid early stops compounding for longer. I worked through a case where a client had been making consistently extra payments since year one and ended up paying off a 30-year mortgage in about 17 years. Another client started the same strategy five years later and only shaved four years off. Same amount of extra money, wildly different outcome because of when they started.
Common Ways People Shorten the Timeline
Biweekly payments are popular but often misunderstood. You pay half your monthly amount every two weeks, which results in 26 half-payments per year, or 13 full payments. That one extra payment annually reduces a 30-year mortgage to roughly 23 to 24 years depending on the rate. Some servicers charge a setup fee for this program, usually around $200 to $300, and a small monthly administration charge. You can replicate the same effect manually by dividing your monthly payment by 26 and multiplying by 12, then sending one extra principal payment each year on your own. No fee, same result.
Lump-sum payments from bonuses, tax refunds, or inheritances are the most straightforward tool. A single $10,000 principal payment in year two of a $300,000 loan at 6.5% saves roughly $38,000 in total interest and cuts about two years off the payoff timeline. The calculation assumes the payment is applied to principal and stays applied. That assumption is where things go wrong.
The Servicer Problem That Nobody Warns You About
I ran into this with a client's refinance in 2019. They sent an explicit written instruction with their extra payment marking it as "principal only." The servicer applied half of it to escrow for property taxes anyway because their system defaulted to prorating extra payments across the account. It took 47 days and three phone calls to get the error corrected and the records adjusted. The workaround is simple and painful: always send principal-only payments via a check with the words "principal only" handwritten clearly on the memo line, mail it with certified tracking, and confirm in writing within 30 days that the full amount was applied to principal. Get that confirmation in writing. Verbal promises from servicer representatives don't hold up when you're auditing your statements later.
Mathematical Realities Most People Miss
The Rule of 78s is something you'll encounter in older loans and some refinancing scenarios. It's an interest calculation method that front-loads interest even more aggressively than standard amortization. If your loan uses Rule of 78s, making extra payments early provides dramatically more benefit because the interest is even more concentrated in the early period. Most conventional 30-year fixed mortgages don't use this anymore, but it still appears in some state-specific programs and older portfolio loans. Ask your servicer explicitly which method governs your loan.
There's also a hard ceiling on how much speed you can buy. Once you're in the last five years of a standard amortization, the principal portion of each payment already exceeds the interest portion. Extra payments still reduce the balance, but the interest savings per dollar decline sharply. A $5,000 extra payment in year two might save you $30,000 in interest. That same $5,000 in year twenty-eight saves maybe $2,000. The math doesn't lie but it's easy to overlook when you're just trying to feel productive about paying down debt.
When Paying Early Is Actually the Wrong Move
Prepayment penalties exist and they're not rare. Some loans carry a clause that charges 2% of the remaining balance if you pay off the loan within the first three years, tapering down to 1% in years two and three. On a $300,000 loan with a 2% penalty in year one, that's $6,000. You'd need to save more than $6,000 in interest over the life of the loan just to break even on paying off early. Always read the prepayment penalty section before you start sending extra money.
Then there's the opportunity cost question. If your mortgage rate is 6.5% and you could put that same extra money into a diversified index fund averaging 7% to 8% annually after taxes, the math might favor investing instead of prepaying. The gap is narrow at these rates but it exists. I've seen people ruthlessly pay down a 4.5% mortgage while simultaneously carrying credit card debt at 22% because they didn't look at the full picture. That's obviously the wrong order. But the reverse mistake happens too—people with 7% student loans and a 4% mortgage will pay off the mortgage first thinking it's simpler, when mathematically the higher-rate debt should clear first.
A Practical Framework That Actually Works
Start by pulling your most recent mortgage statement. Note the current principal balance, your interest rate, and the remaining term. Then calculate what happens if you add one extra monthly payment per year applied to principal. There are free calculators for this, but you can also approximate it manually: divide your current monthly principal portion by the annual interest rate, multiply by the number of extra payments, and subtract that from your total term. It won't be exact but it gets you in the right neighborhood.
If you're within five years of payoff and your rate is below 5%, the extra time and stress of aggressive prepayment is usually not worth it compared to other uses of your cash. If your rate is above 6.5%, prepayment becomes a significantly better return than most safe investments available today. The breakeven point sits somewhere around 5.5% to 6% depending on your tax situation and risk tolerance.
Gallery How Long To Pay Off Mortgage
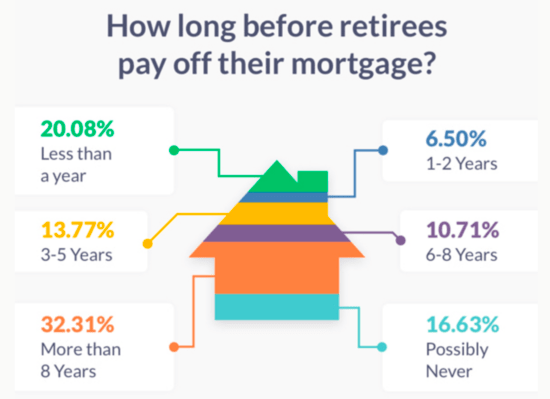
How Long After Closing is Your Mortgage Paid Off? A Guide to Achieving Mortgage Freedom
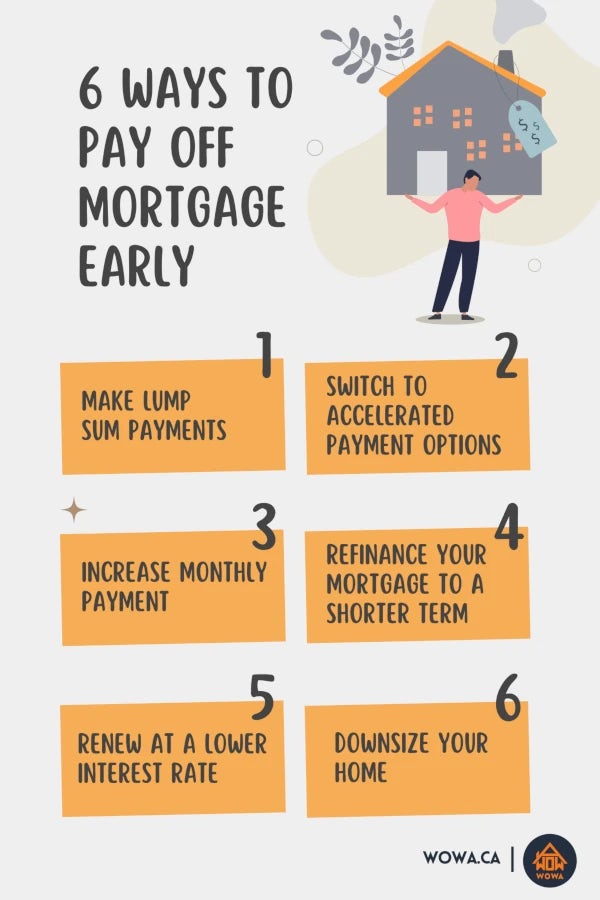
How to Pay off Your Mortgage Early | WOWA.ca
How to Pay Off Your Mortgage Early
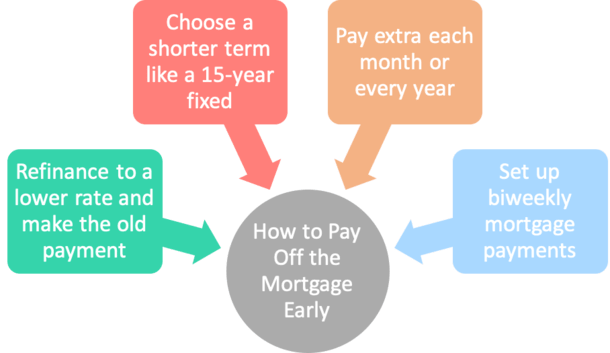
How to Pay Off the Mortgage Early: 30+ Methods You Can Use Right Now
Ways to Pay Off Your Mortgage Early - How to Money