Setting Realistic Expectations for CFP Exam Prep
The CFP exam isn't something you can cram through in a week. It covers about 100 learning statements across six major domains, and the questions aren't straightforward recall—they're scenario-based problems that require you to apply formulas, read case studies, and make judgments under time pressure. Most people who actually pass put in somewhere between 250 and 300 hours of study over eight to twelve weeks. That's not a guess. That's what the actual data from review course statistics and candidate surveys show year after year. You'll find plenty of blogs saying six weeks is enough. They're wrong for most people. Six weeks at full-time study intensity might work if you already work in the financial planning space daily and the material is somewhat familiar. If you're coming from a completely different field, or if you're working full-time while studying, you should plan for ten to twelve weeks minimum. The difference between passing and failing often comes down to whether you've actually done enough practice questions, not whether you've read the material once. Here's what nobody tells you: the exam is longer than it looks on paper. There are 170 multiple-choice questions spread across two ninety-minute segments with a break in between. That's about forty seconds per question, and many of the case studies contain far more information than you actually need. I spent about forty-five seconds on one question last time just trying to figure out which numbers in the case study were relevant and which were distractors. That single question ate into the time I had for three or four others.
What the Exam Actually Tests
The CFP exam splits its content into six learning modules: General Principles, Insurance Planning, Investment Planning, Employee Benefits and Retirement Planning, Tax Planning, and Estate Planning. Each module has a specific weighting on the exam. Investment Planning carries the most weight at around twenty percent, followed by General Principles and Retirement Planning at roughly fifteen percent each. Tax and Estate Planning each sit around twelve to thirteen percent, and Insurance Planning is the smallest chunk at about nine percent. Understanding the weighting matters because it determines how you allocate your study time. People who spend equal time on every module are wasting their time. If you have two weeks left and you're weakest in Estate Planning, pushing through more Insurance questions won't move the needle as much as spending those hours where your score will actually improve.
How I Structured My Own Study Period
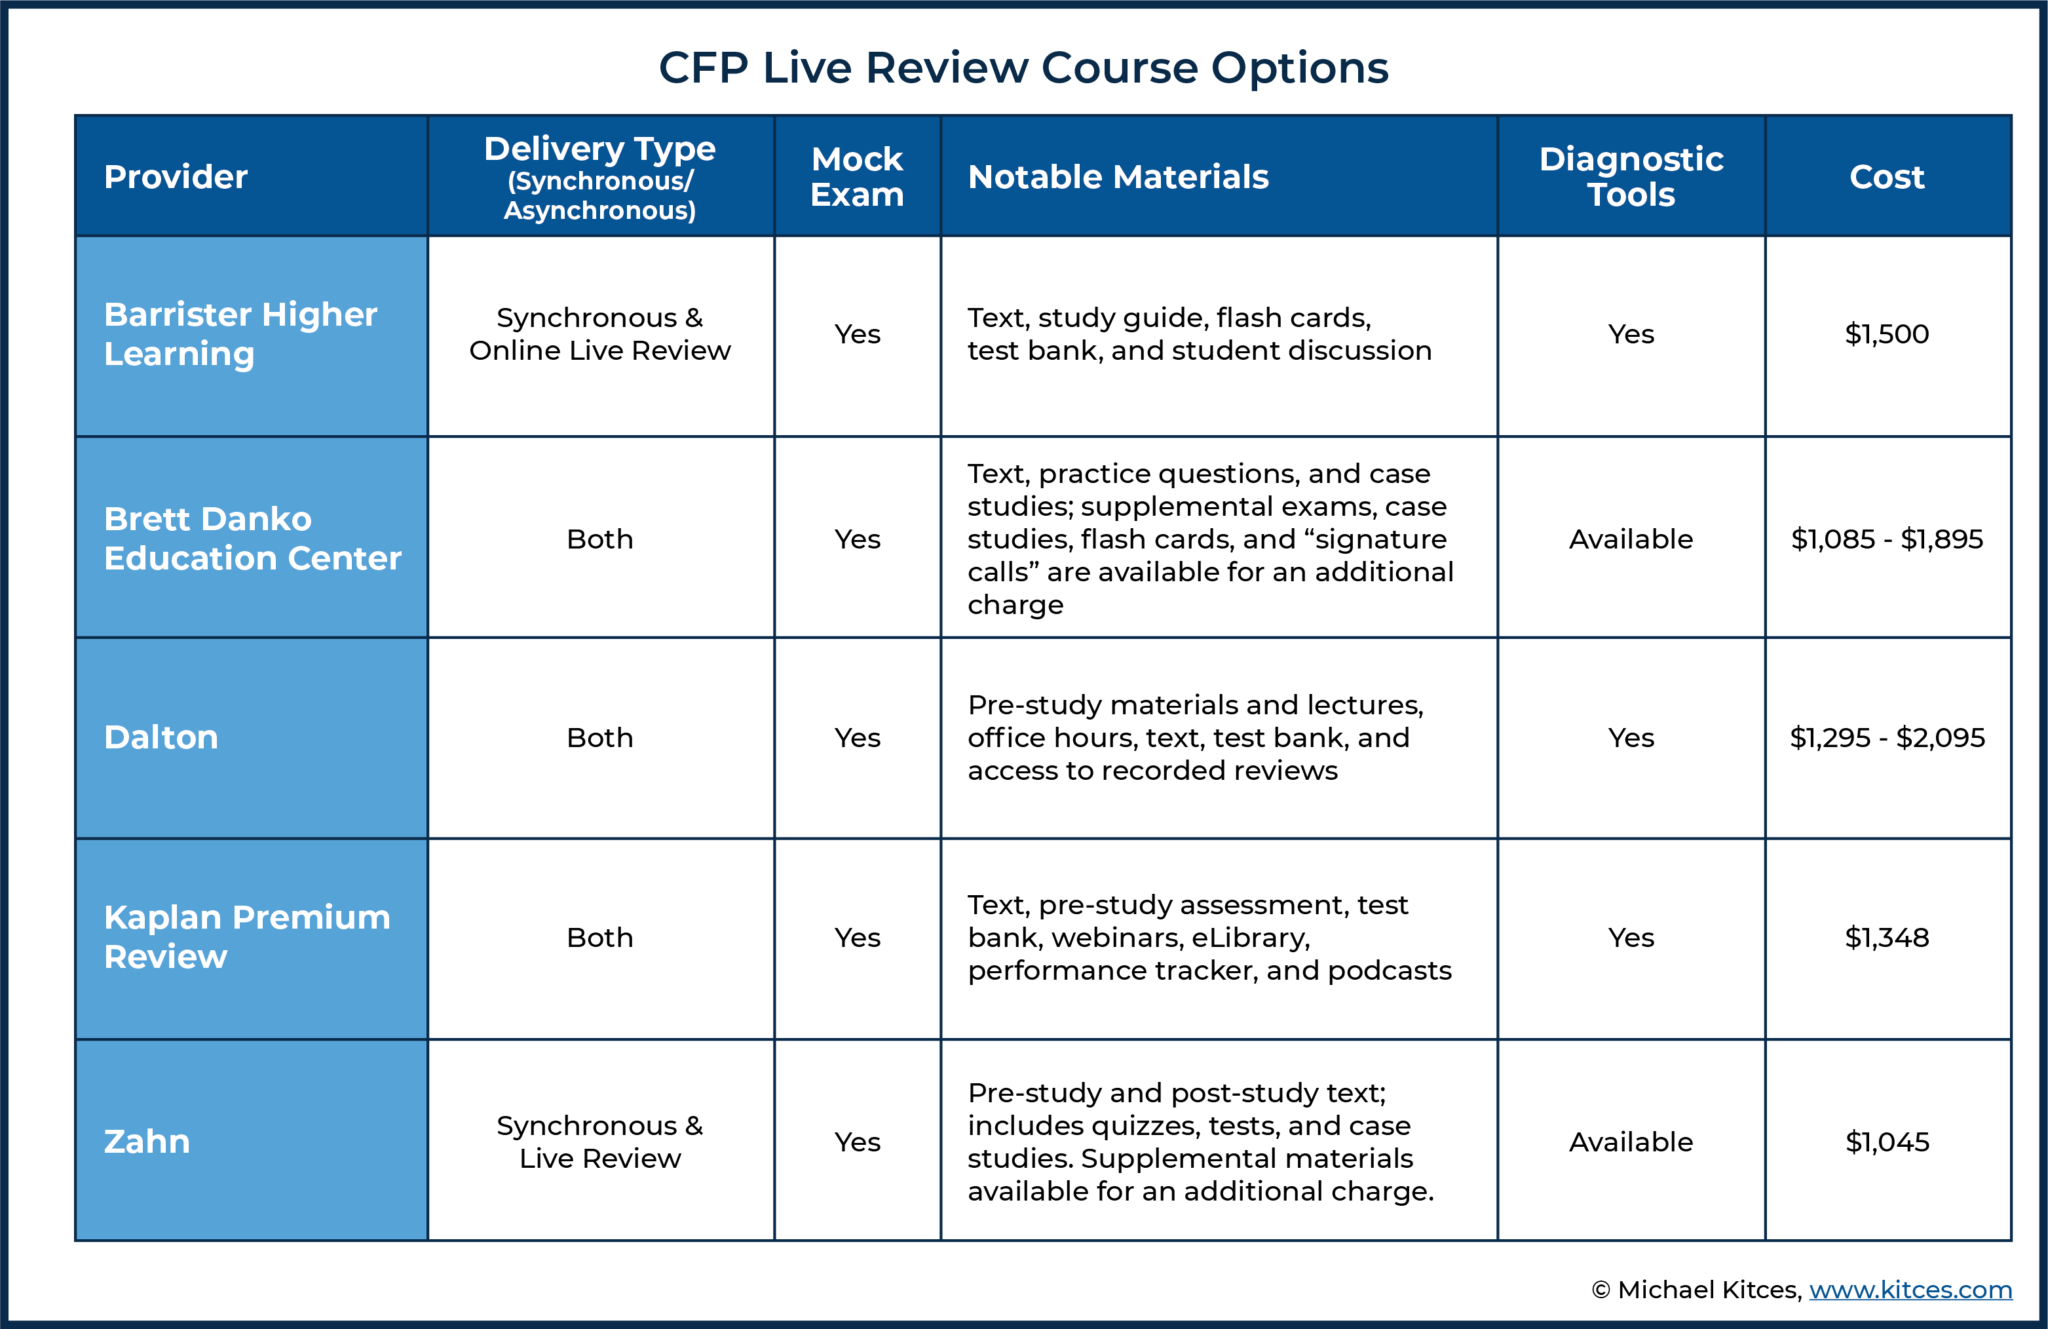
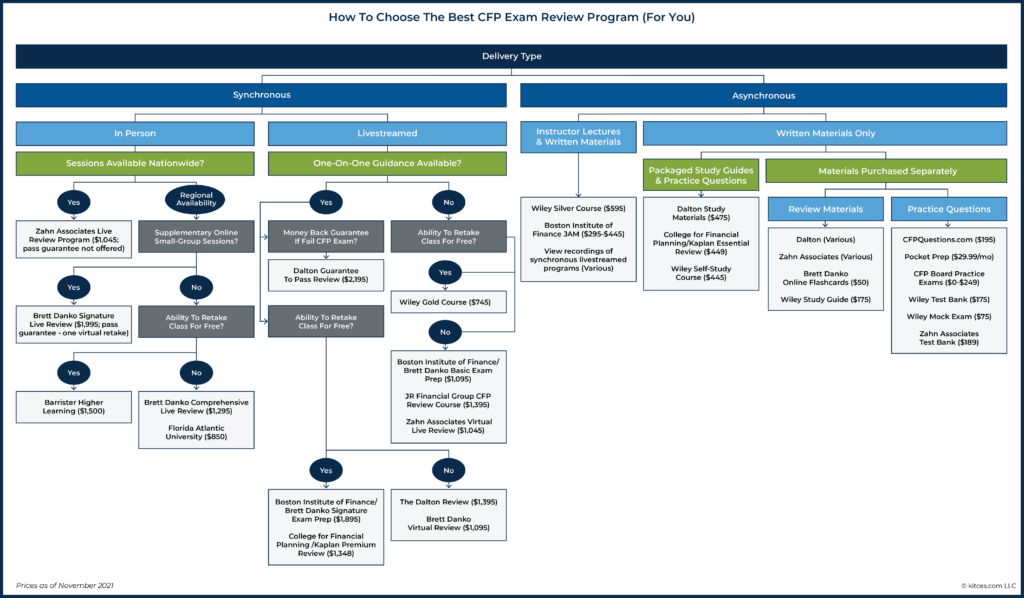
When I sat for the exam, I worked full-time and studied on evenings and weekends over about ten weeks. I used a combination of a pre-built review course and the official CFP study guide. I blocked out two hours on weekdays and four to five hours on Saturdays. Sundays were for lighter review or rest, depending on how the week went. That came to roughly two hundred and eighty hours total, which landed me in the middle of the typical range. One thing that surprised me was how much the case study format threw me off. The review course questions are often cleaner and more direct than the actual exam. On exam day, I'd read a case study that was three or four paragraphs long, full of irrelevant details mixed in with the data I needed. I developed a workaround where I'd highlight the key figures first—ages, income, assets, tax brackets—before I even looked at the question. This saved me maybe ten to fifteen seconds per case study, which added up to several minutes over the full exam. It sounds small, but when you're on a tight clock, those seconds matter.
Get the Full Details

Common Mistakes That Waste Time
The biggest waste I see is reading the textbook cover to cover before doing any practice questions. You can read every page in the Kaplan or Gleim materials and still freeze when you see a novel-format question on exam day. Start practicing questions early, ideally after your first pass through a module. The second pass should be almost entirely practice questions and reviewing the explanations for ones you got wrong. Don't just check if you were right or wrong. Read the explanation for every question you missed, and especially the ones you guessed on correctly. Those are the concepts you don't actually understand yet. Another mistake is underestimating the time it takes to work through the calculator functions. You need to be fast with your financial calculator—Texas Instruments BA II Plus or HP 12C—on topics like TVM calculations, amortization schedules, and bond math. If you're fumbling with the calculator during practice, you'll be behind on the real exam. I used about ten minutes a day just drilling calculator keystrokes for TVM and cash flow functions over the last two weeks before the exam. It felt like wasted time at first, but it cut my per-question time down significantly on test day.
When You Might Need More or Less Time
Some people finish in eight weeks and pass. Others take fifteen and still struggle. The variables that shift your timeline include your baseline knowledge, how many hours per week you can realistically commit, and how well you handle standardized testing under pressure. If you already have a finance or accounting background, you'll move faster through Investment and Tax Planning. If you're coming from HR or a non-numerical field, those same modules will eat up more of your schedule. There's also the question of retakes. If you fail, you can retake the exam, but there's a waiting period and you'll need to budget for another study cycle. Some candidates come back after six to eight weeks of prep for the retake. The good news is that you only need to retake the parts you missed, not the entire exam, which can make the second round shorter. But planning for that possibility from the start is smarter than hoping you won't need it.
A Realistic Week-by-Week Breakdown
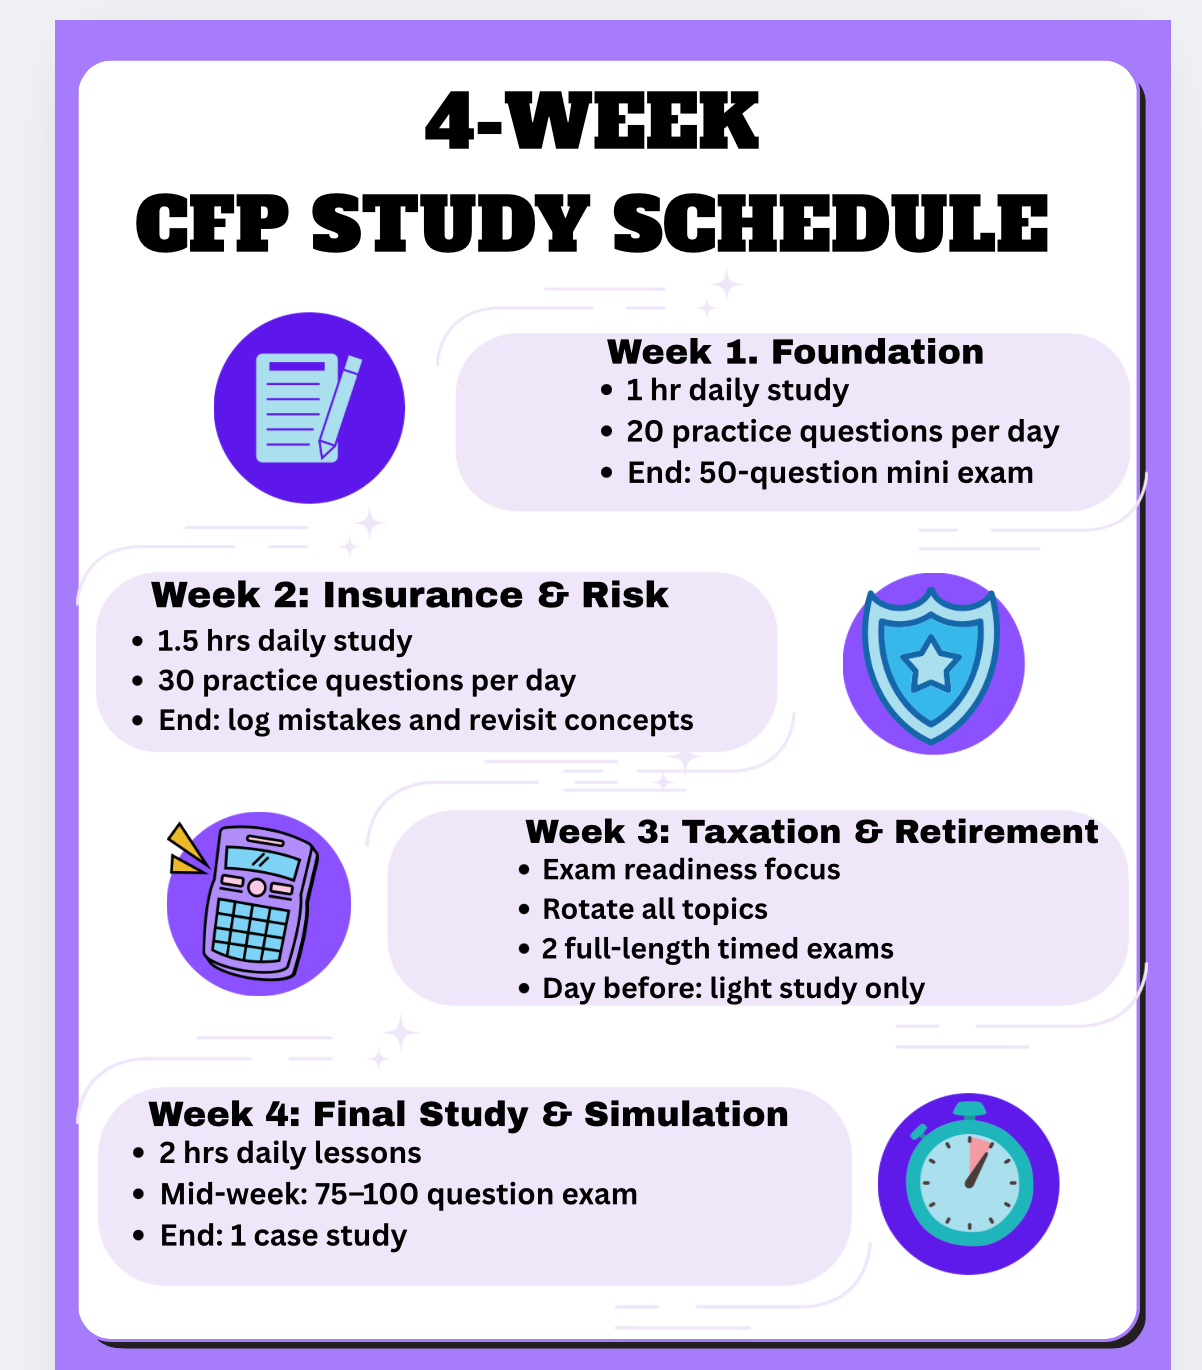
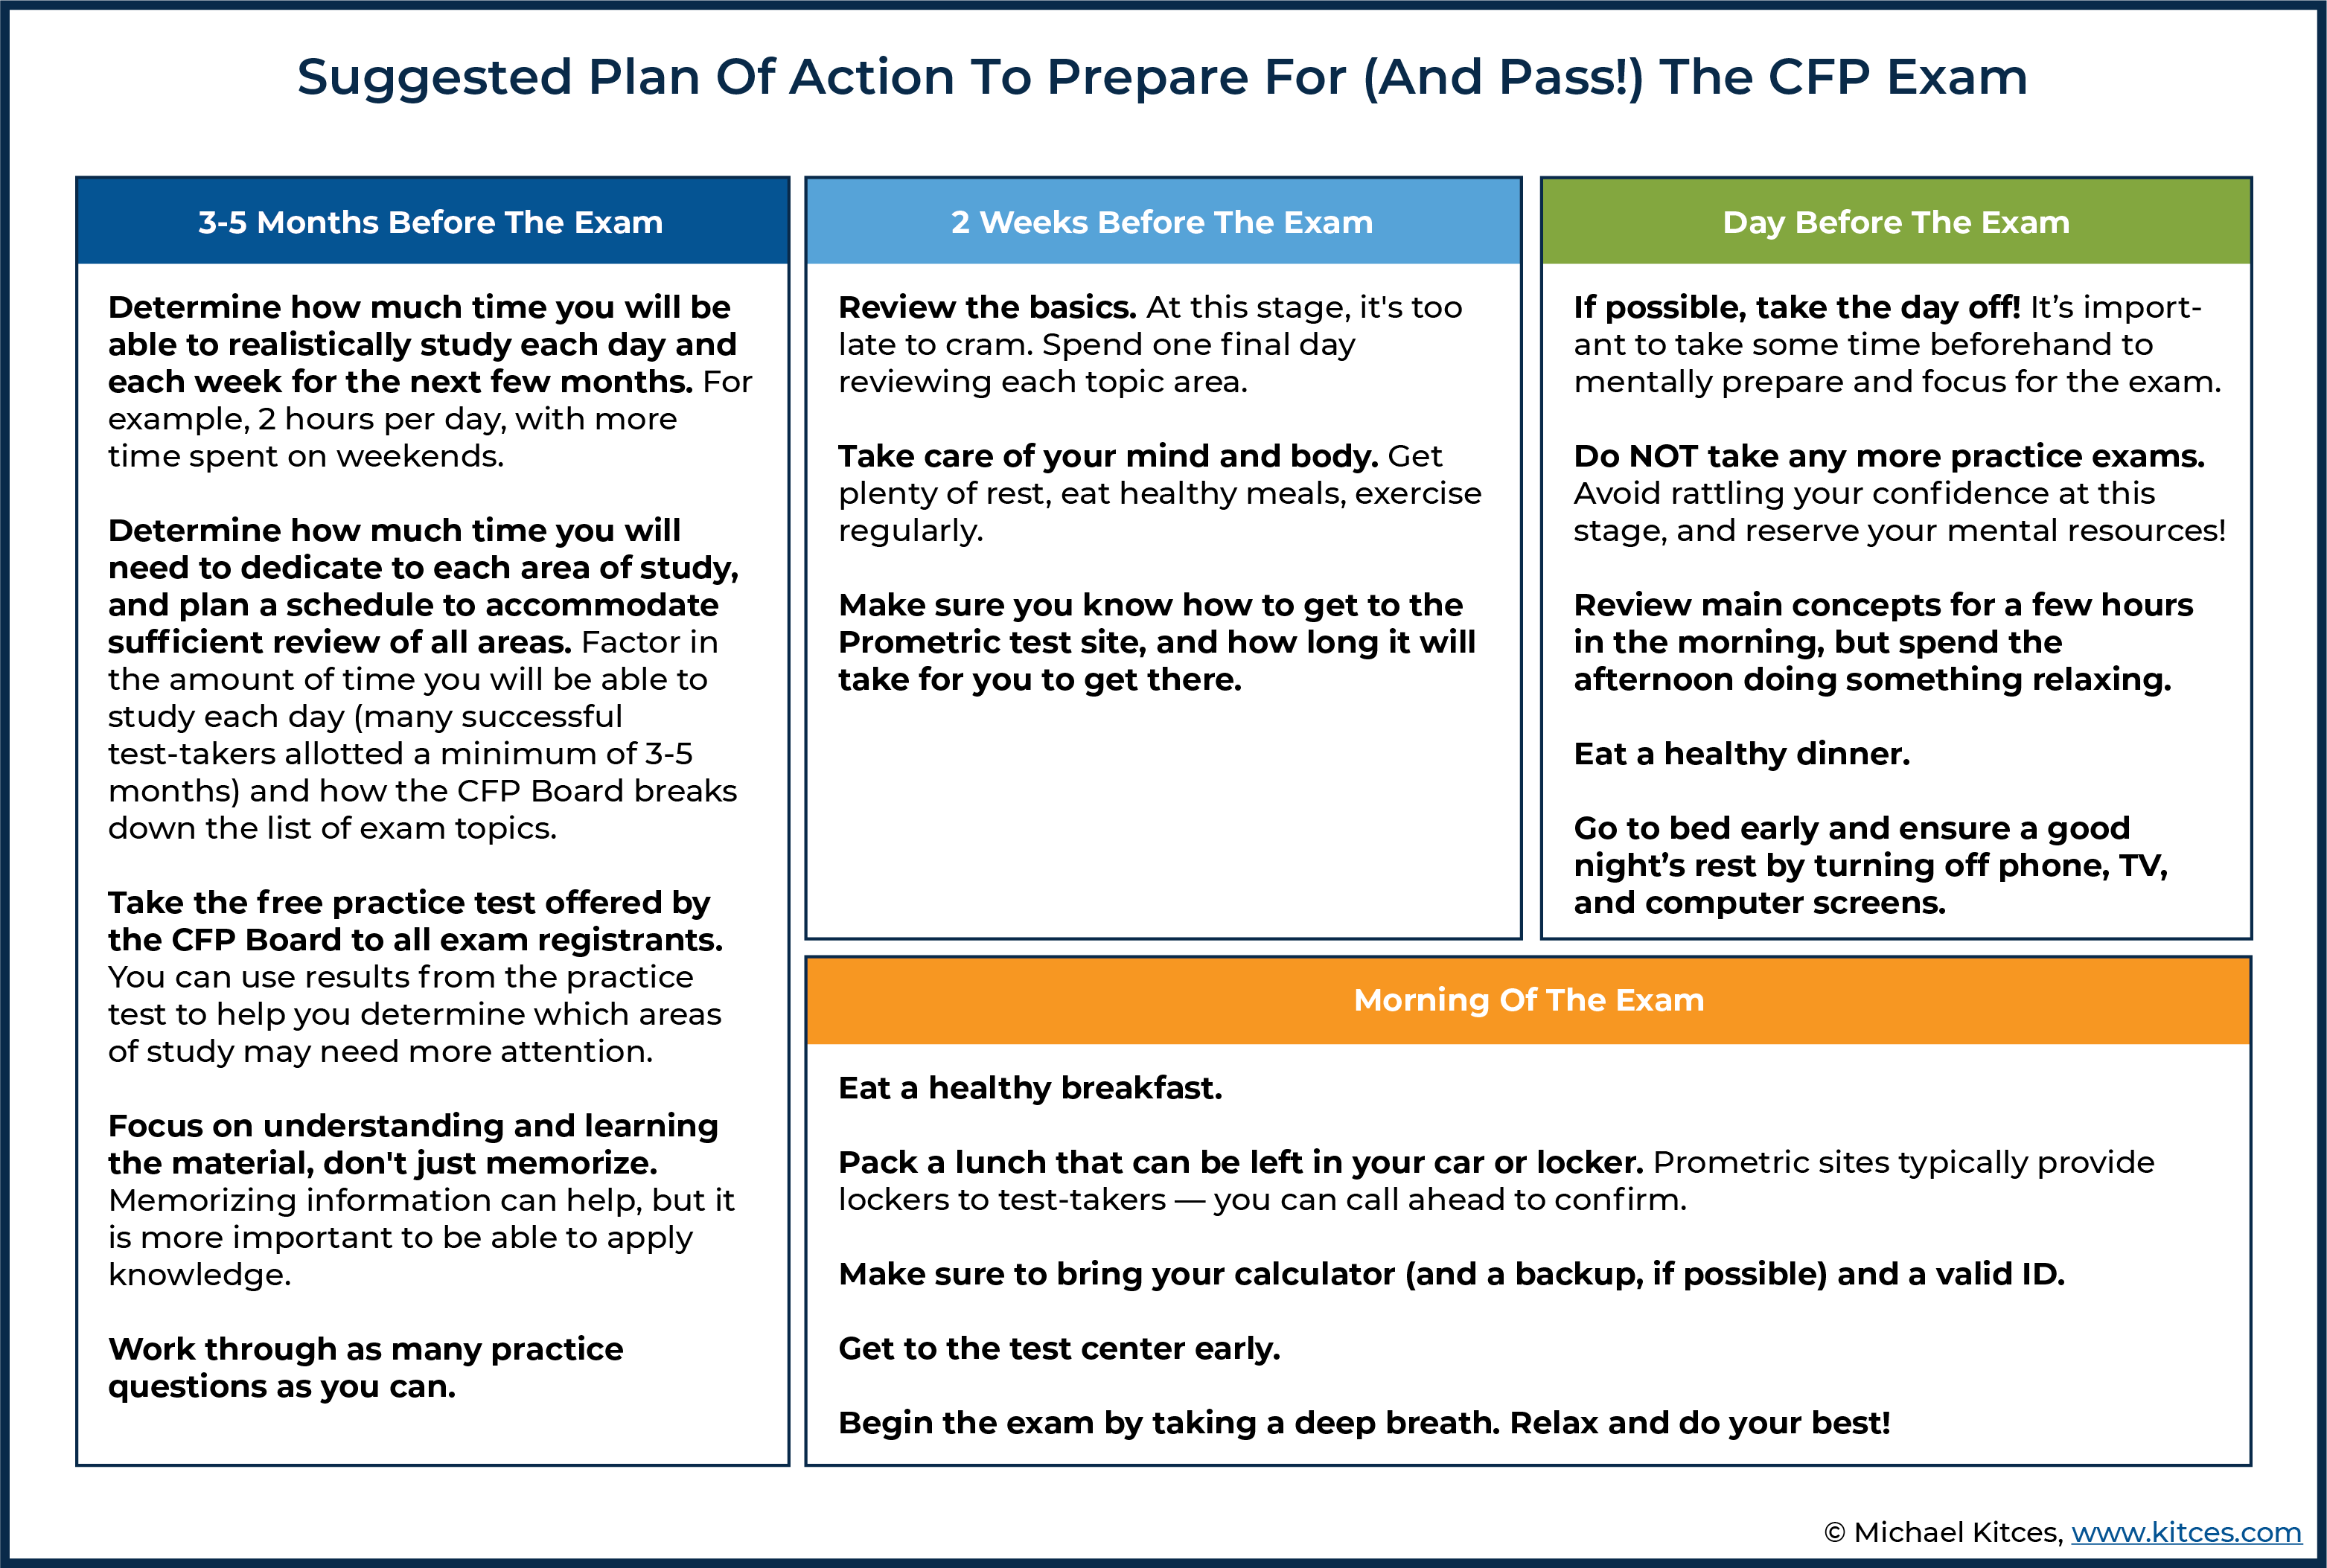
Here's how a ten-week plan actually looks in practice. Weeks one and two go to General Principles and Insurance Planning. These are the foundation topics, and you'll reference them throughout the exam. Weeks three and four are Investment Planning, which is the heaviest weighted module and requires the most problem-solving practice. Weeks five and six cover Retirement Planning and Employee Benefits. Weeks seven and eight are Tax Planning and Estate Planning. Weeks nine and ten are almost entirely review and practice exams under timed conditions. I took two full practice exams in those final two weeks, under conditions that mimicked the real test as closely as possible. No phone, no notes, timed breaks only. The first practice exam score was probably ten to fifteen points below passing. The second, taken a week later, was close enough that I felt confident going in. That gap between those two scores is exactly why the final two weeks matter more than any single topic review.
What I Would Do Differently Next Time
If I were starting over, I'd front-load the hardest material. Investment Planning and Tax Planning are where most people lose points, and they also require the most mental energy to study. Putting them at the beginning of your schedule, when you have the most freshness and time, makes more sense than saving them for later when you're already fatigued. I saved Investment Planning for week three because it seemed approachable after General Principles. By the time I hit it, I was already feeling the pressure of the timeline and didn't give it the attention it deserved. I'd also spend more time on the calculator from the very start, not just in the final two weeks. Building fluency early means you're not fighting the tool while you're also trying to learn new concepts. Ten minutes a day from week one changes everything.
The Honest Bottom Line
Plan for at least eight weeks if you can study full-time, and ten to twelve weeks if you're working or have other commitments. The total hours matter more than the calendar span. Two hundred fifty to three hundred hours of focused, practice-heavy study is the target. Reading alone won't get you there. Doing hundreds of practice questions under timed conditions is what actually builds the muscle memory you need on exam day. And don't skip the full-length practice exams in the final weeks. They're the single best predictor of how you'll actually perform, even if the scores look discouraging at first.