Card Numbers Explained
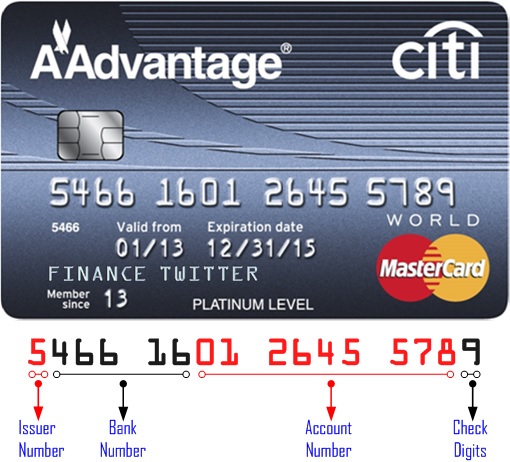
Most credit cards carry 16 digits. That is the standard for Visa, Mastercard, Discover, and American Express used to be different. Amex cards have 15 digits, which trips people up when they copy numbers from memory. JCB, Diners Club, and UnionPay follow similar patterns but you will not see them every day. The number sits embossed or printed on the front. It is called the Primary Account Number, sometimes abbreviated as PAN. The first six to eight digits identify the bank and card network. The last digit is a checksum calculated using the Luhn algorithm. Everything in between is your unique account identifier.How Many Numbers On A Credit Card
The short answer is 16 for most cards, 15 for American Express. But the count alone does not tell you much about how the number works in practice.
I remember running into an issue at a hotel in Chicago. The front desk scanner kept rejecting my Amex. Not because the number was wrong, but because the system expected 16 digits and truncated the trailing zero on their validation script. I ended up typing the number manually into a web form while the cashier watched. Took three minutes. The fix was just telling them to check the backend regex pattern. Since then I always carry a Visa or Mastercard when traveling internationally. The first digit is the Major Industry Identifier. Bank and financial institutions start with 3 through 6. Travel and entertainment cards start with 3. Everything else falls into different buckets. The next five to seven digits are the Issuer Identification Number, which pins the card to a specific bank. Your actual account number fills the middle section. The final digit validates everything.The Luhn check is simple enough that you can verify any card number on paper. Double every second digit from the right. Add the results. If the total divides evenly by ten, the number is structurally valid. This catches typos but does not verify whether the card is active or has funds.
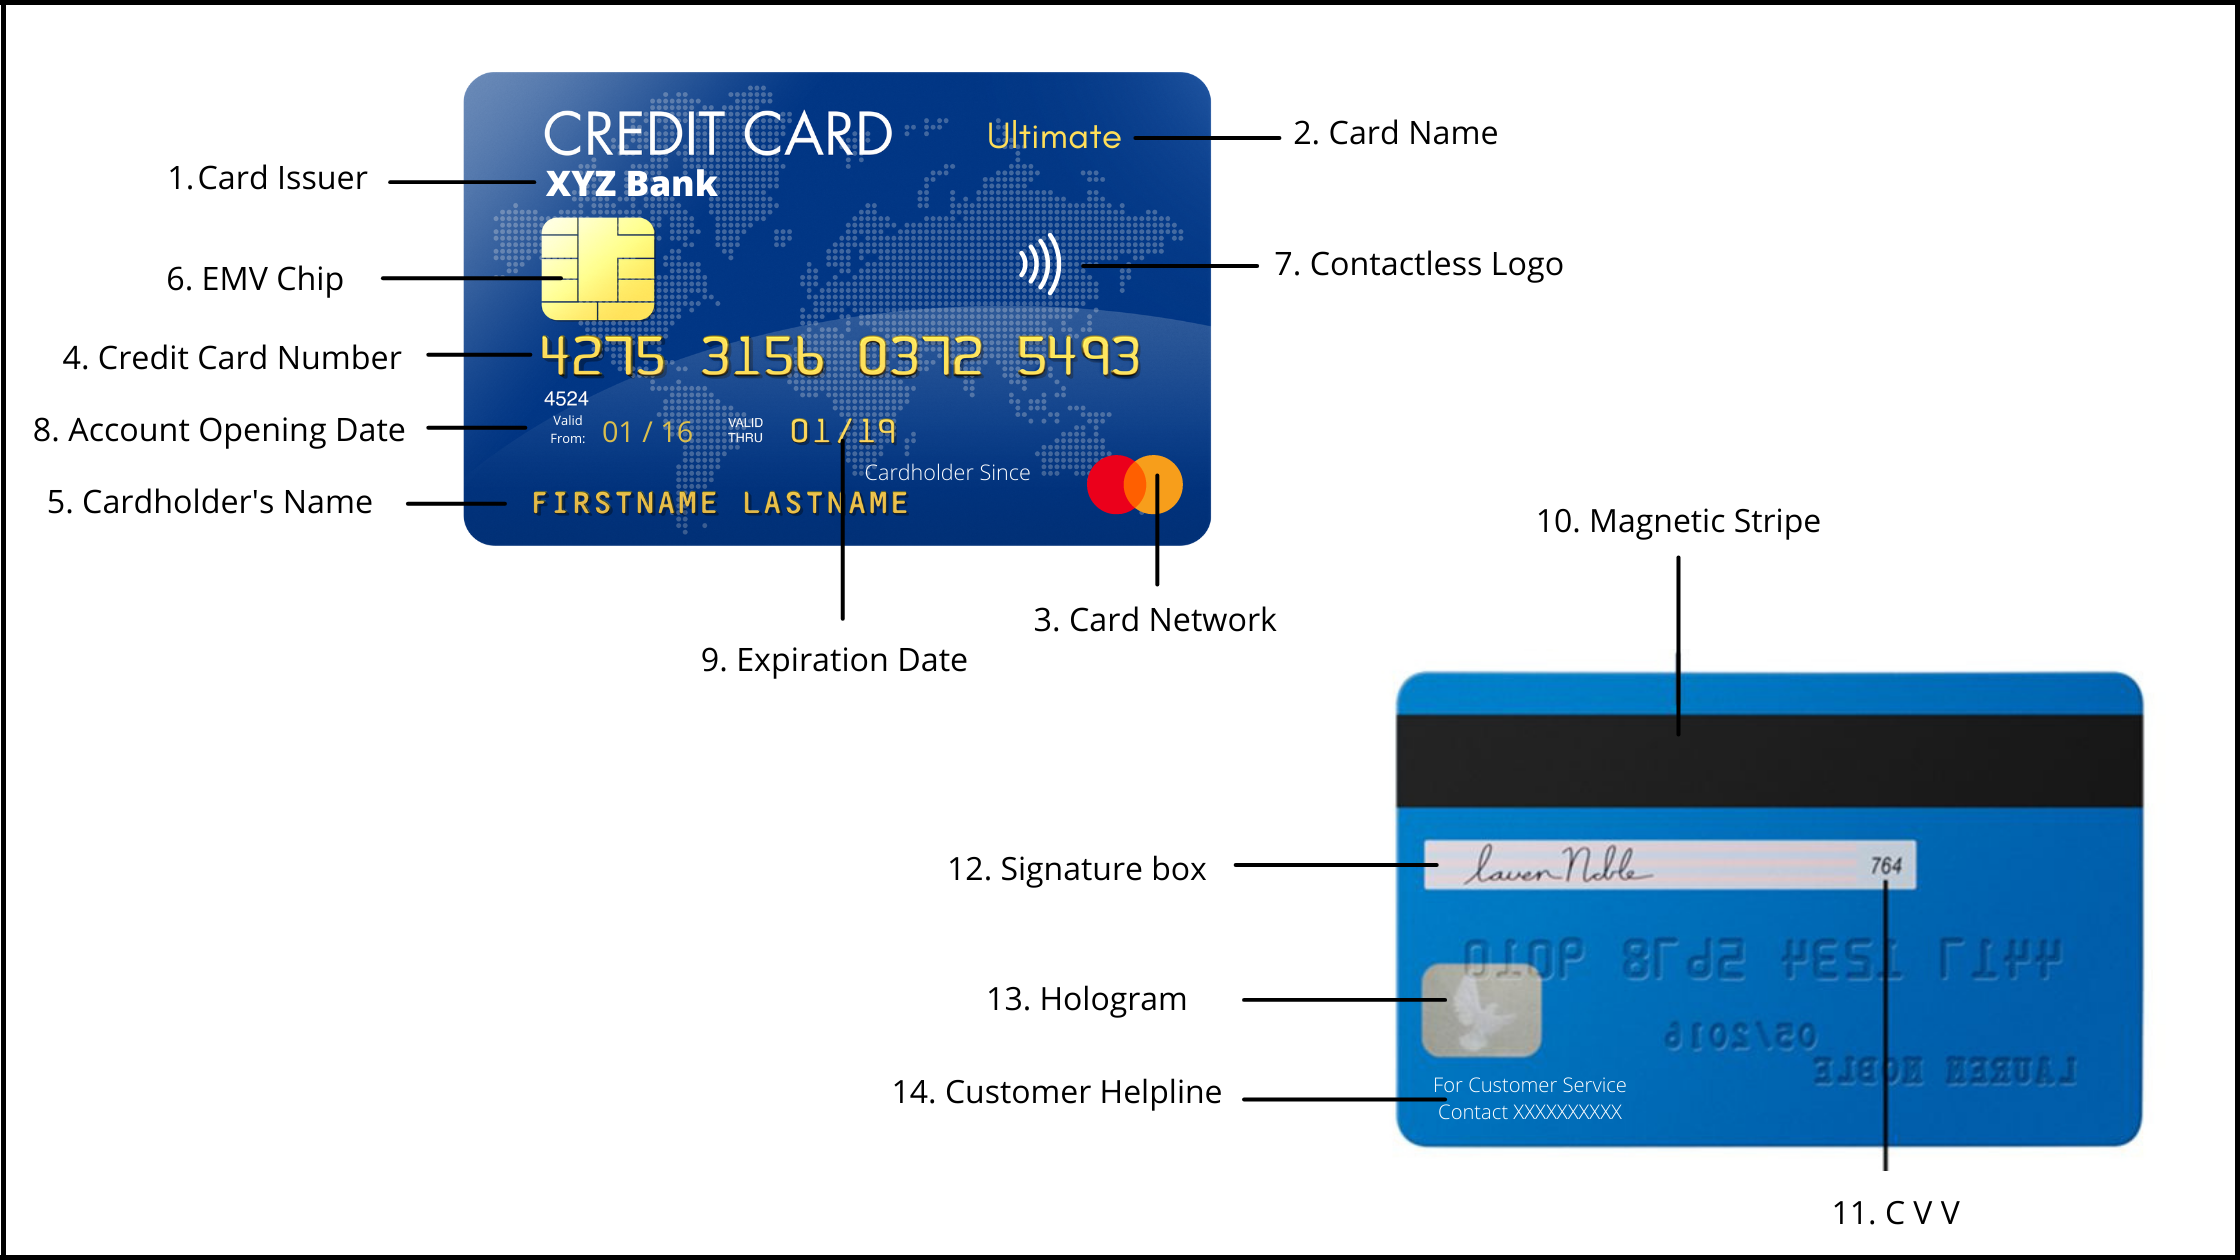
A few nuances that matter. Card numbers can change when a bank rebrands or merges. Chase used to issue cards starting with 4987. After internal migrations, those shifted to different prefixes. The length stays 16 but the issuer identification block changes. Virtual card numbers from services like Revolut or Wise follow the same rules but rotate more frequently. You will see new numbers every time you generate a token. Security professionals treat the full 16-digit number as sensitive. Skimmers on ATMs capture the PAN along with the magnetic stripe data. That is why chip cards exist. The EMV chip generates a unique transaction code each time. The actual card number never leaves the terminal. Contactless payments add another layer. The radio frequency signal contains a encrypted token, not your raw PAN.If you need to verify a card number without charging it, most payment processors offer a test mode. Stripe, Braintree, and Adyen all provide dummy numbers that pass Luhn validation but never touch real accounts. Use 4242 4242 4242 4242 for Visa testing. It is hard coded into their docs. No one gets billed.
Get the Full Details

When replacing a card, the number usually changes along with the expiration date. The account remains the same. Auto-payments transfer over automatically with most banks but you should confirm. PayPal, Amazon, and subscription services sometimes need manual updates after a reissuance. Missing one renewal can interrupt a service you rely on.
Digital wallets abstract most of this away. Apple Pay and Google Pay store tokens rather than raw numbers. The merchant never sees your actual PAN. This reduces fraud exposure significantly. The tradeoff is that you cannot use these tokens outside the wallet ecosystem. Some older payment systems do not support tokenized transactions yet. You still need the physical card for those. The industry standard has held steady for decades. 16 digits cover 95 percent of consumer cards globally. The remaining 5 percent split between Amex, Diners, and niche issuers. New payment methods like blockchain wallets or Central Bank Digital Currencies follow completely different numbering schemes. They do not use the PAN format at all. But those are outside the credit card domain entirely. If you are building a payment form, validate length before submission. Accept 15 for Amex, 16 for everyone else. Run the Luhn check client-side to catch obvious errors. Do not store the full number server-side. Request tokenization from your processor. This cuts liability and simplifies compliance review. Most legal teams prefer this approach anyway. The number itself is just an identifier. It does not reveal your balance, credit limit, or payment history. Those live on the bank's servers. Anyone who sees your card number knows the routing information but nothing about your account status. That is why phishing attempts focus on CVV and expiration rather than the PAN alone. Combine those and you have enough for most online purchases.I stopped carrying paper copies of my card numbers years ago. The risk of losing a wallet with the PAN printed on it felt unnecessary. Now I keep the number in a password manager encrypted field. If I ever need it, I retrieve it from there. The physical card stays in my wallet. The digital record stays separate.
Payment networks update rules periodically. Visa and Mastercard both publish version histories for their numbering standards. The core structure has not changed since the 1990s but minor adjustments happen. New BIN ranges get allocated. Some old ranges get retired. If you are maintaining a database of accepted card types, refresh the ranges annually. Most processors provide updated CSV files for this purpose. The takeaway is straightforward. Look at the front of your card. Count the digits. Sixteen means Visa, Mastercard, Discover, or UnionPay. Fifteen means Amex. Everything else is either a specialty card or potentially fraudulent. When in doubt, call the number on the back of the card and ask the representative to confirm the PAN format for your issuer. They will tell you without verifying anything sensitive.