Figuring Out Your Capital Gains Tax Isn't as Simple as the Website Suggests
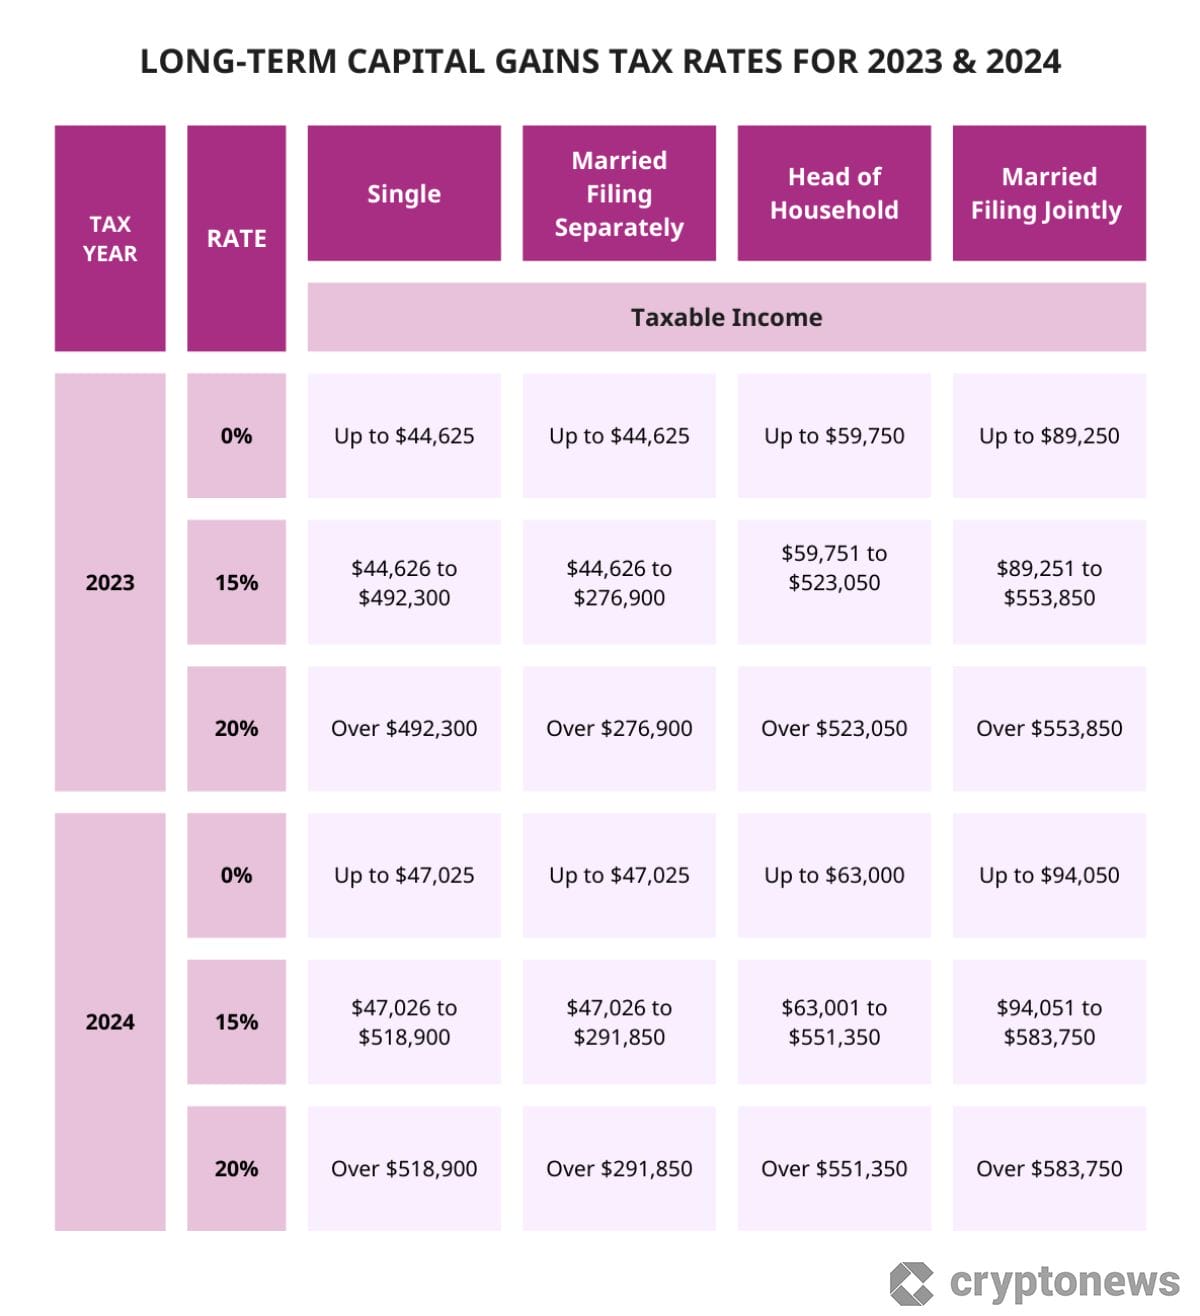
The quick answer most people want is that you pay either 0%, 15%, or 20% depending on your taxable income, and that's technically true if you sold a single stock in a normal year. But the actual calculation has enough moving parts that you can easily get it wrong by a few thousand dollars if you're not paying attention to the details most calculators skip over. Start with your cost basis — the actual amount you paid for the asset including any commissions or fees. A lot of people just look at their purchase price and forget the transaction costs, which makes their gain look bigger than it really is. Your holding period is the other piece. If you held the asset for more than one year before selling, it's a long-term capital gain and the preferential rates kick in. One year and one day makes the difference between paying top income tax rates or the much lower capital gains brackets. Anything shorter is short-term and gets taxed as ordinary income, period. I spent about three hours one year reconciling my cost basis across fourteen different lots of the same ETF because I'd bought shares at various times over five years and my broker's summary lumped them together. The workaround was pulling the individual trade confirmations from my brokerage account and building a spreadsheet that tracked each lot's purchase date, shares, and per-share cost. Once I had that, I could match specific lots to the sale transaction and use the average-cost method only on the shares where the lot-specific identification wasn't clear. That process took me about forty-five minutes once I figured out the workflow, so going forward I always pull the lot-level data right after a sale instead of waiting until tax season when everything gets messy.
Here's something most beginners don't expect: capital losses can offset capital gains dollar for dollar, and if your losses exceed your gains, you can deduct up to three thousand dollars against your ordinary income. Anything beyond that carries forward indefinitely. I've seen people completely ignore this part because they only think about their winning trades. You need to look at the net of everything — the losers and the winners together — before you figure out what you actually owe. There's also the Net Investment Income Tax, which adds another thirty-eight point nine percent effectively on top of your capital gains if your modified adjusted gross income puts you above the threshold — one hundred twenty-seven thousand dollars if you're married filing jointly, eighty thousand if you're single, and one hundred twenty-seven thousand five hundred for head of household. That thirty-point eight percent surtax applies to the lesser of your net investment income or the amount by which your MAGI exceeds the threshold. It's easy to miss because it doesn't show up on the 1099-B form. You have to calculate it yourself on Schedule D and Form 8960. State taxes are another layer that varies wildly. Some states like Texas and Florida don't tax capital gains at all. Others like California push effective rates well above forty percent when you combine state income tax with the federal portion. If you live in a high-tax state and you're planning a large sale, the timing matters because you can sometimes bunch gains into one year or spread them across two years depending on your situation, and that decision changes your state tax liability differently than your federal one.
The step-up in basis at death is worth knowing about even if it's not directly relevant to your current planning. Heirs who inherit assets get a basis equal to the fair market value on the date of death, which wipes out all the accumulated gain. It's one of the most efficient tax mechanisms in the code and it's under constant political discussion, but it's the law right now. If you're holding appreciated assets long-term and estate planning is part of your picture, this alone changes how you think about when to sell and when to hold. For actual tax preparation, I use TurboTax but I don't trust the first pass. The software usually handles straightforward sales correctly, but it misses things like the NIIT calculation, it sometimes mishandles wash sale adjustments if you have lots of them, and it rarely accounts for state variations properly. I cross-reference every return against my own spreadsheet before I file. This usually cuts the process down from about an hour of anxiety to maybe twenty minutes of verification, assuming your transactions aren't excessively complex. A couple of other things that catch people off guard. If you sell primary residence gain, up to two hundred fifty thousand dollars for singles and five hundred thousand for married couples filing jointly can be excluded if you've lived in the home for at least two of the last five years. That's a separate rule from investment property gains and it lives on Form 8949 with a special code, not on Schedule D in the same way. Municipal bond interest is generally exempt from federal tax but if you're dealing with private activity bonds, part of that interest might trigger the AMT. And collectibles like gold coins or artwork get taxed at a maximum twenty-eight percent rate, not fifteen or twenty. These edge cases don't affect most people, but if any of them apply to you, the wrong rate gets you an unpleasant surprise on audit.
Get the Full Details
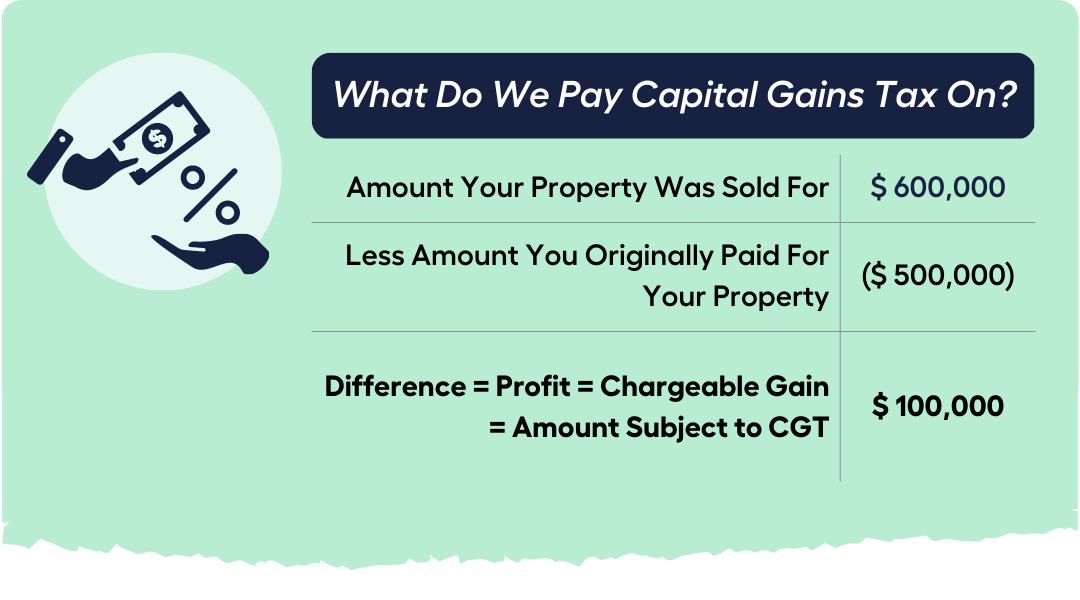
The bottom line is that the calculation itself is straightforward — gain equals sale price minus cost basis, then apply the right rate based on holding period and income. The hard part is getting all the pieces lined up: individual lot tracking, loss harvesting, state tax implications, and the NIIT that nobody remembers until they see it on their final tax bill. If you can document your basis accurately and run through the checklist above before you file, you'll probably land on the right number without needing a CPA unless your situation involves complicated pass-through entities or multiple properties.