Understanding What You're Actually Paying
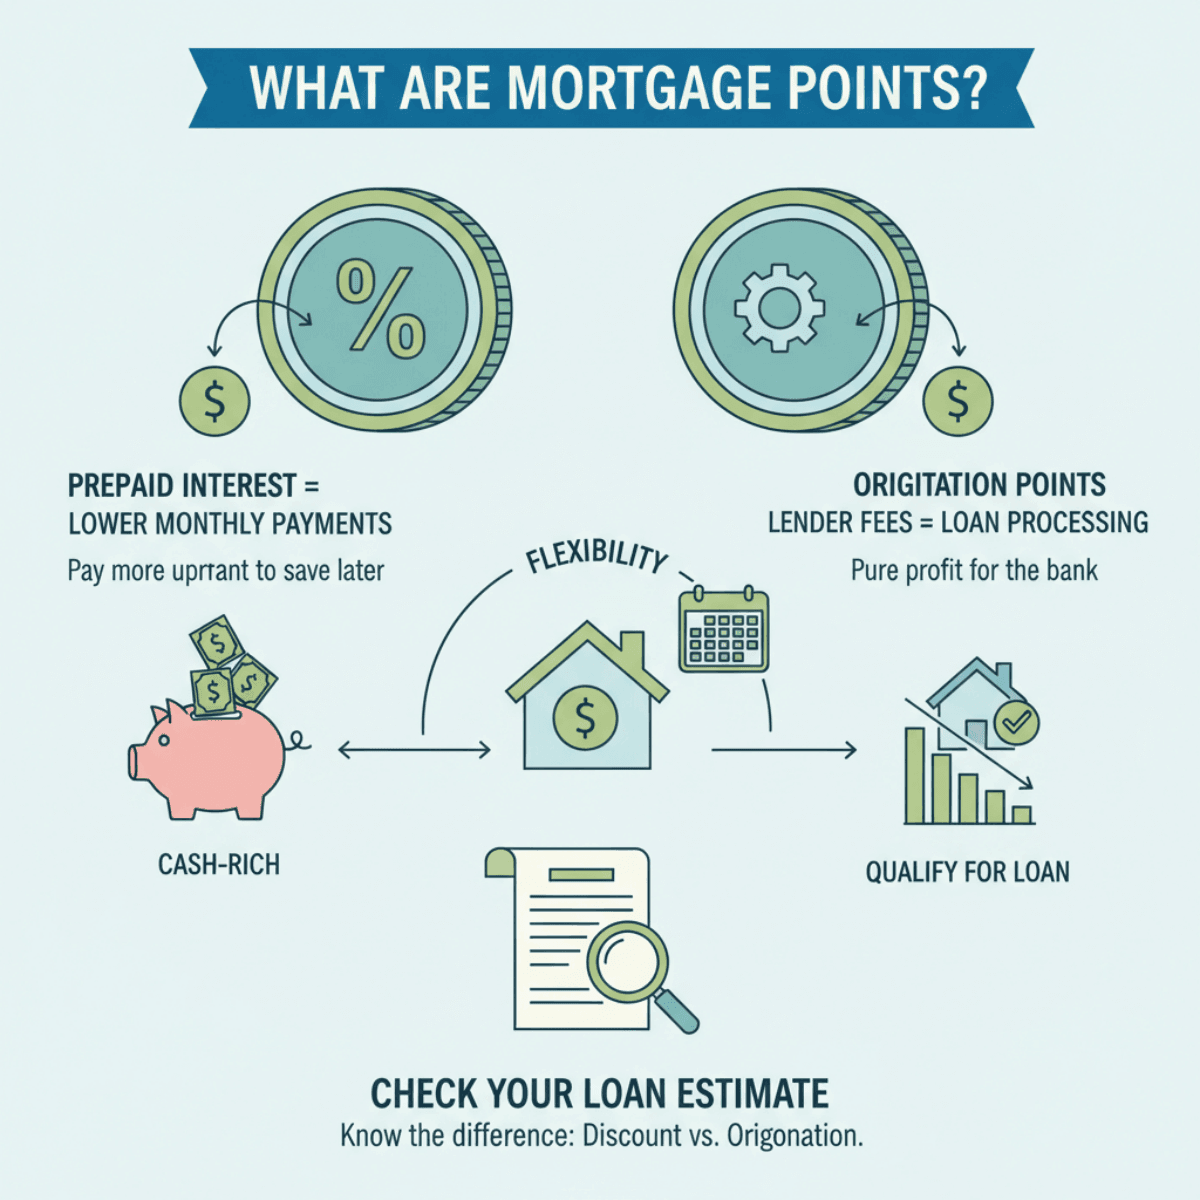
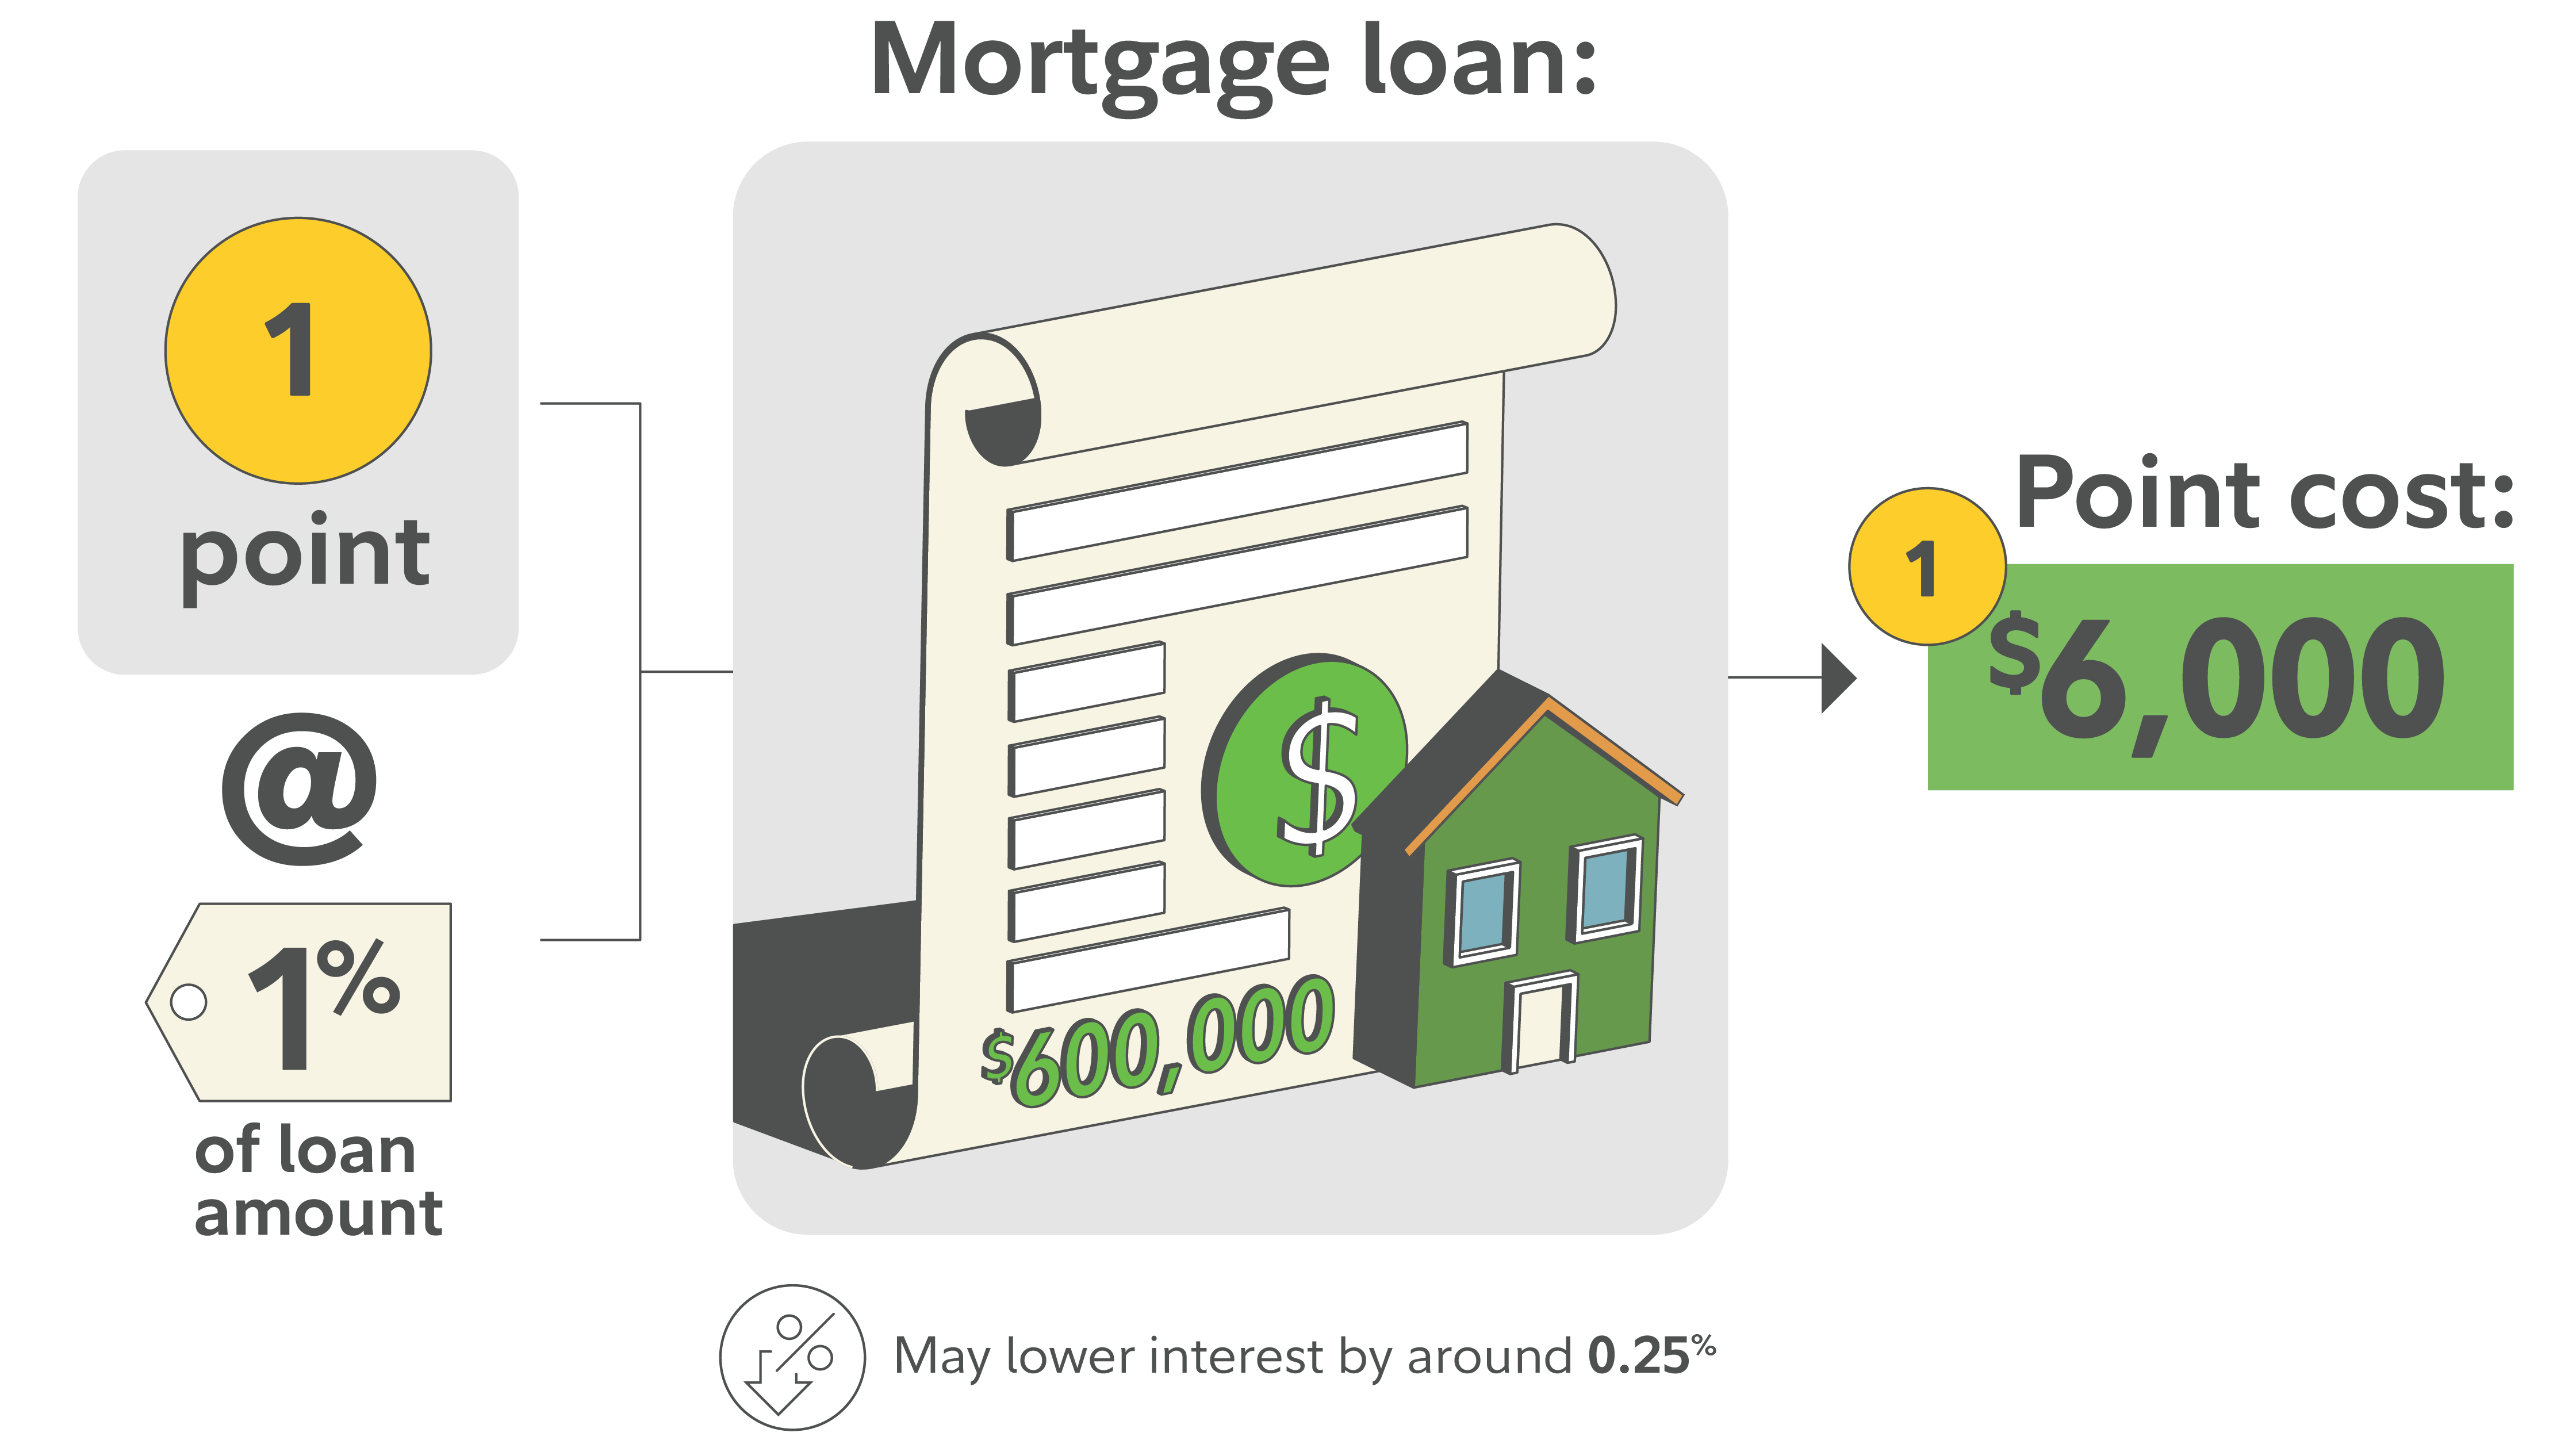
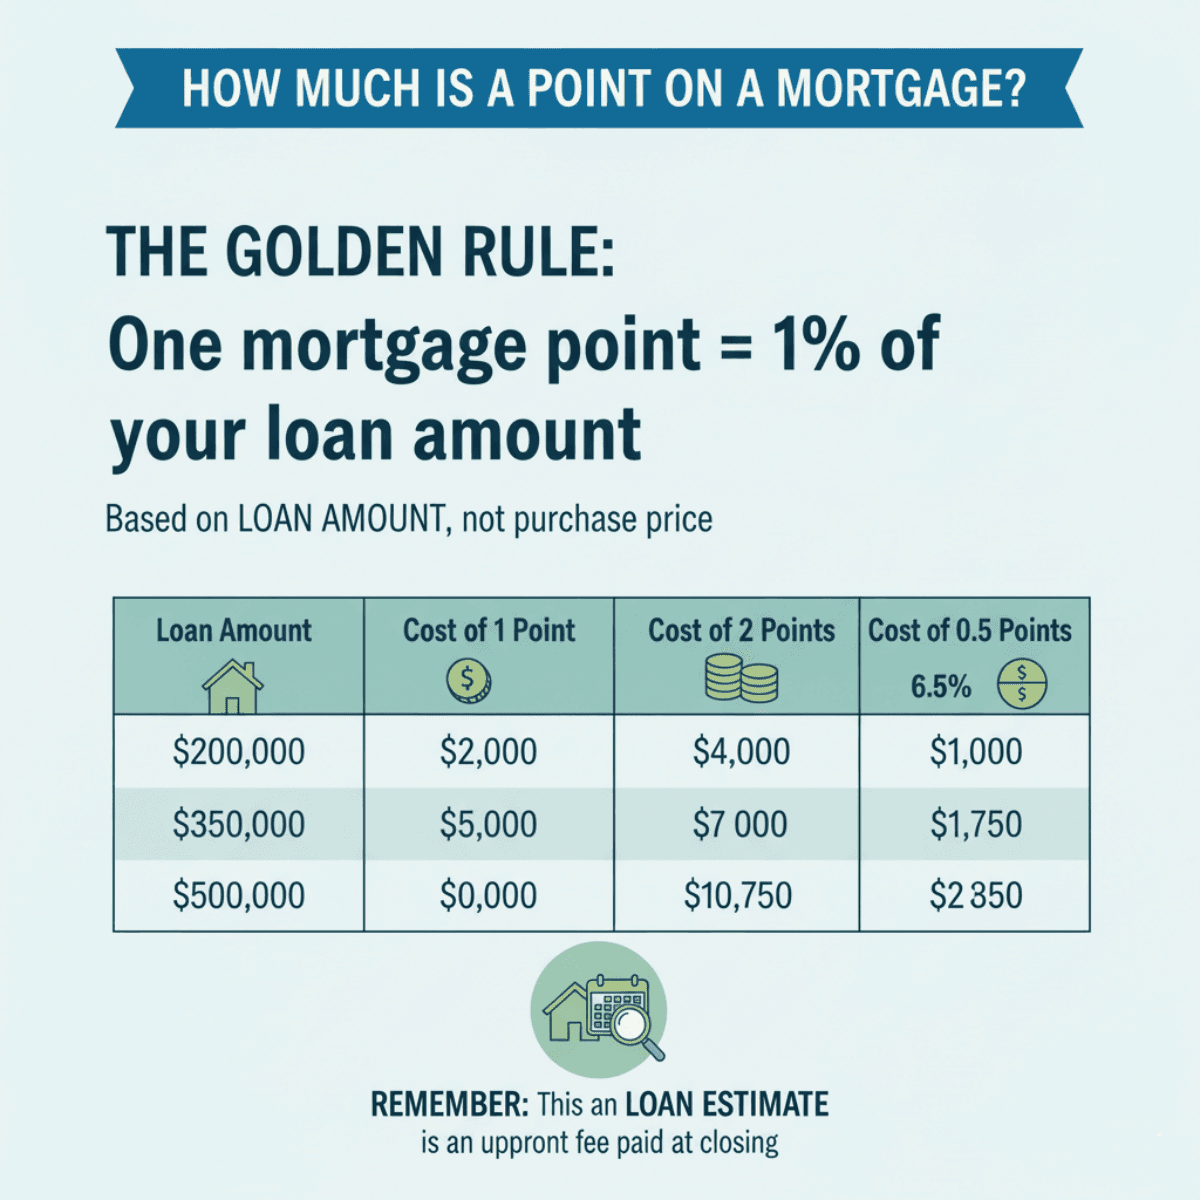
Mortgage points are upfront fees you pay to lower your interest rate. Each point costs 1% of your total loan amount. A single point on a $300,000 loan is $3,000. Two points would be $6,000. That part is straightforward arithmetic, but the decision of whether to buy them down or not is where things get tricky. The cost calculation itself is simple — multiply your loan amount by the number of points you want to purchase, then divide by 100. But knowing the cost is only half the equation. The real question is whether those points actually save you money over the life of the loan. And that depends on how long you stay in the home, what rate you're given without points, and what the discount rate looks like after you buy them down. I worked with a client last year who was refinancing a $425,000 loan. The lender offered two rates: 6.75% with zero points, or 6.25% with two points. Two points on that loan meant $8,500 out of pocket at closing. My first instinct was to run the breakeven analysis, which showed roughly 5 years and 3 months before the lower monthly payment made up the difference. She planned to sell in about four years, so buying points would have been a losing move. We went with the higher rate and saved her $8,500. That was the right call because her situation was short-term, even though the math looked decent on paper.
The Mechanics Behind the Numbers
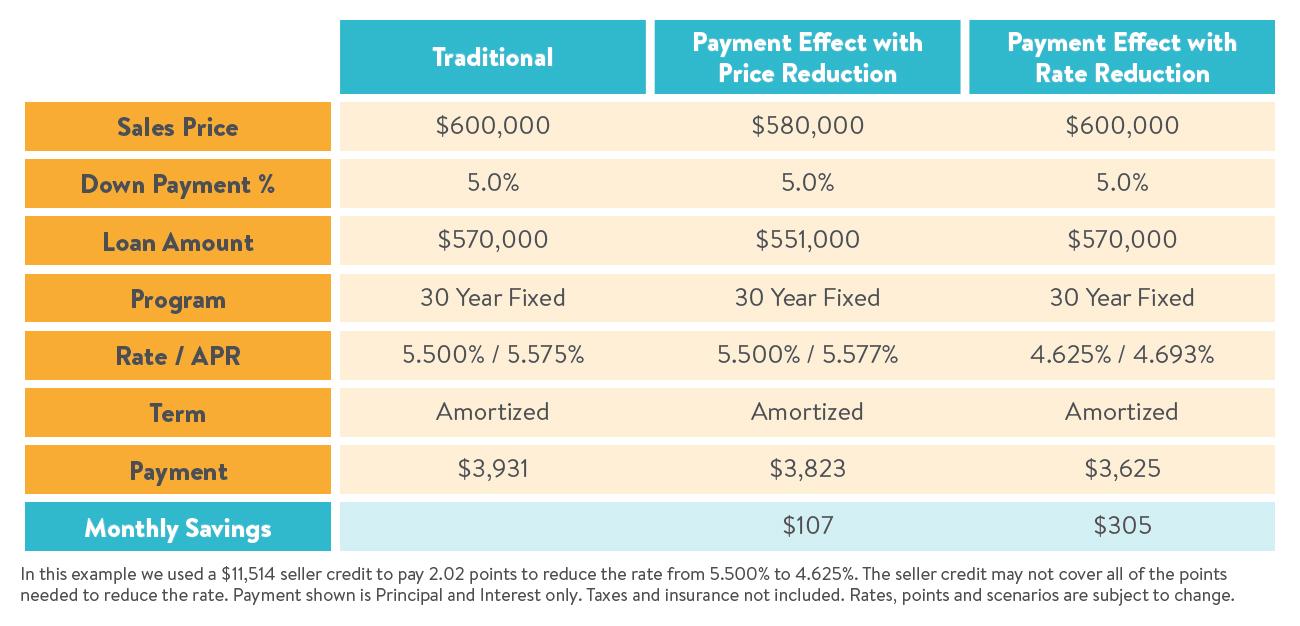
One point typically drops your rate by about 0.25%, though this varies by lender, market conditions, and your credit profile. Some lenders might offer a larger drop for jumbo loans or during periods of low rate volatility. The relationship isn't perfectly linear either. Sometimes the first point buys you 0.25%, but the second point might only get you 0.15% or 0.20% because lenders structure the discount schedule to make additional points less attractive. This is one of those details people miss when they're just looking at headline numbers. Breakeven analysis is the tool you need. Take your monthly savings from the lower rate and divide the total points cost by that number. That gives you how many months it takes to recover what you paid upfront. If you plan to move before that breakeven point, buying points is almost certainly the wrong decision. There are exceptions, and I'll get to them, but the breakeven framework should be your starting point every time. Here's a practical example that came up recently. A borrower had a $350,000 loan and was considering one point. One point cost $3,500. The rate dropped from 6.5% to 6.25%. Their monthly principal and interest payment went from about $2,212 to $2,158 — a savings of $54 per month. Dividing $3,500 by $54 gives a breakeven of roughly 65 months, or about 5.4 years. If they were planning to stay in the house for 10 years, buying the point made sense. If they were on the fence about moving in three years, it didn't.
Edge Cases and Complications
Not all points are created equal. There are borrower-paid points, which go straight to the lender and are the standard type discussed here. Then there are lender credits, where the lender gives you money back at closing in exchange for a higher rate. These are essentially the opposite of buying points and can be useful if you need cash at closing but accept a higher long-term rate. I've seen borrowers confuse the two and think a lender credit means they're getting a deal when they're actually paying more over the life of the loan. There's also the issue of points versus other closing costs. Some lenders bundle origination fees, application fees, and other charges into what they call "points" on the Loan Estimate form. The TRID disclosure makes this somewhat clearer now, but it's still possible to encounter situations where what looks like a point isn't actually reducing your rate at all. It's worth line-item reviewing every charge on your closing disclosure. If a fee says "discount points" but your rate didn't change, something is off. Another complication that catches people off guard: points are generally tax-deductible in the year they're paid, but only if they meet IRS criteria. The points must be for the purchase or refinancing of your primary residence, they must be calculated as a percentage of the loan amount, and they must be a customary charge in your area. Point payments on a second home, investment property, or home equity line of credit don't qualify. I once had a borrower who assumed his refinance points on a rental property were deductible. They weren't, and the oversight meant he overestimated his tax savings by nearly $400 that year.
Get the Full Details
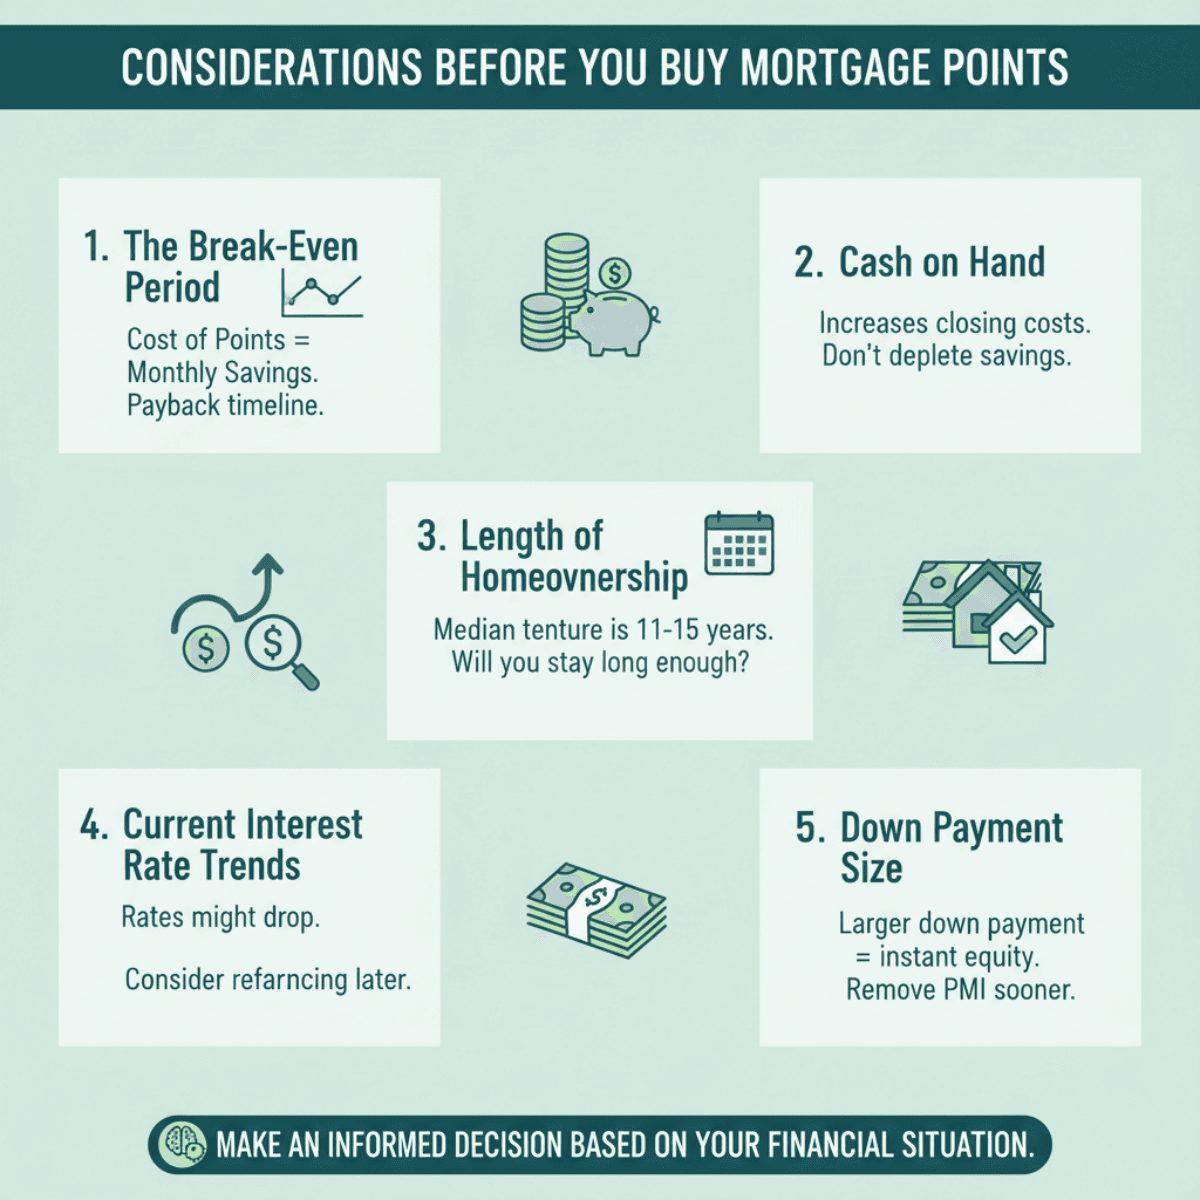
When Points Don't Make Sense
Buying points fails in several common scenarios. If you're likely to sell or refinance within three to five years, the math rarely works out. If you're already carrying high-interest debt elsewhere, putting $5,000 or $10,000 into mortgage points is a poor use of capital compared to paying down that debt first. And if you're short on cash at closing, using your reserves to buy points leaves you vulnerable to unexpected expenses during the transaction or shortly after. The other scenario where points are a bad bet is when the rate drop is smaller than advertised. During the volatile rate environment of recent years, some lenders offered aggressive discount schedules that they later adjusted. A rate sheet you see today might not be the one you lock at closing. Always confirm the exact rate you're locking and what the point cost is for that specific rate, not just what the marketing material suggests.
Practical Steps Before You Buy
Get at least three Loan Estimates from different lenders. Compare the interest rate, the points cost, and the total closing costs side by side. Don't just look at the rate — a slightly lower rate with heavy points might cost you more overall than a middle-of-the-road option. Ask each lender to itemize every charge so you can identify what's actually a discount point versus an administrative fee. Run the breakeven calculation for each option. Factor in your expected timeline in the home, any anticipated changes to your financial situation, and whether you have better uses for the same amount of cash. If you have a liquid retirement account earning 7% or more, using part of that to buy a 0.25% rate reduction is likely the wrong move — you'd be swapping a higher return for a lower one. It's counterintuitive for people to think about, but it comes up more often than you'd expect. The bottom line is that mortgage points are a legitimate tool for reducing your long-term interest cost, but they only work in your favor if you stay in the home long enough to recover the upfront expense. Run the numbers honestly, don't let a lower headline rate blind you to the total cost, and make sure the points are actually doing what the lender says they're doing. Most people who buy points regret it because they moved sooner than expected or didn't realize the rate drop was smaller than they thought. The math is clear if you take the time to do it properly.