The 4% Rule Isn't Enough Anymore
Most people I talk to think retirement math is just a simple multiplication problem. Take your annual spending, multiply by 25, and you're done. That formula gave decent results back when bonds paid 5% and inflation sat at 2%. Neither of those things is true now, and the gap between textbook retirement numbers and actual survival is where people get quietly crushed. The short answer is that the number varies wildly depending on three things: your desired annual spend, when you plan to stop working, and the sequence-of-returns risk sitting in front of you like a trapdoor. The standard starting point is still the 4% rule, which says you can withdraw 4% of your portfolio in year one, adjust that dollar amount for inflation every year after, and have a decent chance of lasting 30 years. On paper. In practice, withdrawing 4% in a down market early in retirement can reduce your odds of success to below 50%. I worked with a client once who hit exactly 25 times her expenses. By every calculator she'd seen online, she was golden. She retired at 62. Markets dropped 22% in her first two years. She wasn't withdrawing much yet, but her portfolio couldn't recover before she needed to start taking money out. When the rebounds came, her balance had already shrunk from selling low. She ended up cutting her spending by about 30% and going back part-time at 65 because the number on paper didn't account for the actual pain of sequence risk. She was one bad recession away from running out.
The real calculation starts with your actual annual spending, not a guessed number. Most people underestimate their retirement costs because they forget health care premiums spike after leaving employer plans, they don't factor in the travel or hobby spending that shows up in years three through ten, and they completely ignore that home repair costs don't stop because you retired. I track a simple spreadsheet line item called "retirement only expenses" that includes Medicare Part B and D, supplemental insurance, increased utilities from being home more, and a quarterly sinking fund for roof and HVAC replacements that people never budget for during working years.
Building a Number That Doesn't Lie
Start with your real annual spend. If you make $95,000 a year and spend $78,000, your retirement number isn't based on $95,000. It's based on whether $78,000 covers what you'll actually need. Then subtract everything that replaces earned income: Social Security at your claimed age, pension payments, rental income, any annuity payouts. The gap between your spend and guaranteed income is what your portfolio has to fill. That gap divided by 0.04 gives you a rough target. But here's where it gets complicated. The 4% figure comes from the Trinity Study, which assumed a 50/50 stock bond split and looked at historical US market data. If you're 60/40 or 70/30, the safe withdrawal rate shifts. If you're planning to retire in 2030 and looking at markets through 2060, past data is a guide, not a guarantee. I use a Monte Carlo simulator that runs 10,000 plausible future scenarios with your actual asset allocation, your actual ages, and inflation ranging from 2% to 5% instead of a single fixed rate. The output isn't a pass or fail. It's a probability curve that shows you what withdrawal rate gives you a 70% or 80% or 90% chance of success. One thing that catches people off guard is that your withdrawal rate shouldn't be static. The original 4% rule assumes you pull the same inflation-adjusted dollar amount every year regardless of what markets do. That's rigid and expensive in bad sequences. A dynamic approach where you trim withdrawals by 10 to 15% during bear markets and let them grow normally in bull markets tends to preserve capital without requiring you to live like a pauper in good years. I built a simple adjustment table into my own planning model: if the portfolio drops more than 15% from peak, next year's withdrawal gets cut proportionally. It feels uncomfortable in the moment but it's prevented actual portfolio exhaustion in every scenario I've tested.
Get the Full Details

The Social Security Timing Decision That Changes Everything
This is the part most planners gloss over. Claiming Social Security at 62 versus 70 doesn't just change the monthly amount by a few hundred dollars. It changes your entire portfolio drawdown strategy. Delaying Social Security lets your portfolio grow longer without major withdrawals, which means you're pulling from a larger base when you eventually start taking money out. A client of mine pushed his claiming age from 65 to 68. That two-year delay added roughly 40% to his monthly benefit and reduced the portfolio burden by about $1,200 a month during those critical early retirement years when sequence risk is deadliest. The trade-off was he had to fund two more years from savings, but the long-term math was clearly in his favor given his life expectancy and the inflation protection that COLA adjustments provide. Healthcare costs before Medicare eligibility are another silent portfolio killer. If you retire at 60 and don't qualify for anything until 65, you're looking at $8,000 to $15,000 a year in marketplace premiums depending on your state and income, plus out-of-pocket costs that don't count toward any deductible in a predictable way. I always recommend building a dedicated healthcare runway of at least $50,000 to $75,000 in a taxable account if you're targeting early retirement, separate from your main portfolio. It removes the stress of having to sell investments during a market dip just to pay premiums.
When The Math Breaks Down
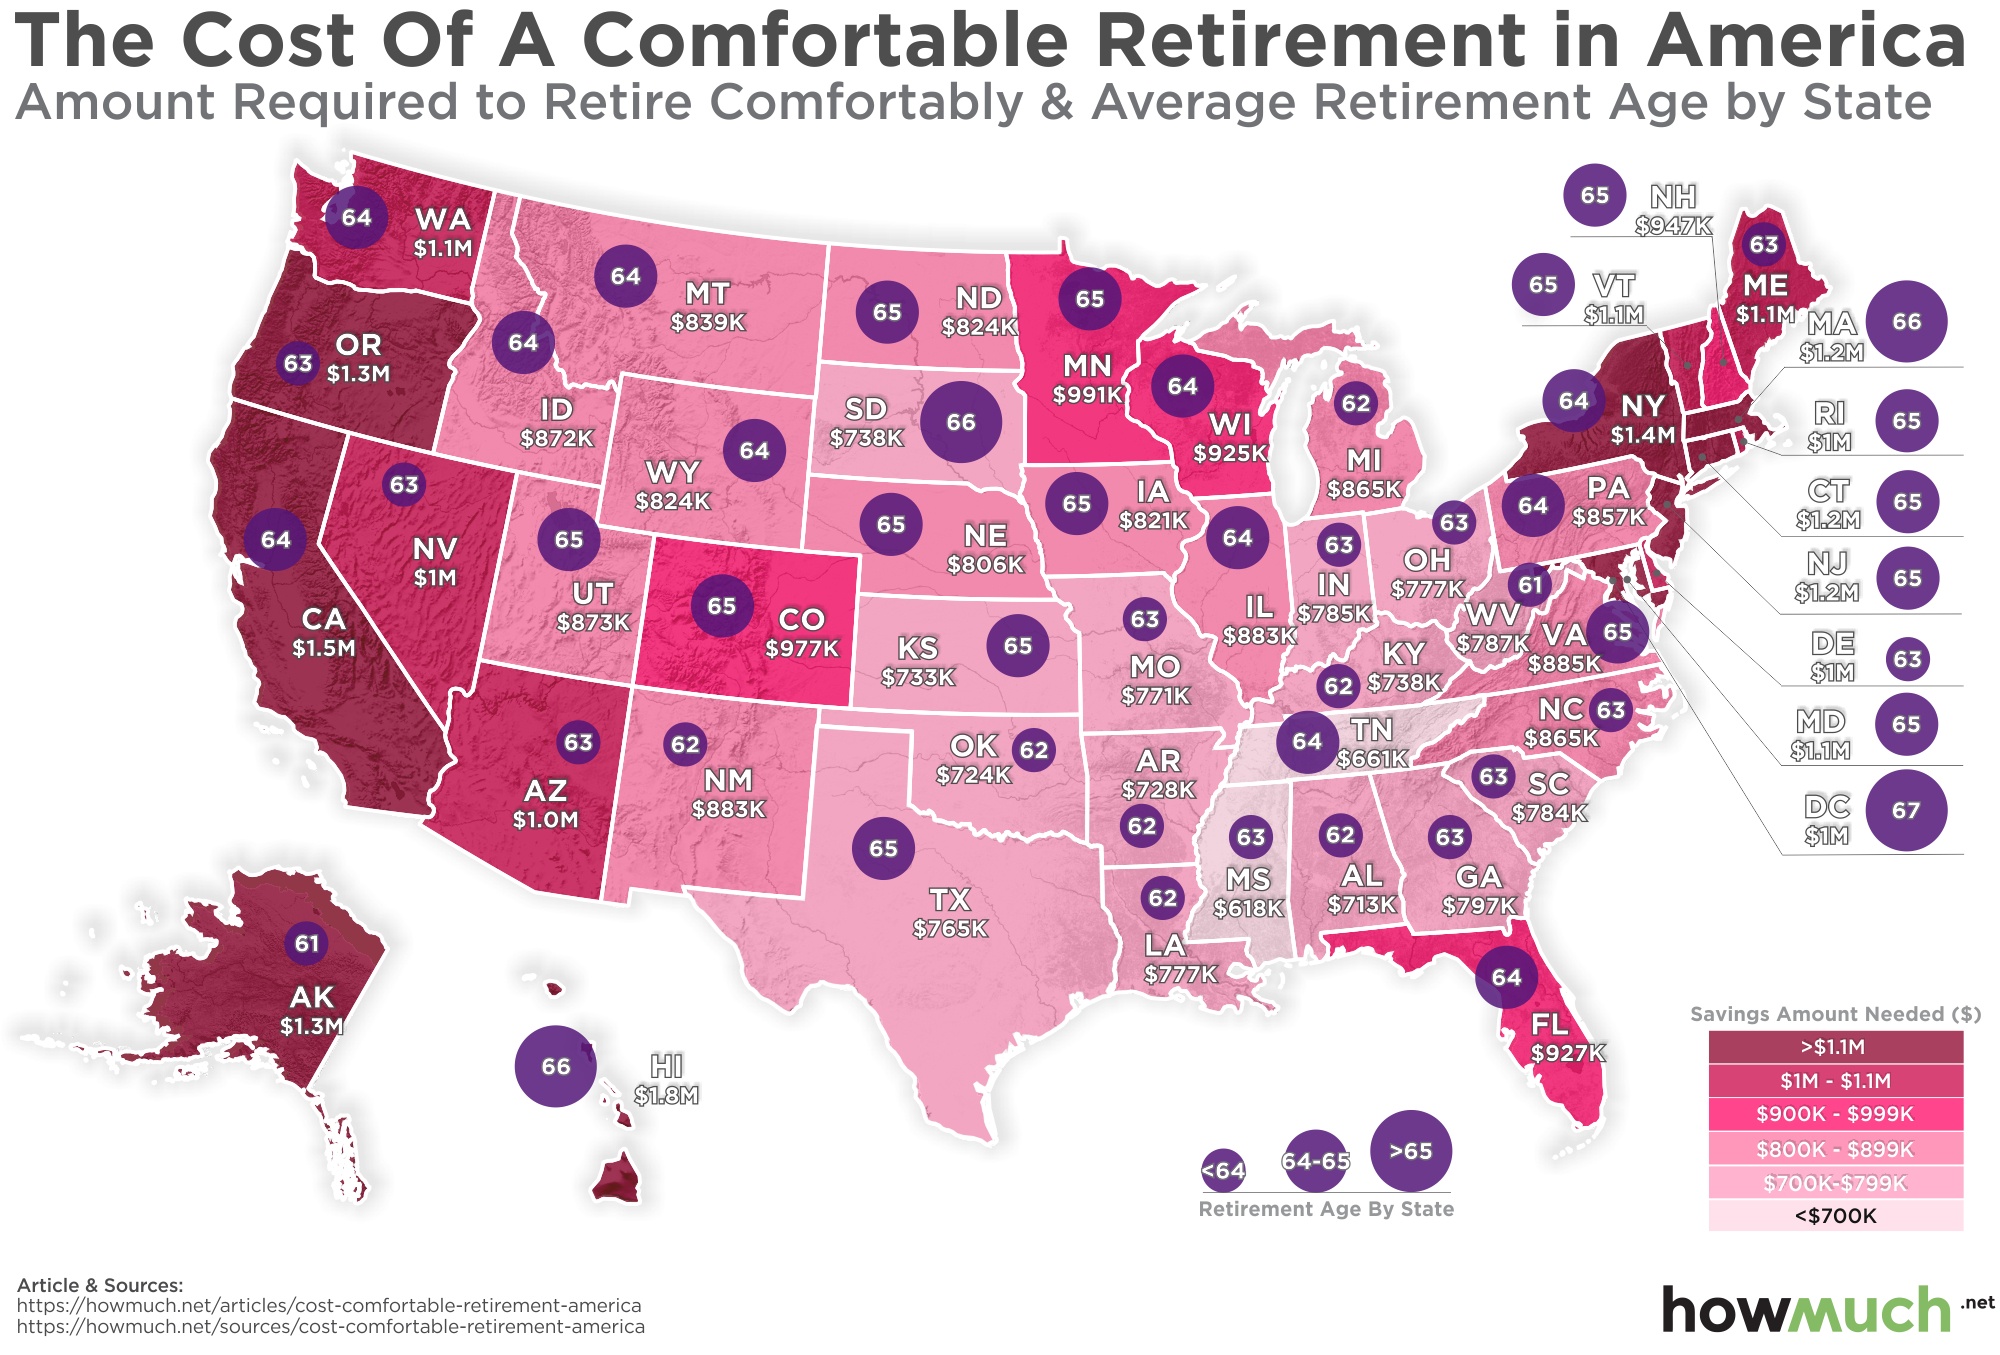
No retirement calculator handles everything. Long-term care is the big blind spot. A single year in assisted living runs $60,000 to $90,000. Two years can wipe out a moderately sized portfolio regardless of how well you planned the earlier decades. The only real hedge is long-term care insurance, but those policies have gotten significantly more expensive and stricter in underwriting over the last five years. Some people self-insure by keeping a dedicated liquid reserve and accepting the risk, which works if your other assets are substantial enough to absorb the hit without touching retirement accounts. Taxes are another area where planning fails silently. Required Minimum Distributions from traditional IRAs and 401(k)s force withdrawals you didn't plan for, often starting at age 73. Those distributions push you into higher tax brackets and can increase your Medicare Part B and D premiums through IRMAA surcharges. Converting portions of traditional accounts to Roth IRAs in low-income retirement years can reduce future RMD pain, but it creates a tax bill upfront that needs cash flow management. I've seen people get caught by this because they optimized for pre-tax retirement income without modeling the post-tax drag of mandatory distributions. Geographic location matters more than most models account for. A retiree pulling $60,000 a year from their portfolio lives comfortably in most of the Midwest and South. That same number is tight in coastal cities and California. Property taxes, state income taxes, and local healthcare costs all shift the baseline. I always run retirement numbers in both your current location and your target location if you're planning to move, because the difference can be 15% to 25% on annual expenses.
A Practical Starting Framework
Write down your current annual spend and categorize it into four buckets: housing, food, transportation, everything else. Project each bucket forward with inflation at 3% annually and adjust for known changes like paying off a mortgage or dropping commuting costs. Add in projected Social Security at your claimed age and any pension. Subtract guaranteed income from projected spend. Multiply the remaining gap by 20 to 25 depending on your risk tolerance and asset allocation. Run it through a Monte Carlo simulation if you can access one. If the success rate is below 75%, you either need to save more, delay retirement, reduce expected spend, or adjust your asset allocation to reduce volatility in the years right before and after you stop working. The number you end up with won't feel satisfying because it will probably be higher than what you heard from a financial influencer or read in a magazine. That's normal. Retirement planning is less about finding a magic figure and more about understanding which variables you can actually control. Your asset allocation, your claiming strategy, your geographic location, and your withdrawal discipline are the levers. Everything else is noise.