The Actual Numbers Behind Raising a Kid
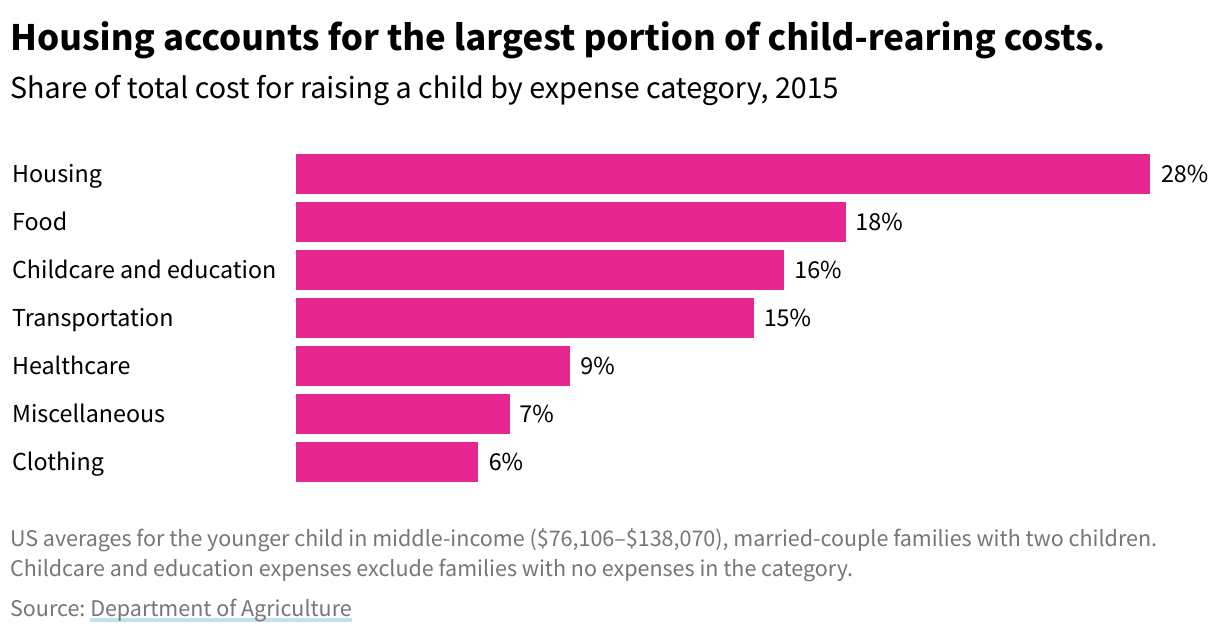
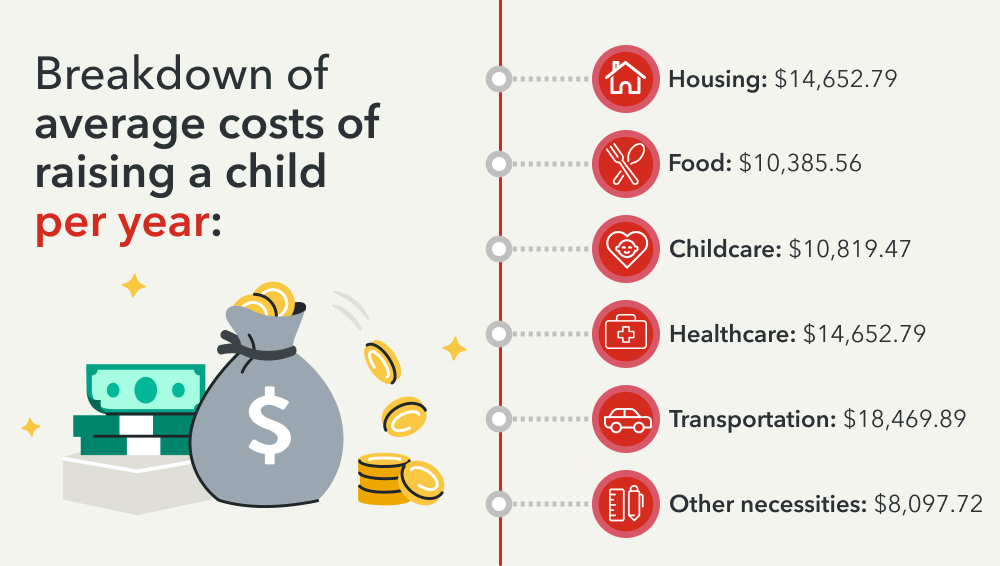
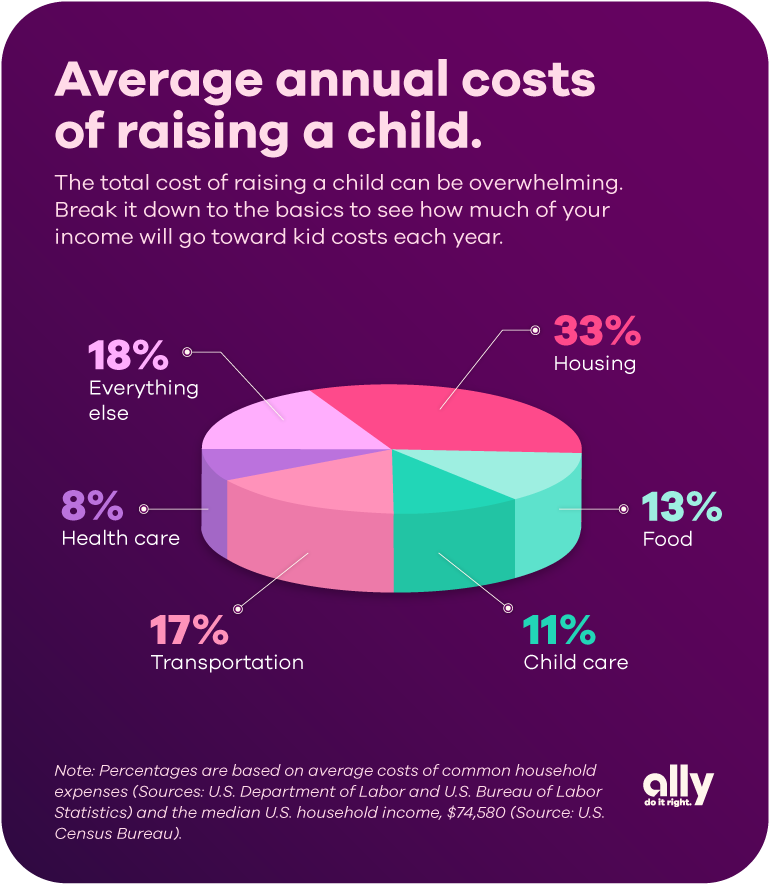
The USDA recently updated their estimate to about $23,000 to $28,000 per year for a child born in 2024, depending on whether you live in a high-cost urban area or somewhere more rural. That puts lifetime costs roughly in the $300,000 to $550,000 range before college. The spread is massive because it depends entirely on your zip code, your income bracket, and whether your kid goes to public or private school. Most online calculators give you one clean number, which is misleading by design. The question everyone wants answered right away, and the answer is complicated because housing, food, healthcare, childcare, and education are all line items that behave completely differently depending on who you are. I've been through this with two kids and helped several friends run the numbers, and here's what I actually learned after the fact. Childcare is the big one. In my area, infant daycare ran about $1,400 a month. By age four, when they qualified for pre-K, it dropped to around $900. That's a $16,800 annual difference alone. If you're dual-income and one parent stays home, that number vanishes, but so does half the household income. There's no free lunch there, just a different kind of cost.
Housing is where most people blow past their budget. I bought a three-bedroom condo instead of a two-bedroom house partly because I knew a kid was coming. The monthly payment was $600 more than my original plan. Over ten years, that's $72,000 in extra housing costs. You could have rented a much larger apartment for less, but I didn't want to uproot a toddler. Decisions like that add up quietly. Food costs come out to roughly $1,500 to $2,000 a year per child by the time they're eating like adults. Babies are cheap on food. Toddlers are unpredictable. School-age kids eat like small horses and then hit growth spurts where you go through three weeks' worth of groceries in four days. My second kid ate $400 a month less than my first did until he turned nine, then the gap reversed overnight. Budgeting for food is mostly guesswork. Healthcare is another category that surprises people. Even with insurance, copays, prescriptions, dental, and vision add up. I tracked our out-of-pocket medical spending for both kids over five years. It averaged about $800 a year per child, but the distribution was lopsided. One year my oldest had braces and a surgery, and our medical costs jumped to nearly $3,000. The next year was under $400. You need a health savings account or some kind of buffer for the fat years.
School expenses are deceptively low if you're in a public school district. Books, supplies, field trips, and lunch money might total $500 to $1,000 a year. Private schools start at $10,000 and go well past $30,000 at the high end. The difference between public and private is the single largest variable in the entire equation, and it's the one parents talk about least until they're already committed. Extracurriculars are where budgets really fracture. Soccer camp, piano lessons, coding class, travel team fees, band uniforms. I kept a spreadsheet for my younger kid's activities and tracked it for three years. We spent about $2,200 annually on structured activities, not including the equipment we bought and abandoned after six weeks. The average family probably spends between $800 and $4,000 here depending on how many things the kid actually sticks with. Clothing and gear are another category with huge variance. Newborn clothes are expensive per item but last maybe two months. Then you buy hand-me-downs or shop secondhand and the cost drops dramatically. Car seats, strollers, cribs, high chairs — a lot of this is either rental quality or something you'll sell back for 30 percent of what you paid. I've resold two cribs, three strollers, and four car seats over the years. The resale market for baby gear is real if you shop smart.
Get the Full Details
Here's something most cost calculators miss: opportunity cost. If one parent reduces hours or leaves the workforce entirely, that's often a $30,000 to $80,000 annual loss in household earnings, plus long-term retirement impact. Some families absorb this willingly. Others don't factor it in at all. It's a real cost whether you call it one or not. The other thing nobody talks about is geographic adjustment. A family making $80,000 in rural Alabama raises a child for significantly less than a family making $120,000 in San Francisco, even though theSF family has more income. Housing, childcare, and even groceries can be twice as expensive in coastal cities. The USDA calculator has regional adjustments built in, but most online tools don't. Use a calculator that accounts for your metro area or the numbers will be wrong. I ran into a specific edge case that I wish I'd known about earlier. My first child's pediatrician was in-network, but the urgent care center near our house wasn't. I took him in once for a suspicious ear infection and got a bill for $280 that my insurance only covered at the out-of-network rate. After the copay, I owed $147. That one mistake taught me to check every provider against my insurance directory before booking appointments, not after. I maintained a folder of in-network specialists for both kids from day one. It saved me probably $2,000 over five years in unexpected bills.
Another thing that trips people up: tax benefits are fragmented. The Child Tax Credit gives you $2,000 per child, but it's partially non-refundable. The Child and Dependent Care Credit can cover up to $3,000 in qualifying expenses ($6,000 for two kids), but you have to actually pay for eligible care to claim it. If you have a grandparent watching the kid for free, you get nothing from that credit. State-level benefits vary wildly too. Some states offer monthly child allowances, others offer nothing. Check your state's department of revenue website before you assume the federal numbers are the whole picture. College savings is a separate beast entirely. 529 plans have tax advantages, but contributing $200 a month per child from birth to age 18 at a 5 percent average return gets you roughly $75,000 per kid. That covers public in-state tuition comfortably and private maybe not at all. If you can't contribute consistently, even small amounts matter because compound interest is brutal in reverse. Starting at age ten instead of age five cuts your final balance by nearly half, all else equal. If you want a practical way to estimate your own situation without getting lost in national averages, start with your actual monthly expenses and add line items. Track childcare if you're paying for it. Add food delta — how much more does your grocery bill go up when a second person starts eating? Add healthcare out-of-pocket. Add housing delta if you moved for space. Add school and activity costs based on what you actually plan to spend, not what the internet says is typical. Then multiply by 18. That gives you a number closer to your reality than any generic calculator ever will.
The honest answer to How Much Does It Cost To Raise A Child is that it depends on everything except the child itself. Your income, your location, your insurance, your choices about school and activities, whether you have help from family, and how much you value time versus money all determine the final number. The range is wide on purpose. There is no single cost. There's just your cost, and you figure it out the same way I did — by tracking what actually leaves your bank account each month and accepting that the estimate will be wrong anyway.