Where to Start With Extra Mortgage Payments
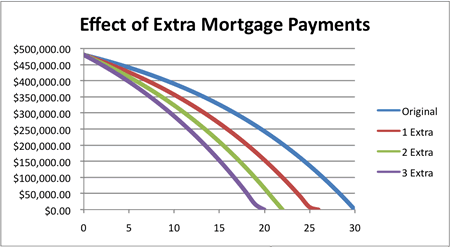
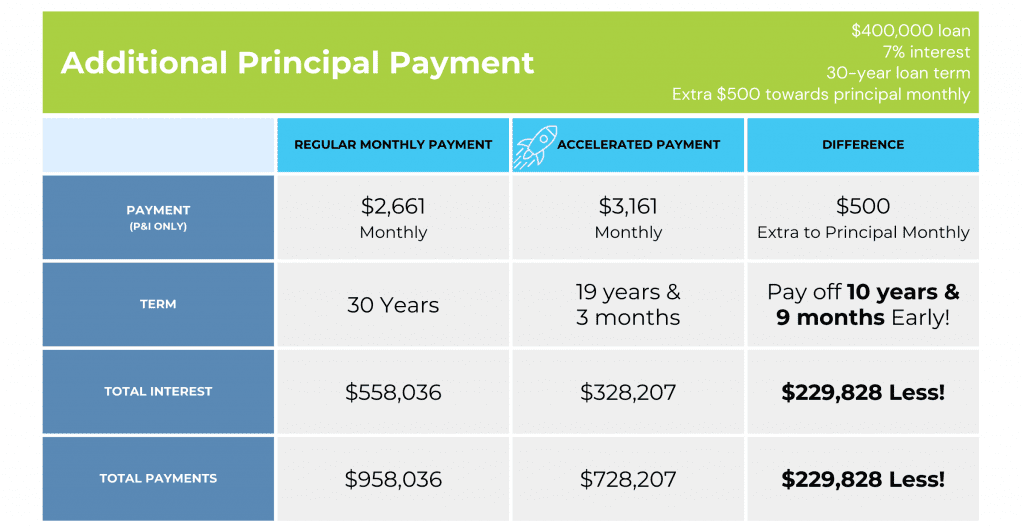
Most lenders will accept extra principal payments without any special permission, but that doesn't mean they apply them correctly. I learned this the hard way when I sent a $10,000 supplemental payment to my own mortgage servicer in 2018. Half of it went toward that month's interest and escrow reserve instead of the principal balance. I had to call their servicing department, fill out a written "principal-only" designation form, and wait three weeks for the correction to post. During those three weeks my balance hadn't moved at all, even though I'd clearly sent extra money. That experience made me a lot more careful about how I handle this going forward. Once you actually get the extra payment applied correctly, the savings are straightforward. On a 30-year fixed at 6.5% with a $300,000 balance, adding $200 per month to your principal payment cuts roughly four years off the loan and saves about $28,000 in total interest. Add $400 and you're looking at roughly five and a half years shaved off and $42,000 in interest elimination. The reason this works is simple compounding — each extra dollar reduces your principal, which reduces the interest calculated the following month, which then frees up more of your regular payment to go toward principal the month after that. It's a self-reinforcing loop that accelerates as your balance shrinks.
Figuring Out How Much Extra Principal Should I Pay On My Mortgage
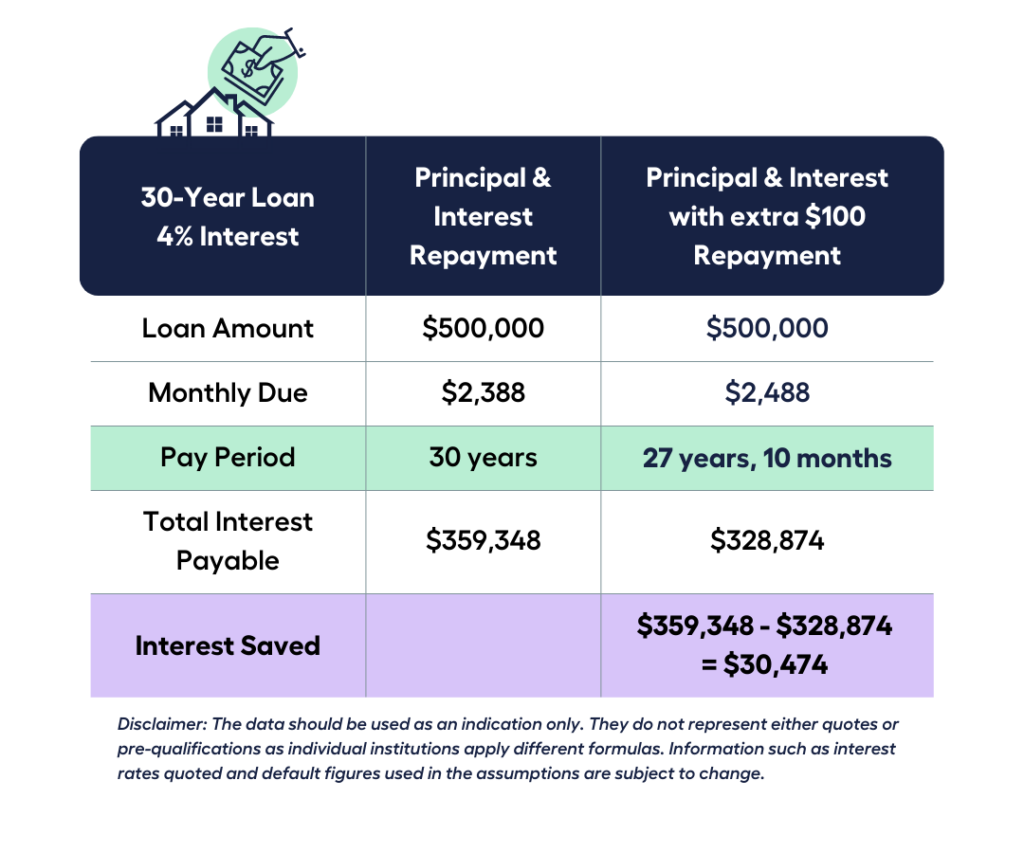
The honest answer is that it depends on your rate, your remaining balance, and what else you could do with that money. The rule of thumb most financial writers repeat is to target the gap between your mortgage interest rate and your expected investment return. If you're paying 6.5% on your mortgage and your retirement portfolio averages 7% or 8% annually, the math actually favors investing the extra cash rather than prepaying. The spread is only 1.5 to 2 percentage points, and over 20 years that compounds in your favor on the investment side. But if your rate is 8% or higher, or if you simply don't trust the market to deliver consistent returns, prepaying becomes the safer bet. There's also the tax angle that most people skip. If you itemize deductions, every dollar of mortgage interest you eliminate is a dollar of lost tax benefit. At the top end that might cost you 25 to 37 cents per dollar depending on your bracket. So a 6.5% mortgage rate effectively becomes maybe 5% after taxes if you're itemizing. It changes the calculus slightly, and for high earners it can push the decision toward investing instead of prepaying. On the practical side, there's a minimum threshold that actually moves the needle. An extra $50 a month on a $300,000 loan at 6.5% saves roughly $4,500 in interest over the full term. It's not dramatic but it's real. An extra $200 saves significantly more because of the compounding effect I described. If you can consistently add $200 or more, the difference in total interest paid over the life of the loan is substantial. Below that, you're still saving money but the impact is modest enough that the administrative hassle of tracking it may not be worth it for some people.
How Your Servicer Actually Handles the Payment
This is where things get messy and where most people lose money without realizing it. Different servicers have different default behaviors. Some automatically apply any excess to principal. Others apply it to the next month's payment first, then the month after that, then eventually principal. A few hold it in a suspense account until you contact them. I've dealt with all three versions across different loans over the years, and the one that cost me the most was the suspense account version — my extra $5,000 sat unapplied for six weeks while I figured out what was happening. The workaround I use now is to call my servicer before making any large extra payment and ask three specific questions: how extra payments are applied by default, whether I need to submit a written form to designate principal-only treatment, and how long it takes for the application to post. If the answer to any of those is unclear, I send a certified letter with explicit instructions along with the payment. It feels excessive but it creates a paper trail that actually matters when something goes wrong. I once had to dispute a missed application and the letter was the only thing that resolved it within two weeks instead of two months. Biweekly payment programs are another route worth considering. These split your monthly payment in half and auto-deduct every two weeks, which results in 26 half-payments per year instead of 24. That's one full extra payment per year built in automatically. Some servicers offer this directly, while others charge setup fees of $100 to $300. The math works out the same whether you do it through the servicer or on your own — sending half payments every two weeks manually produces identical results without the fee. I switched to the manual version once the servicer tried to charge me for their program.
Get the Full Details
Edge Cases and Situations Where This Strategy Fails
Not every mortgage benefits from aggressive prepayment. If your loan has a prepayment penalty — common on some FHA, VA, and jumbo loans in the first two to five years — you could lose money by paying extra. These penalties typically range from 2% to 5% of the prepaid amount and can wipe out your interest savings in a single quarter. Pull your closing documents and look for a prepayment clause before you commit to anything beyond your normal payment. Another situation where prepayment makes less sense is when your loan is already deep into its amortization schedule. On a 30-year loan, by year 20 most of your payments are already going toward principal. The remaining interest savings from extra payments in years 25 through 30 are minimal compared to what you'd save in years 1 through 10. If you've already paid a decade or more, the optimal strategy might be to redirect those extra payments toward higher-interest debt or investments instead. There's also the opportunity cost problem that gets overlooked. If you have credit card debt at 20% or a personal loan at 12%, paying extra on a 6% mortgage is financially backwards. The debt at 20% is costing you far more than you're saving on the mortgage. I've talked to plenty of homeowners who were aggressively prepaying a 5.5% mortgage while carrying $8,000 in credit card debt at 22%. They were literally setting money on fire.
Some loans also have balloon payments or unusual structures that make extra principal payments risky. If your loan requires a large lump sum payment at a certain date, reducing your balance unnecessarily could create liquidity problems down the line. I saw this with a client who had an ARM with a five-year balloon. She was making extra principal payments toward the end of her ARM period, which reduced her balance but left her unable to qualify for the refinance that would have replaced the balloon payment. She ended up in a much tighter position than if she'd kept the balance higher and maintained more cash reserves.
What I'd Actually Recommend
Start by pulling your most recent mortgage statement and noting your current balance, rate, and remaining term. Run it through a mortgage acceleration calculator — many are free online — to see the interest savings at different extra payment amounts. Then check your loan documents for prepayment penalties. Call your servicer and confirm their extra payment policy in writing if possible. Decide on an amount you can sustain for at least five years, not just the next few months. Consistency matters more than size. An extra $100 a month maintained for fifteen years saves more than a $1,000 payment followed by nothing. If your mortgage rate is below 5% and you have a solid emergency fund and no high-interest debt, the smartest move might be to invest the extra cash instead. The guaranteed return from prepaying a low-rate mortgage is real, but so is the potential return from a diversified portfolio. Both are valid strategies. The worst outcome is making a decision based on emotion rather than numbers. Track your progress. Log each extra payment and verify it posted to principal within 30 days. If your servicer consistently misapplies payments, consider switching. The right servicer makes this process automatic and transparent, which removes the friction that causes most people to stop making extra payments after a few months. Once the habit is established and the servicer is reliable, the savings accumulate quietly in the background without requiring ongoing attention.