Breaking Down the Monthly Payment on a $200,000 Home
Most people who ask this question are surprised by how many moving parts actually go into a mortgage payment. The headline number everyone looks for — the monthly figure — is only one piece of it. I used to give quick answers at dinner parties, then realized half the time the person asking didn't even know what rate they'd be working with or how much down they could put down. So let's just walk through it methodically. At a current market rate around 6.5% with a 30-year fixed loan and 20% down, your principal and interest payment lands near $1,010 a month. That number alone doesn't tell the whole story. Property taxes, homeowners insurance, and possibly private mortgage insurance (PMI) sit on top of that, and those can add another $400 to $700 monthly depending on where you live. In a high-tax area like New Jersey or parts of Texas, property taxes alone can exceed $300 per month on a 200K home. In low-tax states like Hawaii or Alabama, you might be looking at under $100. The P&I stays relatively consistent. The rest floats based on your location and lender requirements. If you put less than 20% down, PMI kicks in. On a $200,000 purchase with 10% down, that's a $180,000 loan. At 6.5%, the P&I drops to roughly $875. But you'll add PMI at about 0.5% to 1% of the original loan amount annually, which works out to $75 to $150 a month until you hit that 20% equity mark. Some lenders will let you cancel PMI once you reach 78% of the original value based on the amortization schedule alone. Others require a formal request or a refinanced rate drop before they'll drop it. This varies by lender and loan program, so don't assume anything.
I ran into this exact issue with a borrower last year — she had an FHA loan at 3.75% on a $200,000 property and was paying $1,100 in P&I plus $120 in MIP (mortgage insurance premium), plus about $200 in escrow for taxes and insurance. She thought she was overpaying until we recalculated everything against her actual property tax bill, which her lender had estimated conservatively. Her actual taxes came in at $1,800 annually, not the $2,400 her escrow analysis had projected. That $600 discrepancy meant her monthly escrow shortage was smaller than feared, and we adjusted accordingly rather than forcing a refi she didn't need.
What Drives the Number Up or Down
Interest rate is the big one, obviously. A half-percent difference between 6.0% and 6.5% on a $180,000 loan over 30 years changes your P&I from about $878 to $1,080. That's over $200 a month, or $72,000 extra paid over the life of the loan. Points can shift the rate too. Buying one discount point at closing — costing 1% of the loan amount, so $1,800 in this example — might drop your rate by 0.25%. Whether that makes sense depends on how long you plan to stay in the home. If you're moving in five years, the math rarely works in your favor. If you're staying ten or more, it often does. The loan term itself matters a lot more than people realize. A 15-year fixed at 5.5% on the same $180,000 loan brings the P&I to roughly $1,450 per month. Higher monthly payment, yes, but you'll pay about $78,000 less in total interest over the life of the loan compared to the 30-year version at 6.5%. That's a genuine trade-off worth running on paper before committing. I've seen plenty of buyers jump straight to the lowest monthly payment without calculating the total interest cost, then regret it when they realize they're building equity slower than they expected. Another thing that trips people up: the difference between the note rate and the APR. Your note rate is what your payment is calculated on. The APR includes the note rate plus lender fees, points, and other closing costs amortized over the loan term. It's supposed to give you a fuller picture of what the loan actually costs. Sometimes the APR is misleading though — especially with no-closing-cost loans where the rate is higher but fees are rolled in or waived. Two lenders might advertise the same rate, but one could have $3,000 in origination fees while the other charges $800. The actual payment and total cost diverge significantly even if the monthly figure looks identical on the surface.
Get the Full Details
Quick Reference Scenarios
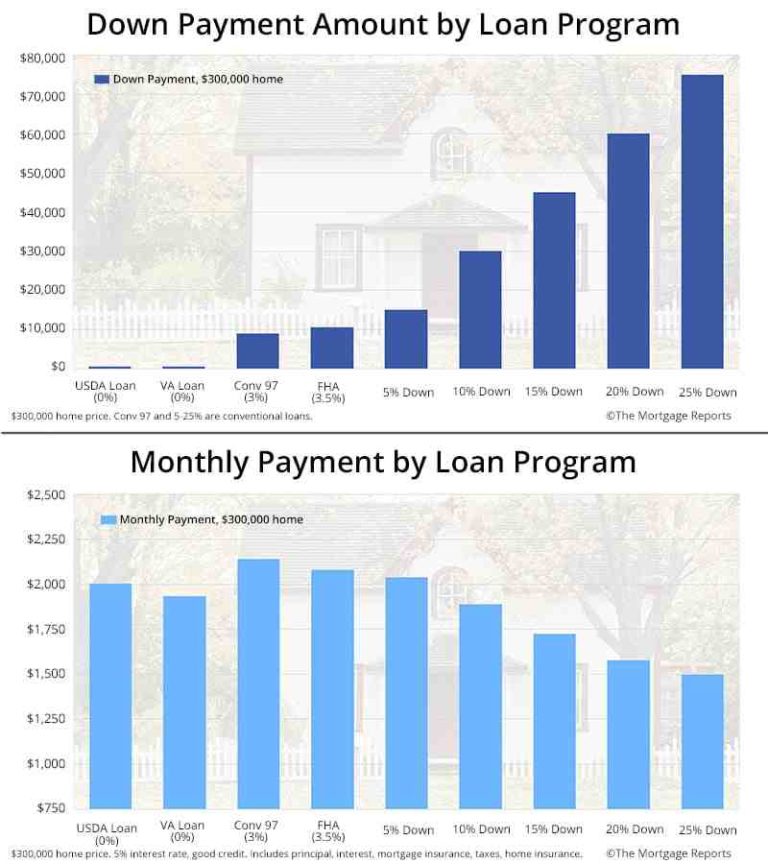
Here's a rundown of what the numbers look like across different down payment and rate combinations, assuming a 30-year fixed and including estimated taxes and insurance but excluding PMI where relevant: 20% down ($40,000), 6.5% rate: P&I of ~$1,010, total with escrow ~$1,360/month 10% down ($20,000), 6.5% rate: P&I of ~$875, plus PMI ~$90, total with escrow ~$1,265/month
5% down ($10,000), 6.75% rate: P&I of ~$840, plus PMI ~$100, total with escrow ~$1,240/month 0% down (VA loan), 6.25% rate: P&I of ~$1,108, no PMI but a 1.5% VA funding fee (~$2,700) typically financed into the loan, total with escrow ~$1,408/month These are rough estimates. Actual numbers depend on your credit score, debt-to-income ratio, the lender's specific fee structure, and your state's property tax rates. A credit score of 740 versus 680 can swing your rate by a quarter to half a point, which matters more at these price levels than most buyers account for.
Where It Falls Apart
Calculators and estimates only get you so far. They don't account for HOA fees, which can add $200 to $500 monthly in certain communities. They don't capture special assessment risk if your area has aging infrastructure. They also don't reflect the fact that property taxes can reassess upward when you buy, depending on your state's rules. In some states, the purchase price triggers a full reassessment, which can bump your tax bill overnight by 20% or more. California's Proposition 13 is the famous exception where taxes stay locked to the previous owner's assessed value, but that's the outlier, not the rule. The other practical limitation: if your debt-to-income ratio is above 43%, which is the standard back-end DTI cap for qualified mortgages, you might not qualify for the full loan amount regardless of what the calculator says. Some lenders will go higher with non-QM products, but the rates on those are usually a full percentage point or more above conventional pricing. If you're close to the threshold, it's worth getting pre-approved before you fall in love with a house, because the approved amount might be lower than the sticker price. If you want to run the numbers yourself, there are free calculators at sites like Bankrate, NerdWallet, and the Consumer Financial Protection Bureau's own mortgage calculator. They're accurate enough for planning purposes. Just make sure you're inputting your actual estimated property tax and insurance figures rather than letting the calculator auto-estimate, because those defaults are often wildly off for your specific zip code.