Valuing a tax practice isn't as simple as multiplying revenue by a number
I sold my own tax practice five years ago and went through the whole process of figuring out what it was actually worth. The buyer wanted a simple multiple of gross receipts. I had to explain why that approach would leave tens of thousands of dollars on the table. The reality is that a tax practice's value depends on several moving parts, and most people get this wrong because they only look at the top line. The standard approach uses adjusted seller discretionary earnings, which means you take gross revenue, subtract cost of goods sold, remove one-time expenses, and then apply a multiple based on risk factors. For tax practices specifically, the multiple typically lands between 2.5x and 4x SDE, but that range hides a lot of nuance that matters enormously to the final number. A practice doing $500,000 in gross revenue with $120,000 in direct costs and $40,000 in add-backs would have an SDE of roughly $340,000. Applied against a 3x multiple, that gives you about $1,020,000. But here is where most people miss the mark: the multiple shifts based on client concentration, staff dependency, software ownership, and whether the books are clean enough for a buyer to underwrite without fear.
I ran into a specific problem with a client who had about 60% of their revenue coming from a single large corporate client who filed quarterly estimated returns. The buyer's due diligence team immediately flagged this as a critical risk. One loss of that client would drop the practice's SDE by nearly two-thirds overnight. We restructured the deal by adjusting the multiple down from 3.2x to 2.4x on the projected earnings and built in an escrow holdback tied to client retention for the first 18 months. The final sale price was about $680,000 instead of the $940,000 my client originally hoped for. It was a hard lesson that client concentration can destroy valuation faster than almost anything else.
Revenue quality matters more than revenue amount
Two tax practices can both bring in $400,000 annually, but their values could differ by 40% or more. The difference comes down to recurring versus one-time work. A practice built primarily on annual tax preparation engagements has significantly more predictable revenue than one that relies on cyclical advisory projects, audit defense retainers, or business formation fees that come and go with economic conditions. Buyers pay a premium for predictability because they know exactly what cash flow they are getting. Bookkeeping and payroll services are the gold standard for recurring revenue in a tax practice. These services generate monthly income that continues regardless of tax season, which means the practice has value even during the nine months outside the January through April window. A practice with 40 bookkeeping clients paying an average of $400 per month generates $192,000 in recurring revenue that doesn't disappear after April 15th. That revenue stream alone can add 15% to 25% to the overall practice valuation because it reduces the seasonal risk that plagues pure tax preparation practices. Another factor buyers scrutinize is gross margin. If your practice has high gross margins, it tells the buyer that your pricing is strong and your delivery model is efficient. A practice with 70% gross margins is fundamentally different from one struggling at 40%. The higher-margin practice can absorb staff turnover, invest in better technology, and still deliver healthy earnings. The lower-margin practice is one bad year away from losing money.
Get the Full Details
The software question nobody asks early enough
Who owns the software licenses matters more than most sellers realize. If your practice runs on ProSeries, Lacerte, or UltraTax and those licenses are registered under your personal name or a previous company structure, the buyer cannot legally transfer them. You need to either convert them to a business entity before listing or negotiate who absorbs the cost of new licenses as part of the deal. I saw a deal fall apart completely because the seller's software licenses were tied to an LLC that had been dissolved two years earlier. The buyer walked away after realizing they would need to spend $18,000 annually on new license fees on top of the purchase price. Practice management software like CaseWare, Canopy, or Thomson Reuters ONESOURCE works differently. These platforms often allow transferable implementations, but there is usually a setup fee and a learning curve. Factor in approximately $5,000 to $15,000 for transition costs when valuing the practice. Clean, well-organized digital files that transfer seamlessly add value. Disorganized client folders, missing engagement letters, and scattered spreadsheets subtract value because the buyer is inheriting a cleanup project.
Staff dependency and key person risk
If your practice cannot function without you personally preparing returns or maintaining key client relationships, the valuation drops significantly. Buyers are wary of practices where the owner is the primary relationship holder and the only person who understands the client base. This is sometimes called key person risk, and it is one of the most common reasons valuations get cut during due diligence. A practice where a lead preparer handles 80% of the returns and maintains the top 20 client relationships is a single point of failure. If that person leaves after the sale, the buyer's revenue could collapse. The workaround is straightforward but requires work before you list: document every process, build a second pair of hands who can step in, and gradually transfer client relationships to junior staff over six to twelve months. I spent about eight months doing this before listing my own practice. It was annoying and slowed my income during that period, but it increased the final offer by roughly 22% because the buyer had confidence the practice would run without me.
What the local market and economic cycle do to your number
Tax practice valuations move with interest rates and broader economic conditions. When financing is cheap and buyers have access to favorable SBA loans, multiples expand. When rates climb and borrowing becomes expensive, multiples compress because the buyer's cost of capital increases. The current environment as of 2025 has seen multiples tighten by about 0.3x to 0.5x compared to the low-rate years of 2020 through 2022. Geographic market saturation also plays a role. A tax practice in a growing suburban market with expanding small business population will command a higher multiple than one in a declining rural area where the client base is aging and shrinking. Buyers evaluate the tailwind or headwind of the local economy just as carefully as they evaluate your numbers.
Common mistakes that tank valuations
Most sellers mess up the financials by overstating expenses or failing to properly add back legitimate adjustments. An add-back is an expense that is not expected to recur under new ownership. Examples include a one-time legal settlement, a personal vehicle expense running through the business, or a home office deduction claimed on Schedule C that the buyer will not continue. Every add-back needs documentation. If you claim a $15,000 add-back for a consultants fee but cannot produce the invoice and proof of payment, the buyer will simply disallow it and reduce the SDE accordingly. I have seen a $40,000 discrepancy from sloppy add-back documentation in a $700,000 practice. That single error cost the seller about $80,000 in reduced offer price. Another frequent mistake is trying to sell before the books are organized. A buyer needs at least three years of tax returns, profit and loss statements, and a detailed client list with revenue per client. If you are scrambling to pull this together after listing the practice, you will look disorganized and raise red flags. Prepare these documents before you think about listing. The biggest pitfall is pricing based on emotional attachment rather than market comparables. You might believe your practice is worth more because you built it from nothing or because you love your clients. The market does not care about any of that. Buyers look at comparable sales, revenue quality, growth trajectory, and risk profile. If your neighbors are selling similar practices for 2.8x SDE and you are asking for 4x, you will sit on the market for months or accept a lower offer after multiple rounds of negotiation.
When a simple multiple approach completely fails
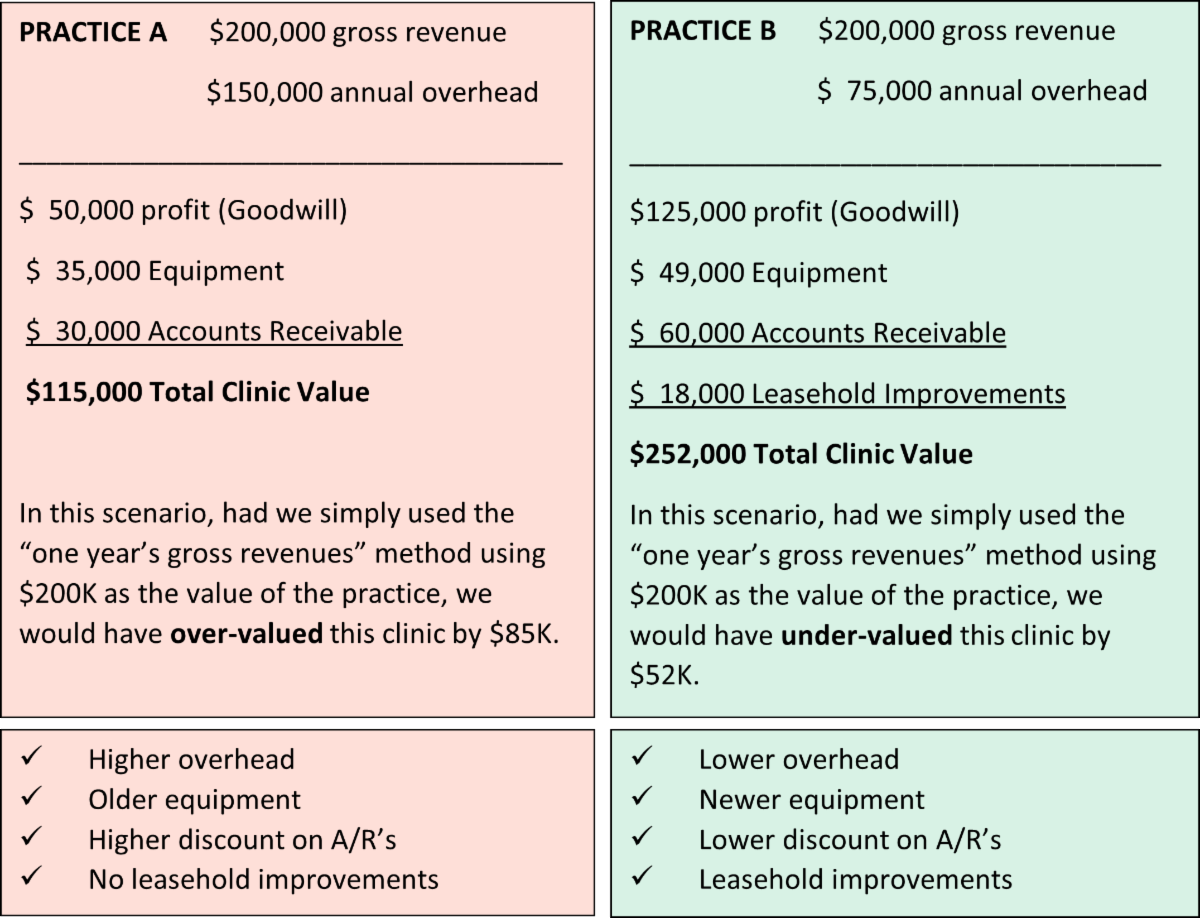
There are scenarios where the standard SDE multiple method produces a wildly inaccurate number. If your practice has recently lost its largest client, the trailing SDE will look artificially high. Using a multiple on that inflated number would overvalue the practice. In this case, you should use forward-looking projected earnings with a discount for the elevated risk. Conversely, if you have just invested heavily in new software, hired a key employee, or signed a large new client that will generate revenue for years, the trailing SDE understates the true earning power. Here you might justify a higher multiple based on near-term growth prospects. Both adjustments require solid documentation and a willingness to show your work to the buyer. For practices with significant non-recurring revenue, such as a large one-time M&A advisory engagement, the cleanest approach is to subtract that revenue entirely from the SDE calculation and value only the recurring component. This prevents the buyer from expecting that revenue to repeat and then being disappointed when it does not.
Getting an accurate number for your specific situation
The most reliable way to determine what your practice is worth is to obtain a formal business appraisal from a certified valuation analyst who specializes in professional service practices. These appraisers typically charge between $5,000 and $12,000, but the report they produce can prevent you from leaving money on the table or pricing yourself out of the market. Look for someone with a CVA or ABV credential and experience with accounting and tax practices specifically, not general business appraisers who apply generic formulas. You can also run your own numbers using the SDE multiple method and then cross-check against publicly available practice sale listings on sites like PracticeXchange, Questrom Exchange, or the O’Neil Group marketplace. Recent sale prices for comparable practices in your region give you a reality check against whatever number your calculations produce. The bottom line is that determining how much your tax practice is worth requires looking past the gross revenue number and examining the quality, stability, and transferability of that income. The practices that command the highest multiples are the ones where revenue is recurring, client relationships are distributed across multiple staff members, software and processes are documented and transferable, and the financials are clean enough for a buyer to underwrite without guessing. Spend time strengthening those areas before you list, and you will likely walk away with significantly more than the first offer you receive.