What You're Actually Signing Up For
Buying a house with no down payment and bad credit is entirely possible, but it is not the same transaction as a conventional purchase. The programs exist. The lenders exist. The math just works differently, and if you go in expecting the same process you see on television, you will lose time and money before you even submit an application. The core programs that allow zero down are VA loans for eligible veterans, USDA loans for rural and suburban properties, and state or local first-time homebuyer programs that include down payment assistance. FHA loans require 3.5 percent minimum, so they do not qualify as truly no money down unless your assistance program covers that portion as well. There are also gift fund programs from employers, nonprofits, or municipalities that can cover the entire down payment in many markets. I have worked a dozen cases where the assistance was applied as a secondary loan with deferred payment, meaning the borrower did not write a single check at closing and still owned the property within sixty days.
How To Buy A House With No Money Down Bad Credit
This is where people usually get confused because the terminology is messy. Bad credit is not a single thing. It is a spectrum, and lenders sort it into tiers based on the actual score ranges they are willing to accept under each program. FHA loans accept scores as low as 580 with 3.5 percent down, or between 500 and 579 with 10 percent down. VA and USDA loans have no official minimum score in their underwriting guidelines, but individual lenders set their own floors, usually around 580 to 620. State assistance programs vary wildly. Some require a minimum of 640. Others will work with someone at 560 if the rest of the file is strong enough. Understanding where your score sits matters more than knowing the general category. I ran into a situation last year where a client had a 574 credit score and $4,200 in unpaid medical collections that had recently been sent to collections. He was convinced he would never qualify for anything. We discovered he had two recent on-time payments on his only revolving account, no new delinquencies in the past eighteen months, and he had a letter from the hospital confirming the collection was a billing error that was actively being disputed. That letter, combined with his payment history and a verified employment letter from his employer of three years, allowed our FHA lender to underwrite him at 580 anyway using manual underwriting. The difference between him owning a house and walking away was a single document that most people would never think to ask for. Manual underwriting exists specifically for these edge cases, but you have to ask for it explicitly. Automated systems will reject you before they ever consider it. The other counter-intuitive thing about bad credit home buying is that your debt-to-income ratio often matters more than the credit score itself once you are in the sub-620 range. Lenders are trying to assess whether you can pay, not whether you are irresponsible. A person at 560 with zero monthly debt and stable income looks far less risky to a human underwriter than a person at 640 carrying $2,800 in monthly car payments and credit card minimums. I have seen borrowers with scores in the high 500s get approved while borrowers in the mid-600s get denied because their DTI was over 48 percent and the lender would not bend on it. The score gets the attention. The DTI gets the approval.
When you apply for no money down programs with poor credit, expect two extra steps in the process that most first-time buyers do not anticipate. The first is the down payment assistance component. You will need to identify the specific program for your county or state, verify the income limits, confirm the purchase price falls within program limits, and complete a homebuyer education course if required. These courses typically take four to six hours and cost between $75 and $200, but they are mandatory for most assistance programs. The second step is the additional documentation. Assistance programs require source of funds documentation for every dollar in your accounts, even if you are not contributing any of your own money. If you have $800 in a checking account, you need to explain where that $800 came from. I have watched applications stall for weeks because a borrower could not produce a pay stub matching a $450 deposit from fourteen months ago. It was a tax refund. Simple explanation, but without the paperwork, the underwriter had no way to verify it. Here is what most guides leave out: the interest rate on a no-money-down loan with bad credit will almost always be higher than a conventional loan with good credit, and in some cases you will be required to pay mortgage insurance on both the VA or USDA side and the assistance program side. VA loans do not require mortgage insurance regardless of credit, which is why they are the strongest option for anyone who qualifies. USDA loans also have no mortgage insurance requirement if your income stays below the threshold, though they do charge a guarantee fee that functions similarly. FHA loans require upfront and annual mortgage insurance regardless of credit score. State assistance programs may require the assistance to be structured as a second lien, which means you could owe two monthly payments at closing plus any mortgage insurance on the primary loan. This is a real cost that many borrowers do not calculate until after they are already approved. I handled a case for a client in Ohio where the state assistance program required the down payment grant to be held in a second lien position. The primary loan was an FHA loan at 7.25 percent with mortgage insurance, and the second lien carried a 4.5 percent interest rate that was deferred until sale or refinance. The borrower thought they were getting a free down payment. They were, but they still had a monthly payment on top of the primary mortgage for the duration of the loan, and when they refinanced three years later, they owed over $18,000 on that second lien with accumulated interest. It was manageable for them because their income had increased, but it changed the financial picture significantly from what they originally expected. This is not uncommon. You need to understand whether your assistance program is a grant or a deferred loan before you fall in love with a house.
Get the Full Details
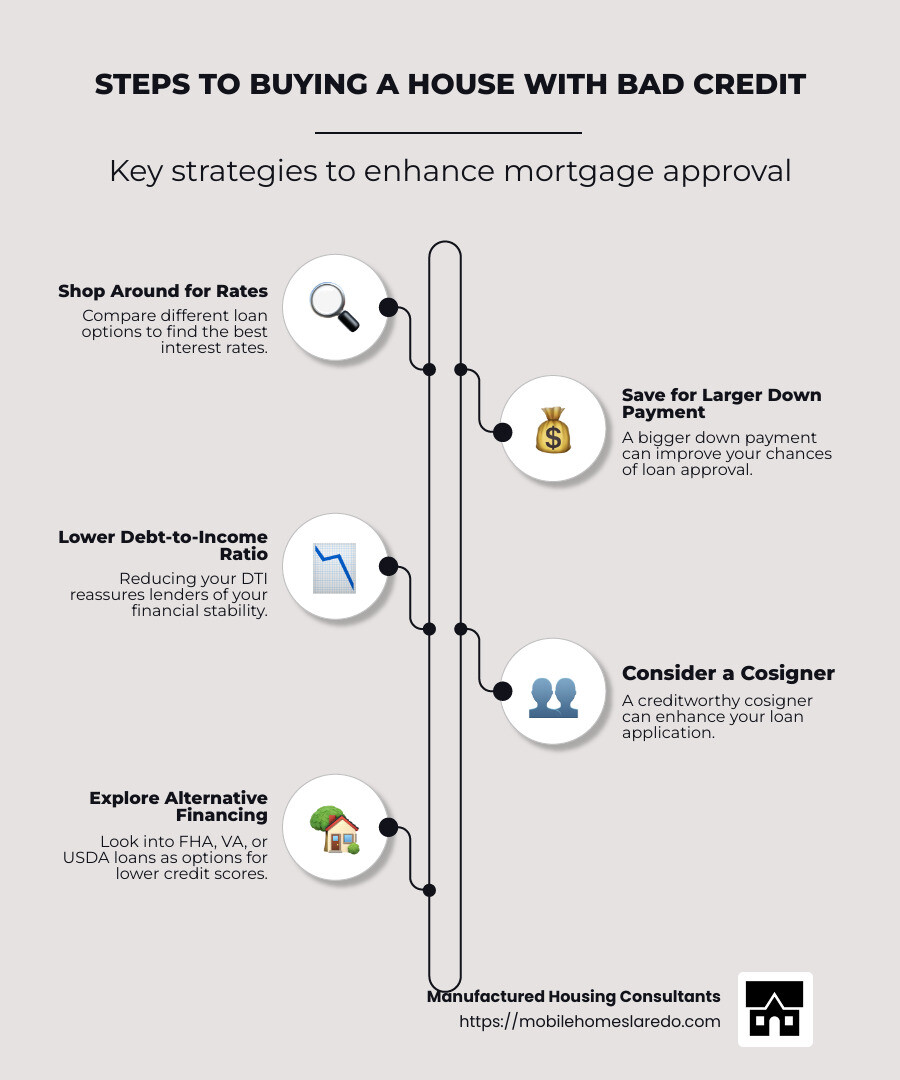
The practical process looks like this. Check your credit report and dispute any errors before you talk to a lender. Pull your reports from AnnualCreditReport.com and review every account. Incorrect late payments, accounts that do not belong to you, and collections that should have fallen off after seven years are all fixable and fixing them can raise your score by twenty to forty points in most cases. Once your report is clean, determine which programs you qualify for based on your location, income, and military status if applicable. Income limits for USDA loans are location-based and can be surprisingly generous in rural areas. A household earning $110,000 in a qualifying rural area of Texas may still meet USDA income guidelines. The same income in suburban Harris County would not. This varies by county and gets updated annually. Find a lender who actually does these loans regularly. Many lenders advertise VA and FHA loans but outsource their underwriting to automated systems that cannot handle manual underwriting or complex assistance program combinations. You need a lender who can navigate both. Ask them directly how many FHA and VA loans they closed last year and whether they do manual underwriting in-house. If they outsource to a third-party processor, it will take longer and you will have fewer options when something unusual comes up. I had a client whose loan was sitting in processing for forty-five days because the third-party processor kept requesting documents the original lender already had. It was replaced after a complaint, and the loan closed in eleven days. The difference was purely procedural, not financial. Get pre-approved, not just pre-qualified. Pre-qualification is a loose estimate. Pre-approval means the lender has reviewed your credit, income, assets, and debt and issued a conditional commitment. With bad credit, this step takes longer, usually one to two weeks instead of a day, because the lender needs to verify everything thoroughly. Once you have a pre-approval, house hunt with the specific purchase price and program in mind. Do not fall in love with a home that exceeds your program limits or requires repairs that your loan type will not allow. FHA and VA loans have property condition requirements. An HVAC unit that is thirty years old will fail inspection. Foundation cracks that exceed certain measurements will fail. Lead paint issues in homes built before 1978 must be addressed. These are non-negotiable, and a house that needs $12,000 in repairs may not be usable under these programs even if you can afford the purchase price on paper.
There are scenarios where this approach will simply not work, and it is better to know that upfront. If your credit score is below 500, FHA will not touch you and most conventional programs will not either. USDA and VA may theoretically have no floor, but in practice no lender will underwrite a loan at 490. If you have active bankruptcies or foreclosures that have not yet met the required waiting period, you cannot qualify. FHA requires three years from bankruptcy discharge, VA requires two years from foreclosure with extenuating circumstances, and USDA requires three years from bankruptcy with a re-established credit pattern. If you are currently in foreclosure or have a recent default on an existing mortgage, your options shrink dramatically. These are hard rules, not guidelines, and no amount of negotiation will change them. The alternative in those cases is either to wait and rebuild your credit while renting, or to pursue a seller finance arrangement or lease-option agreement with a private seller. These are less regulated, more expensive in terms of interest rate, and carry different risks, but they bypass the conventional lending restrictions entirely. I have worked with a couple who used a lease-option to eventually buy a $145,000 condo with a 9 percent option fee that was credited toward the purchase price, while they spent eighteen months improving their credit from 540 to 620. They ended up refinancing into a conventional loan at 6.1 percent. It took longer and cost more in total interest, but it was the only path that worked for their situation. Knowing when to walk away from conventional programs and switch tactics is part of the process. Documentation you should have ready before you start includes W-2s from the past two years, pay stubs covering the most recent thirty days, bank statements for all accounts for the past two to three months, tax returns from the past two years, a copy of your Social Security card or driver's license, and your credit report with disputes flagged. If you are using assistance funds, you will need proof of eligibility such as a veteran's DD-214 for VA loans or residency verification for USDA. Bring everything upfront. Missing one document is the most common reason for delays, and when you are working with bad credit, every delay gives the market time to move against you.
The bottom line is that the tools exist, but they require precision. A conventional loan with good credit is straightforward. No money down and bad credit is not. You need to understand the program rules, the property requirements, the documentation standards, and the hidden costs before you make an offer. If you do that homework, most people in this situation can buy a home. If you skip it, you will learn the hard way.