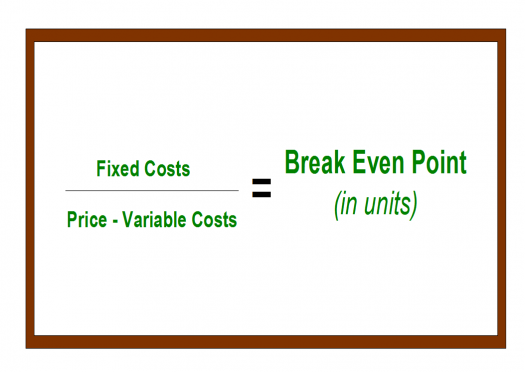
The Raw Formula
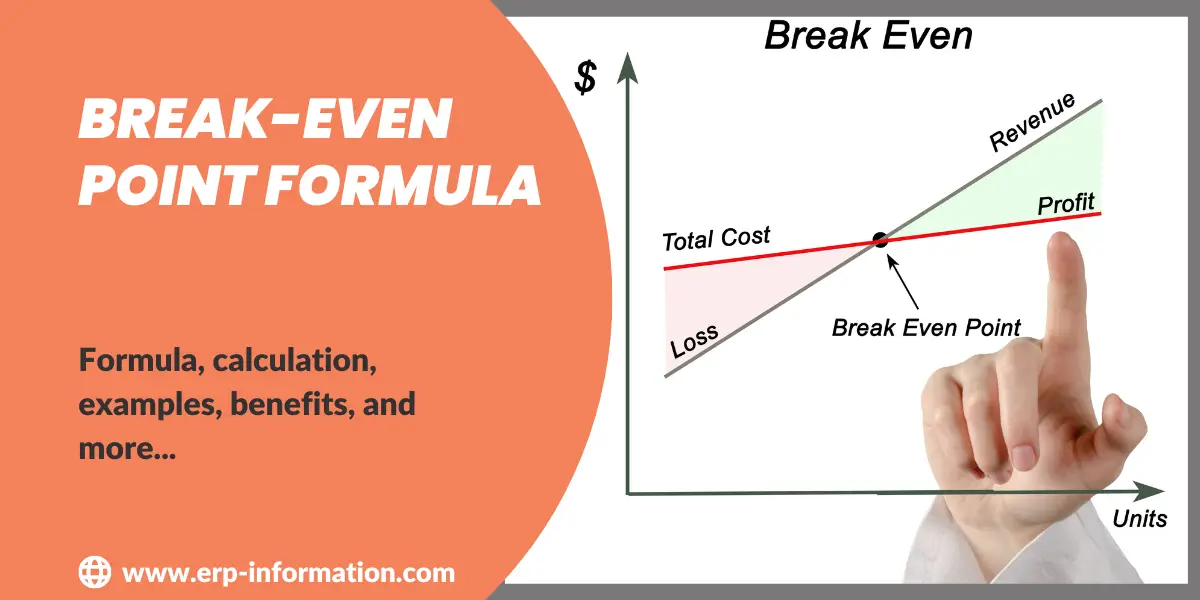
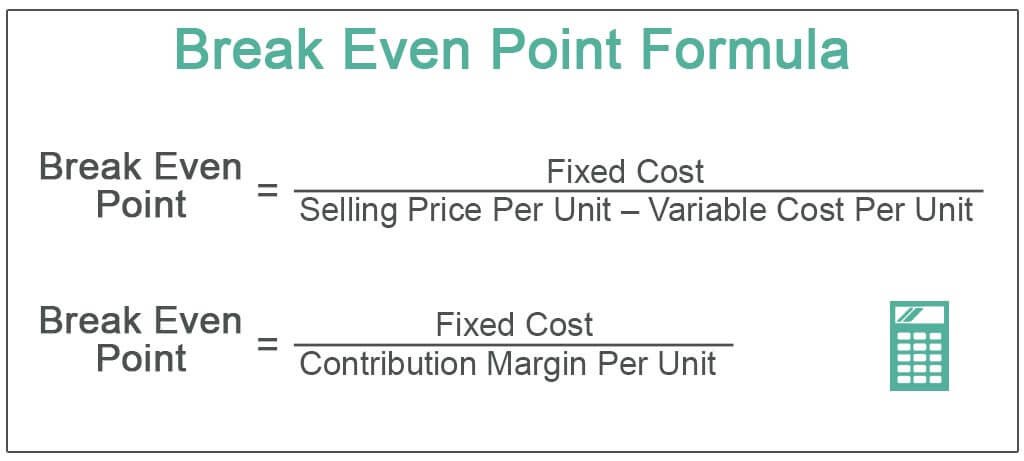
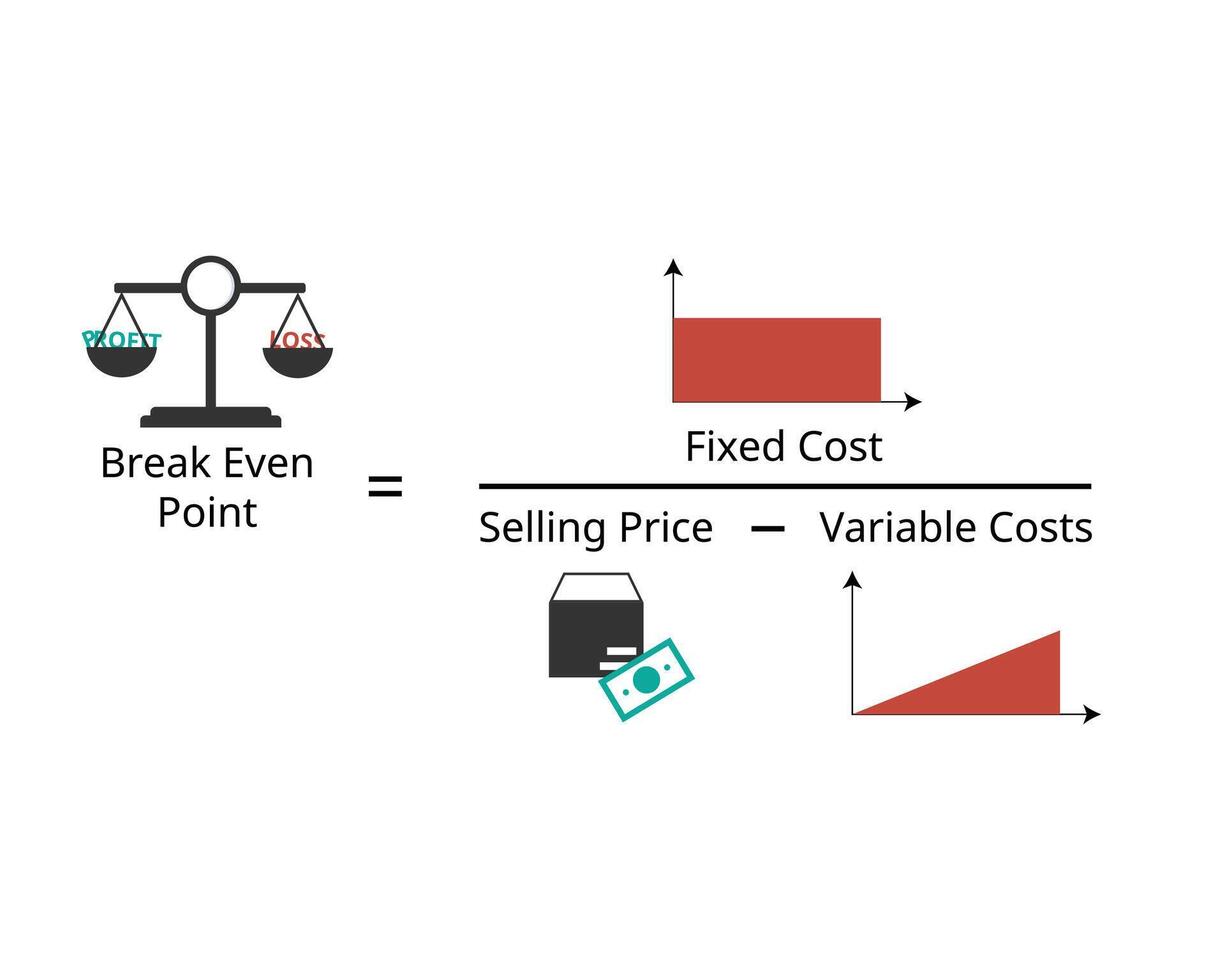
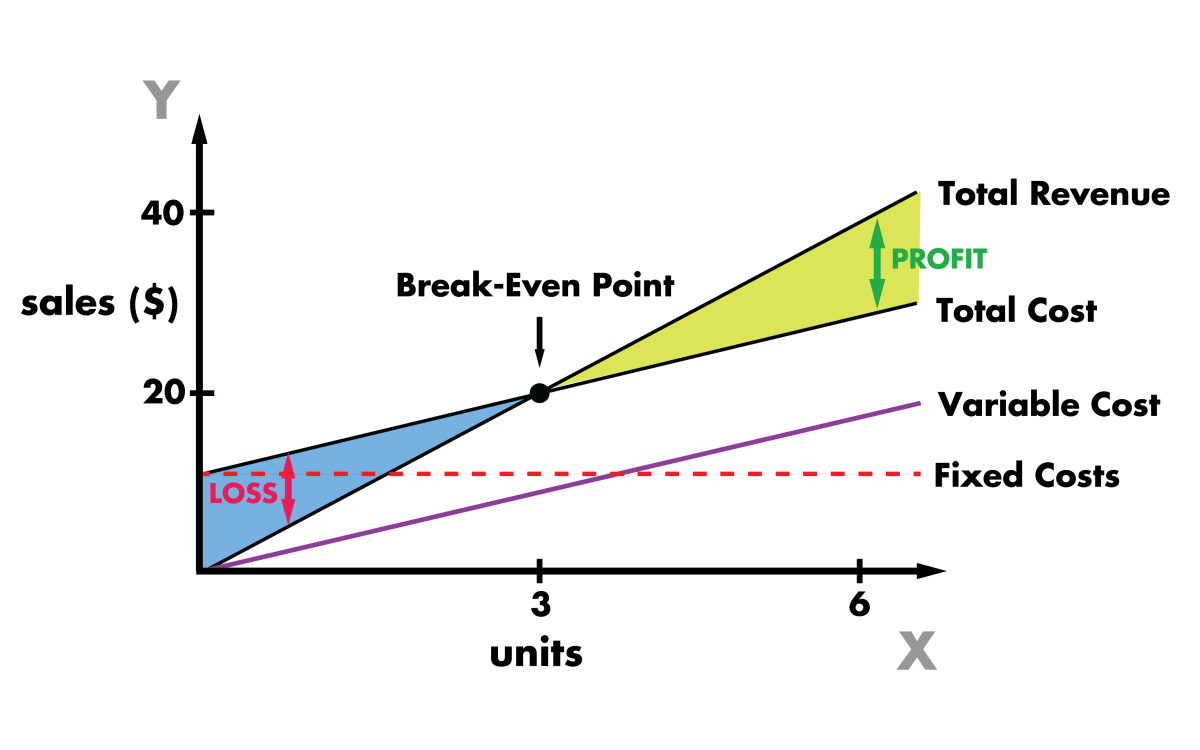
Break even point is straightforward when you strip away the business school gloss. It is the point where total revenue equals total costs. Below that number, you lose money. Above it, you make money. The basic formula divides your fixed costs by your contribution margin per unit. Contribution margin is simply your selling price minus your variable cost per unit. Fixed costs stay the same whether you sell one item or a thousand. Variable costs change directly with each unit sold. This is not complicated math. It is just accounting done honestly. Take your fixed costs and divide by the difference between your price and your variable cost. That gives you the unit count you need to hit zero loss. If you want the dollar value instead of units, multiply that result by your selling price. Or divide fixed costs by the contribution margin ratio, which is the contribution margin divided by price. Both methods land on the same number. The first approach is usually easier to work with mentally. I learned this the hard way running a small custom furniture shop back in 2018. I had fixed costs around four thousand dollars a month covering rent, insurance, and the lease on my table saw. Each table sold for eight hundred dollars and the variable cost came to about three hundred in lumber, finish, and labor per piece. The math said I needed to sell roughly ten tables a month to break even. Ten tables. Not eight. Not twelve. Ten. I was selling six at the time and bleeding two thousand dollars monthly.
Here is the edge case nobody warns you about. My variable cost per table was not actually constant. At higher volumes, I could negotiate better lumber prices, which dropped my per-unit cost to about two sixty. That shifted the break even from ten tables down to eight and a half. Rounding up, nine. The standard formula assumed a flat variable cost that did not exist in practice. I corrected this by using a tiered model rather than a single static number. I broke the formula into ranges tied to volume brackets. This took more setup but it reflected reality. Common mistake number one: people forget to separate mixed costs properly. A utility bill is never purely fixed or purely variable. It has both. If you lump it into one bucket, your numbers drift. I used the high-low method to split them out. Take your highest activity month and lowest activity month, subtract the costs, divide by the difference in units produced, and you get your variable rate. Subtract that from either month total to isolate the fixed portion. It is rough but it works fast. Common mistake number two: treating break even as a single event rather than a range. Your costs shift. Your prices shift. The market shifts. A break even analysis based on last quarter's numbers may already be wrong by the time you finish calculating it. I rebuild mine every thirty days during lean months. It takes about twenty minutes with a clean spreadsheet. During stable months, I do a quarterly review that takes maybe an hour.
Another nuance beginners miss is the impact of product mix when you sell multiple items. A single break even point does not exist if you have five different products with different margins. You need a weighted average contribution margin based on your expected sales mix. If product A makes up sixty percent of sales and product B forty percent, you blend their margins accordingly. Get the mix wrong and your break even number becomes fiction. I have seen founders celebrate breaking even on paper while their actual mix made the target unreachable. The method has real limitations. Break even analysis assumes you can sell everything you produce, which is rarely true. It also assumes costs behave linearly, which they almost never do. Step costs, bulk discounts, seasonal variations, and capacity constraints all distort the picture. When your fixed costs include salary tiers that jump at certain headcounts, a simple formula becomes meaningless. In those cases, I build a monthly cash flow model instead. It takes longer but it captures the messiness. A spreadsheet with monthly rows for revenue, variable costs, fixed costs, and the resulting cash position will show you where you actually break even across a timeline rather than a single abstract point. If you are working with a service business, variable costs are often much lower than you expect, which inflates your contribution margin and makes the break even look achievable too quickly. That feeling is deceptive. Lower margins on individual jobs plus higher customer acquisition costs mean the real number is worse. Factor in the time to close a sale. Factor in unpaid invoices. The breakeven shifts further out than the formula suggests.
Get the Full Details
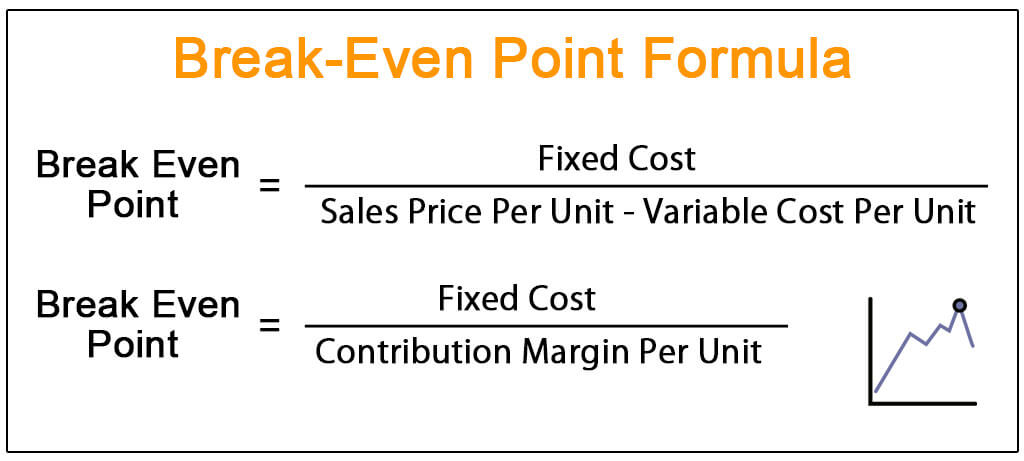
The bottom line is that break even calculation is a starting point, not a finish line. Get the basic formula right. Then stress test it against your actual cost structure. Then rebuild it when conditions change. The people who survive are the ones who treat the number as a living estimate rather than a permanent answer.