HELOC Payment Math Without the Marketing Fluff
Most people think calculating a HELOC is just plugging numbers into a simple interest formula. It's actually more complicated than that because there are two completely different payment phases, a variable rate that shifts quarterly, and a credit limit that doesn't tell the whole story. I've been sitting through lender presentations where the rep shows you the draw period payment and nobody asks about the 10-year repayment number until it's too late. Here's how to actually do the math yourself so you're not surprised.How To Calculate Heloc Loan
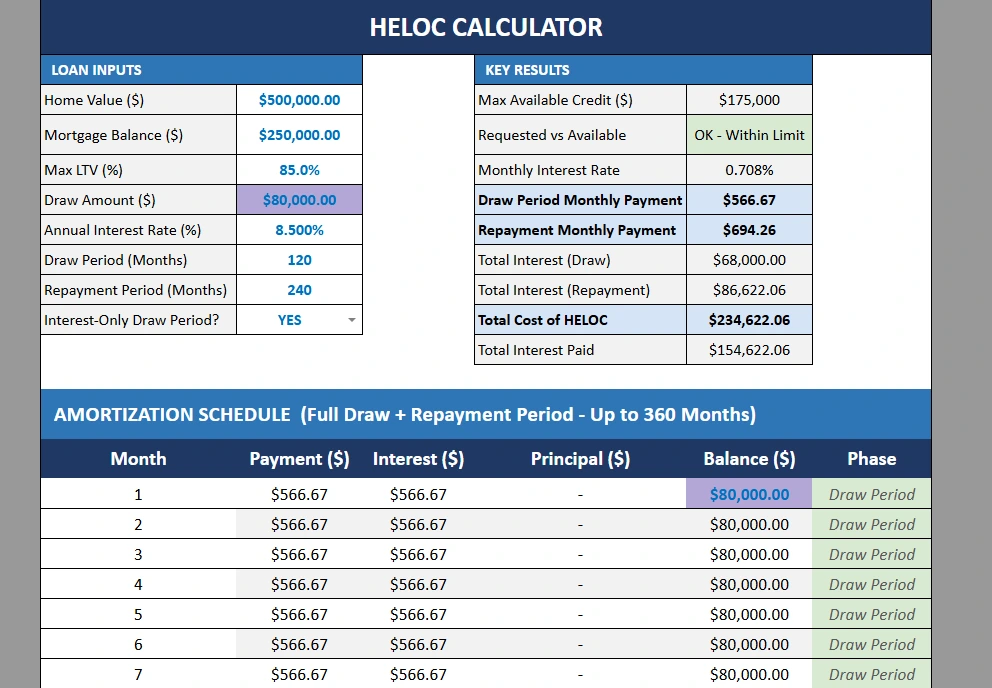
Start with what lenders call the combined loan-to-value ratio, or CLTV. This is the single number that determines whether you get approved and at what rate tier. You take your current mortgage balance, add the new HELOC amount you're requesting, and divide by the appraised value of your home. Most lenders cap this at 85 percent, though some go to 90 or even 95 in competitive markets. If you're at 80 percent CLTV you'll get a significantly better rate than someone at 84 percent, so this matters more than people realize. Once you know your credit limit, you need to separate the two phases. The draw period typically runs 5 to 10 years. During this window you're only required to make interest-only payments on whatever balance you've actually drawn. The formula here is straightforward: multiply your outstanding balance by your annual interest rate, then divide by 12 to get the monthly amount. So if you've drawn $40,000 at a 7.5 percent rate, your monthly payment during the draw period is $40,000 times 0.075 divided by 12, which equals $250. That's it. The full credit limit doesn't matter for the payment calculation—only the amount you've actually borrowed. The repayment period is where people get caught. Once the draw period ends, usually after 10 years, the remaining balance gets amortized over the repayment term, which is typically another 10 to 20 years. Now you're paying principal and interest together using a standard amortization formula. The monthly payment becomes P times r times (1 plus r) raised to the power of n, all divided by (1 plus r) raised to the power of n minus 1. Here P is your remaining balance, r is your monthly interest rate, and n is the total number of repayment months. A $40,000 balance at 8 percent over 20 years (240 months) comes out to roughly $341 per month. Compare that to the $250 interest-only payment you were making during the draw period, and the jump is real.
There's a common misconception that you can treat the HELOC rate as fixed for the life of the loan. It isn't. HELOCs use a margin above a benchmark index, usually the prime rate. If your loan is priced at prime plus 2.5 percent and prime is currently 8.5 percent, your rate is 11 percent. When the Fed moves rates, your payment moves with it, and most lenders reset the index quarterly. I worked with a client a few years back who had a HELOC at prime plus 2. There was a brief window when prime dropped to 3.25 percent, so his rate went to 5.25 percent and his payment was manageable. Then the Fed started hiking and prime climbed to 8.5 percent within 18 months. His rate jumped to 10.5 percent and his minimum payment nearly doubled. He'd budgeted around the original rate and wasn't prepared for the escalation. The fix was simple in hindsight—switch to a home equity loan with a fixed rate for the bulk of the balance—but he should have done it during the low-rate window instead of waiting. Another thing nobody warns you about is the draw period conversion trap. Some lenders structure their HELOCs as closed-end loans after the draw period, meaning they convert the remaining balance into a fully amortizing loan at the current rate. Other lenders keep it as an open HELOC where you can still draw during the repayment phase, but you're paying on a much larger balance. The paperwork is almost identical, so you need to read the actual terms. I had a borrower last year who thought she was converting to a standard home equity loan at her original rate. She wasn't. The lender rolled her into a new amortization schedule at the prevailing rate, which was 4 percent higher than what she expected. That added roughly $280 a month to her payment on a $60,000 balance. For calculating the maximum amount you can realistically borrow, don't just look at the LTV limit. Factor in your existing debt-to-income ratio. The lender will run a DTI calculation on your gross monthly income that includes the proposed HELOC payment alongside your mortgage, car loans, credit cards, and any other obligations. If your front-end ratio is already near 28 percent and your back-end ratio is over 43 percent, adding a HELOC payment could push you into decline territory regardless of how much equity you have. A practical rule of thumb: if your total housing payment plus the HELOC payment exceeds 36 percent of gross monthly income, you're likely maxing out what the lender will comfortably approve.
When you're actually crunching these numbers, a spreadsheet is the fastest tool. Set up columns for the draw period with a variable payment column that recalculates whenever the rate changes, and a second section for the repayment period with the amortization formula. Use a data table to show what your payment looks like at five different rate scenarios—say 6, 7, 8, 9, and 10 percent—so you can see the range. This takes maybe 20 minutes and saves you from getting blindsided. One nuance that trips people up: the refresh provision. Some HELOCs let you rebuild your available credit as you pay down the balance during the draw period, meaning you can borrow, repay, and borrow again without reopening the loan. Others lock your credit limit for the entire term. If you're planning to use the HELOC for multiple renovation projects spread over several years, the refresh provision matters a lot. Without it, you'd be closing and reopening a line of credit, which triggers new closing costs and underwriting each time. The biggest limitation of HELOC math is that it assumes you'll always have the option to refinance or pay off the balance when rates spike. If your credit profile deteriorates or home values drop during a downturn, you might be stuck with a variable-rate debt that's eating into your cash flow with no easy exit. That's why I always recommend running a worst-case scenario where rates go up 300 basis points from your current level and seeing whether your payment is still sustainable on your current income. If it isn't, you're borrowing more than you can safely carry.
Get the Full Details