The actual math behind a HELOC, the way lenders work it out
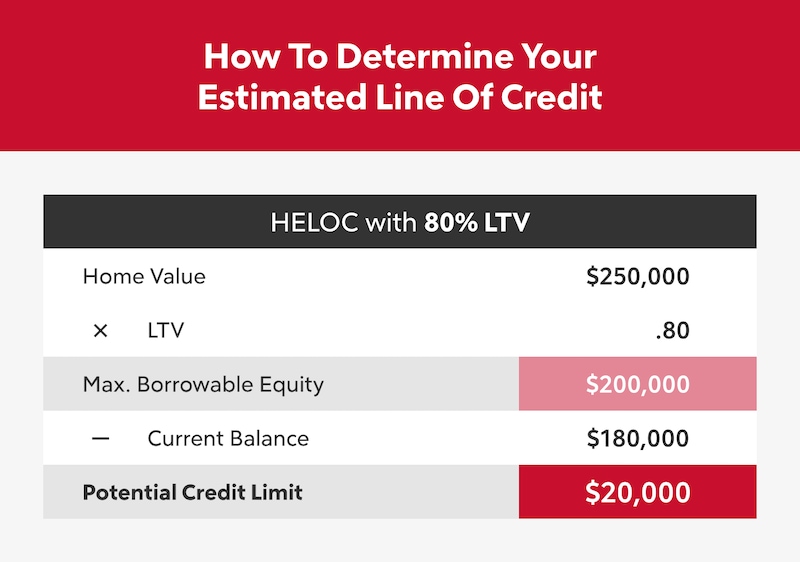
A HELOC isn't calculated the way a personal loan is. There's no simple fixed formula where you plug in numbers and get a clean answer. The calculation is really just two steps mashed together, and most people miss the second part entirely until it bites them. First, you figure out your available credit. Take your home's current appraised value, multiply it by the lender's maximum combined loan-to-value ratio, and subtract everything you already owe on the first mortgage. That remainder is your credit ceiling. Lenders typically cap CLTV at 80 to 90 percent, and the exact number depends on who you're talking to and what your credit profile looks like. Here's a real example. You own a house valued at $420,000. Your existing mortgage balance sits at $280,000. Your lender allows a max CLTV of 85 percent. That means $420,000 times 0.85 equals $357,000 in total allowable debt. Subtract your $280,000 mortgage and you're looking at roughly $77,000 in available HELOC credit. If the same lender only offers 80 percent CLTV, that number drops to $56,000. The difference matters more than people realize.
That's the easy part. The harder part is figuring out what your payments will actually look like during the draw period and then again during repayment, because the math changes completely between the two phases. Most people don't account for that shift. During the draw period, which usually runs anywhere from five to ten years, you're typically only paying interest on whatever you've actually drawn. If you pull out the full $77,000 and the rate is 8.5 percent, your monthly payment is about $546. If you only draw $30,000, it's roughly $213. The rate is variable, so that payment can drift upward every time the index moves. I've seen people budget for their initial payment and then get caught flat-footed when rates jumped a full percentage point two years in and their payment silently increased by nearly $30 a month on a $70,000 balance. Then the repayment period kicks in, and suddenly you're paying both principal and interest on the outstanding balance with no more draws allowed. If you still have $60,000 left on a ten-year repayment schedule at 8.5 percent, that payment jumps to around $730 a month. It's a dramatic shift that catches a lot of people off guard because the initial draw-period payment makes the debt feel manageable.
I ran into a specific edge case recently that illustrates why the standard calculator doesn't always work. A borrower had a first mortgage at $310,000 and wanted to open a HELOC. Her home was appraised at $450,000, which looked fine on paper. But she also had a second lien — a home equity loan from six years ago for $25,000 that she'd forgotten to factor into her mental math. The lender's calculation included it, which dropped her available credit from about $77,000 down to $52,000. She'd been planning renovations around that higher number. The workaround was straightforward once I identified it: pull a full lien search before running any numbers, not just your monthly statement balance. Most people skip that step and it costs them later. Another thing that isn't obvious: some lenders use a purchase-price-based valuation rather than a current appraisal for their initial CLTV calculation. If you bought your home two years ago for $380,000 and it's now worth $420,000, a lender using the original purchase price would calculate your equity differently than one using the current appraisal. This can create a $15,000 to $25,000 discrepancy in your available credit depending on who you apply with. It's not rare, and it's not always disclosed upfront. The qualification side adds another layer. Lenders look at your debt-to-income ratio, and they include your minimum HELOC payment in that calculation even if you haven't drawn anything yet. Most use either 5 percent of the total credit limit or the hypothetical payment on the full amount, whichever is higher. A $100,000 line at 8 percent would generate a $583 monthly payment estimate that gets folded into your DTI before you've borrowed a single dollar. That can be the difference between approval and denial if you're already near the threshold.
Get the Full Details

There are also closing costs and annual fees that eat into the real value of the line. Some lenders charge origination fees between 1 and 2 percent of the credit limit, plus appraisal and title costs. On a $75,000 line, that's roughly $750 to $1,500 in upfront fees. If you're only going to use a fraction of the line for a short project, those costs make the effective interest rate much higher than the advertised rate. A HELOC only makes financial sense if you're drawing and repaying a meaningful portion over a meaningful timeframe, otherwise you're paying premium costs for premium access. The worst-case scenario is when property values decline after you've opened the line. Lenders can and do conduct periodic reviews, and if your home loses value and your CLTV breaches their threshold, they can freeze the line or reduce it. I've seen this happen during regional market corrections where homes dropped 10 to 15 percent in value. Borrowers who were counting on that credit for a later phase of a project found it unavailable when they needed it most. There's no guarantee the line stays open, and that's a risk most calculators won't show you. If you want a concrete way to run the numbers yourself, there are free calculators from major banks like Chase, Bank of America, and NerdWallet. They're accurate enough for estimates, but remember they're built for marketing, not for stress-testing your budget. Run the numbers through multiple periods, not just the first month, and factor in a rate increase of 1 to 2 percent to see how your payments would behave under pressure. That's the exercise most people skip and regret later.