The Basics of Interest-Only Payments
An interest-only loan means you pay just the interest on the principal balance for a set period. The principal stays untouched until that period ends. This makes the monthly payment significantly lower than a standard amortizing loan, which is why people tend to look into them. The calculation itself is straightforward arithmetic. You take the outstanding loan balance, multiply it by the annual interest rate, and divide by twelve to get the monthly amount. That is it. There is no complex amortization schedule to track during the interest-only phase. The numbers do not change unless your rate adjusts or your balance changes.
How To Calculate Interest Only Loan Payments
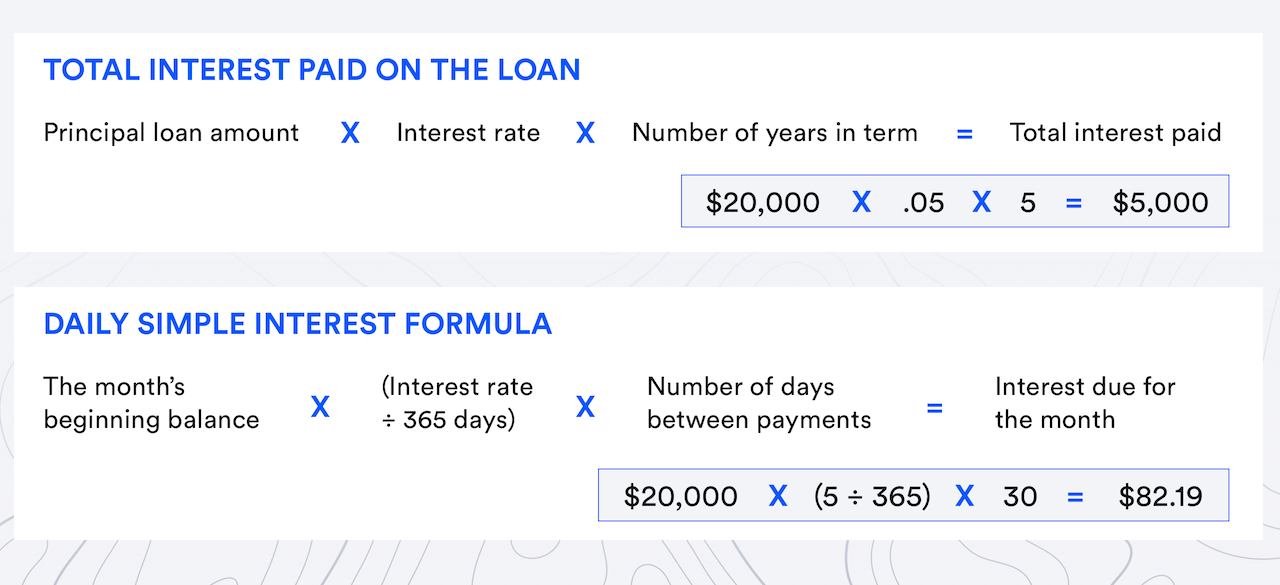
Here is the practical formula I use when someone asks me this question at 11pm on a Tuesday: monthly payment equals the principal balance multiplied by the annual interest rate divided by 12. Write it out on paper if you want to be safe. A lot of people skip that step and then wonder why their first payment is off by forty dollars. For example, say you have a $250,000 loan at 6.5% annual rate. Divide 6.5 by 100 to get 0.065. Multiply $250,000 by 0.065 and you get $16,250 in annual interest. Divide that by 12 and your monthly payment is $1,354.17. No principal component. Just interest. The balance remains $250,000 at the end of the month.
Where People Go Wrong
The most common mistake I see is mixing up the annual rate with the monthly rate before doing the multiplication. People divide the rate by 12 first, then multiply by the balance. Mathematically this gives the same result, but the order matters when your calculator is already open and you are juggling multiple loans. I keep everything in one sequence to avoid that drift. Another issue is annual percentage rate versus the note rate. Some lenders quote an APR that includes fees baked into the interest calculation. If you use the APR instead of the note rate, your payment will be higher than the base interest-only figure. Always confirm which rate the lender is using before you crunch the numbers. I learned this the hard way when a client's lender quoted 5.8% APR on a loan that actually carried a 5.5% note rate. The difference came out to about $58 a month, which sounds small until you are looking at a five-year stretch.
Get the Full Details

Adjustable-Rate Interest-Only Loans
Not all interest-only loans stay at one rate. Adjustable-rate mortgages or ARMs will reset periodically, usually after an initial fixed period. When the rate adjusts, your payment changes. The new payment is recalculated using the current balance and the new rate. The principal balance does not change just because the rate changed, which is worth remembering. I once worked with a borrower who had a 5/1 ARM with a ten-year interest-only period. At the five-year mark the rate jumped from 4.25% to 6.75%. Their payment went from roughly $1,052 to $1,875 on a $300,000 loan. They had budgeted for the original amount and were caught off guard. The lesson here is simple: calculate the worst-case payment using the cap rate, not the initial teaser rate, and make sure you can absorb that number before signing anything.
Practical Edge Case: Balloon Payments at Maturity
Interest-only loans often come with a balloon payment at the end of the interest-only period. The entire principal becomes due, or you refinance into a fully amortizing loan. This is not unusual. It is the default structure for a lot of commercial and investment property loans. I had a client who took a $400,000 interest-only loan at 7% for seven years. Their monthly payment was $2,333.33. At the end of year seven they needed to either sell the property or refinance. The market had shifted and refinancing was tight. They ended up paying off the $400,000 principal plus any accrued interest from a separate savings account they had been building alongside the loan. The workaround here is not fancy: start a dedicated savings plan from day one. Even setting aside $500 a month in a high-yield account gives you $42,000 over seven years, which softens the blow when the balloon hits.
What This Method Does Not Cover
Interest-only calculations do not include escrow items like property taxes or insurance. Those are usually rolled into your monthly payment by the lender but are separate from the interest calculation. If you are budgeting for the total monthly outlay, add those escrow amounts on top of the interest payment. On a $300,000 loan in a high-tax county, escrow alone can add $400 to $800 per month depending on local rates. This method also assumes the rate stays constant during the interest-only period. If you have a fixed-rate loan, the calculation holds. If you have an adjustable loan, you need to recalculate every time the rate changes. There is no single formula that covers both scenarios in one go. You need two separate calculations: one for the fixed period and one for each adjustment period.

Quick Reference Calculation
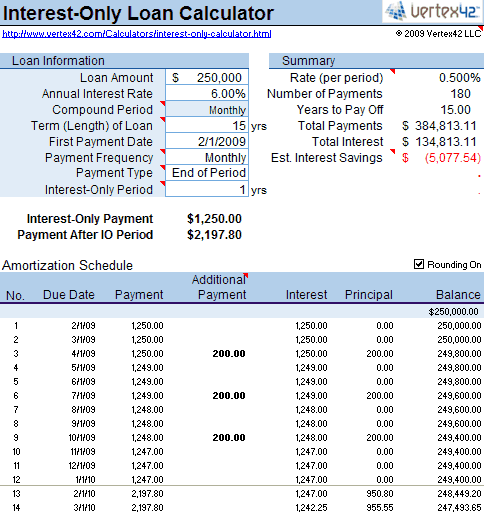
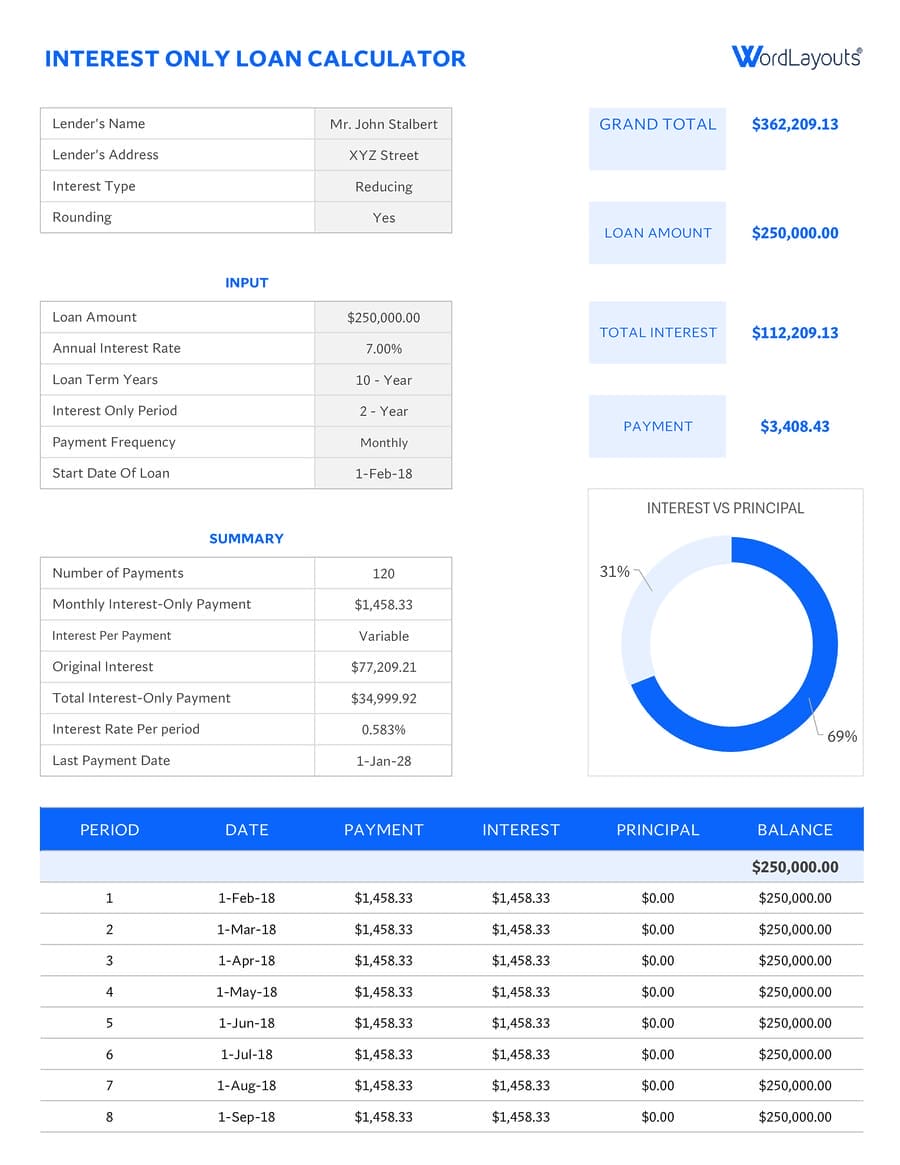
Principal balance: enter the current loan amount you owe. Annual interest rate: enter the yearly percentage as a decimal. Monthly payment equals principal times rate divided by twelve. Repeat for each adjustment date if the rate changes. The output is your interest-only payment for that period. Most spreadsheet templates for this take about two minutes to set up once. I usually build a simple sheet with columns for date, balance, rate, and payment, and a formula that auto-calculates the monthly amount. If the rate changes, I just update the cell and everything below recalculates. It saves time compared to doing each month by hand, and it reduces the chance of a manual entry error.
When Interest-Only Does Not Make Sense
There are scenarios where this approach creates more problems than it solves. If you are counting on the lower payment to free up cash for investments, the math only works if those investments return more than the loan rate. A 6.5% loan requiring a 7% return to break even is a slim margin. One bad quarter and you are underwater. Also, interest-only loans sometimes carry higher rates than comparable amortizing loans. Lenders price in the risk that the principal never gets paid down during the early years. I have seen interest-only products priced at 0.5% to 1% above the amortizing version. Factor that into your comparison before you commit. The lower monthly payment can be misleading if the annual cost is significantly higher over the life of the loan. There is no universal answer here. The calculation itself is mechanical. The decision about whether to use an interest-only structure depends on your cash flow, your exit strategy, and your risk tolerance. Do the math. Then decide whether the numbers actually work for your situation.