Understanding the Mechanics Before You Crunch Numbers
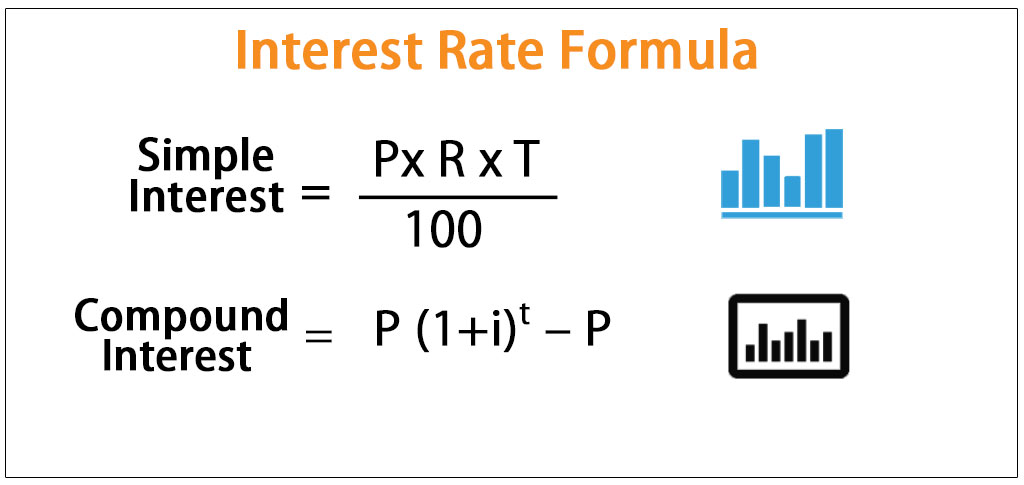
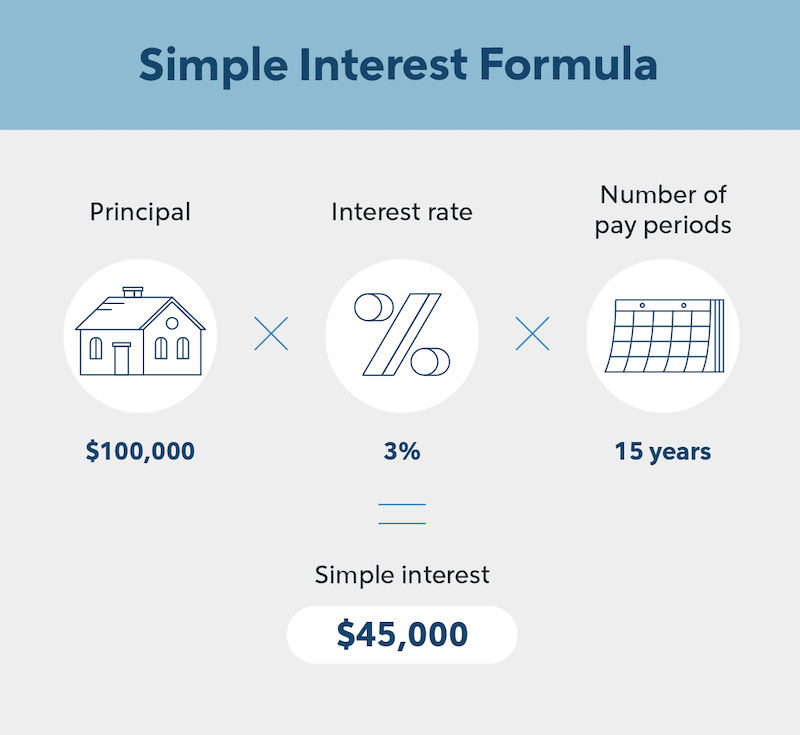
Most people treat interest calculations like they are some kind of arcane art. They are not. It is basic algebra with financial trappings. The formula everyone remembers from high school is A = P(1 + r)^t for compound interest and A = P(1 + rt) for simple interest. P is the principal amount, r is the rate per period expressed as a decimal, t is the number of periods, and A is the total amount owed or earned after time passes. Here is where things get interesting and where most online calculators fumble. Sometimes you do not know the rate. You know the principal, you know the final amount, and you know the time. Solving for r requires rearranging the compound interest formula to r = (A/P)^(1/t) - 1. That exponent of 1/t is the part that trips people up. On a basic calculator you can approximate it with repeated square roots if t is a power of 2, but for anything messier you need a spreadsheet or a proper financial calculator. I spent an afternoon once trying to reverse-engineer a loan rate from a statement that showed $12,847 paid back on a $10,000 loan over 18 months with monthly compounding. My first attempt using the simple interest formula gave me 28.47 percent, which was wildly wrong because the lender was compounding monthly. Switching to the compound formula and using Excel's RATE function returned 1.89 percent per month, or roughly 22.7 percent annualized. The difference between those two answers is the difference between thinking you got a reasonable deal and realizing you got absolutely wrecked. Compounding frequency matters enormously and not in the way most people expect. A rate advertised as 6 percent annually sounds straightforward until you realize that 6 percent compounded daily actually yields about 6.18 percent effective annual rate. A credit card at 24 percent compounded monthly is closer to 26.8 percent in reality. Lenders are required to disclose the APR, which is the nominal rate, but the effective annual rate or EAR tells you what you are actually paying. I always calculate EAR myself before signing anything above a car loan. The gap between APR and EAR might seem small on a mortgage but compounds over thirty years into tens of thousands of dollars.
For annuity-style calculations where you are making regular payments, the formula shifts again. The present value of an annuity formula is PV = PMT × [1 - (1 + r)^(-n)] / r. Solving for the payment amount when you know the principal is straightforward: PMT = PV × r / [1 - (1 + r)^(-n)]. This is how auto loans and mortgages work. Plug in a $25,000 car loan at 5.9 percent annual rate over 60 months and you get a monthly payment of about $482.28. Total paid over the life of the loan is $28,936.80. The interest portion alone is nearly $4,000. There are edge cases where standard formulas break down entirely. Variable rate loans are one. Adjustable-rate mortgages switch between periods based on an index like the SOFR or prime rate. You cannot calculate a single interest rate for these products. What you can do is model the expected payments under different rate scenarios. I built a simple sheet once that projected ARM payments for a client by taking their initial rate, adding the cap structure, and running sensitivity scenarios at plus 1, plus 2, and plus 3 percent from their starting rate. That gave them a realistic range instead of a single misleading number. The sheet took about twenty minutes to set up and saved them from signing a loan where the reset would have doubled their payment. The biggest pitfall I see repeatedly is confusing nominal and real rates. If your savings account pays 4 percent and inflation is running at 3.2 percent, your real return is closer to 0.78 percent, not 0.8 percent. The rough subtraction method works fine for low rates but starts drifting further from accuracy as inflation climbs. The exact Fisher equation is (1 + nominal) = (1 + real) × (1 + inflation). Rearranged: real = (1 + nominal) / (1 + inflation) - 1. At 4 percent nominal and 3.2 percent inflation that gives you 0.781 percent real return. Most people round that to 0.8 and feel fine about it until they realize their purchasing power barely moved.
Another thing nobody warns you about is the day-count convention. Banks do not all calculate interest the same way. Some use 30/360, assuming every month has thirty days and every year has 360. Others use actual/365, counting the real number of days between payments. On a $100,000 loan at 5 percent, the difference between these two methods over a year is roughly $139. Small individually, significant over decades or on larger balances. Municipal bonds and corporate bonds often use 30/360 while government securities typically use actual/day count. If you are comparing investment returns across different bond types, this inconsistency can distort your analysis by a full basis point or more. For quick calculations without a spreadsheet, here is what I keep in a notes file. Double the interest rate and divide into 72 to estimate doubling time. At 8 percent, money doubles in about 9 years. For tripling, use 114 instead of 72. At 6 percent, tripling takes roughly 19 years. These are approximations and they get less accurate at higher rates, but they are fast enough for back-of-the-envelope decisions during a negotiation or when you are comparing offers at the kitchen table. If you need something downloadable, I use a single Google Sheets template that handles compound interest, simple interest, annuity payments, and EAR conversion in one tab. You input the known variables and it outputs the rate, the payment, or the future value depending on which cell you leave blank. The RATE and PMT functions do the heavy lifting. It took me about forty-five minutes to build the first version and maybe an hour to add the EAR converter and the day-count convention selector. I share it freely through a public link because I have no reason to gate something that basic. Search for "interest calculation template spreadsheet" and you will find dozens of similar versions. The ones from financial institutions tend to be bloated with unnecessary features. The ones from individual creators are usually cleaner.
Get the Full Details
There is a limit to what any formula can tell you. Interest rate calculations assume you will make every payment on time, that the rate stays constant unless it is a variable product, and that fees and penalties are separate line items. They do not account for late payment penalties, prepayment fees, or the opportunity cost of locking money away for a fixed term. A high-yield savings account at 4.5 percent looks attractive until you realize you cannot access the funds for twelve months without penalty. The math says one thing. Your actual financial situation says another. The practical takeaway is to run the numbers yourself before trusting any offer. Lenders have incentives to present rates in the most favorable light possible. They will highlight the monthly payment and bury the total interest cost. A 30-year mortgage at 6.5 percent on $300,000 has a monthly principal and interest payment of $1,896.12. Over thirty years you pay $382,603 in interest. That is 127 percent of the original loan amount. Knowing how to calculate that yourself changes how you approach the conversation with a lender.