The formula itself is trivial
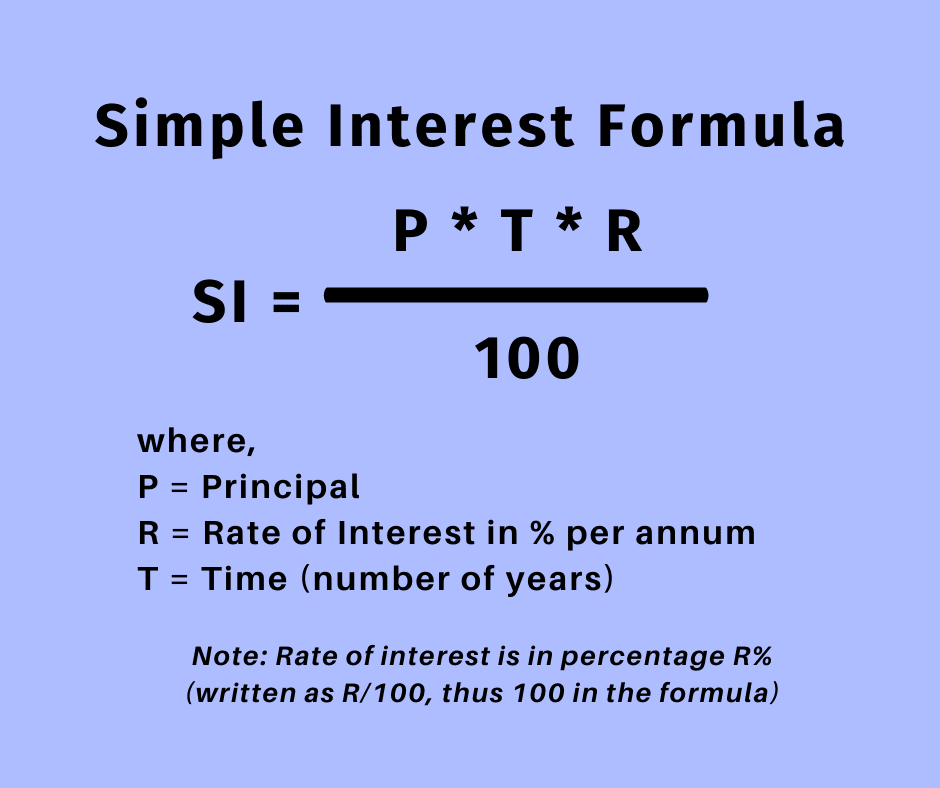
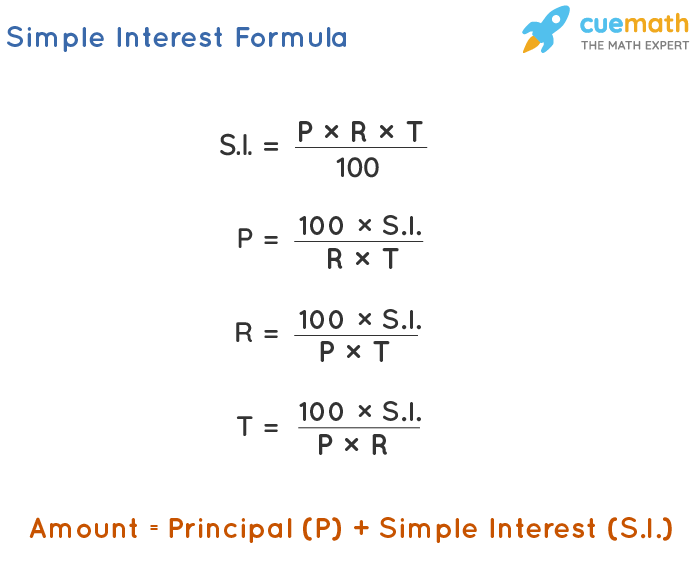
S equals P times R times T divided by 100. That is it. You take the principal, multiply by the annual rate, multiply by the time in years, and divide by 100 to convert the percentage. Anyone who tells you otherwise is trying to sell you a course. I have spent roughly eight years working with loan processors and accounting teams, and honestly, the formula is never the hard part. The hard part is knowing what goes into each variable and catching the edge cases that blow up when you are dealing with real money. I used to see people plug numbers into Excel without thinking about what the numbers actually represent. They would put 5 for a 5 percent rate and forget whether the time was in months or years. That single mistake cascades into thousands of dollars in wrong calculations across a portfolio. It happens constantly.
How To Calculate Simple Interest step by step
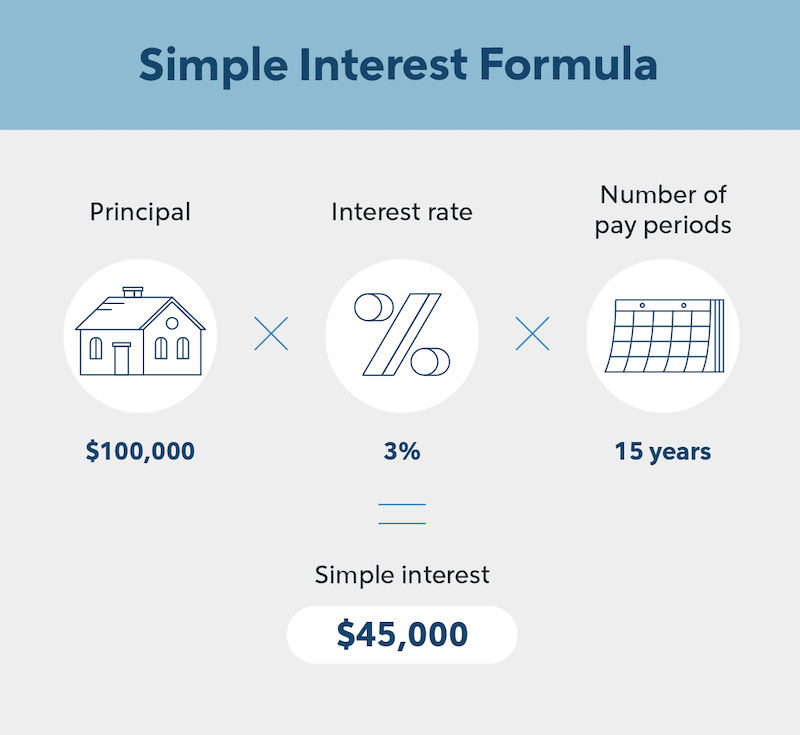
Write down the principal first. This is the starting amount of money being borrowed or invested. Next, identify the annual interest rate as a percentage. Then figure out the time period, but express it in years. If the loan is for 6 months, that is 0.5. If it is 90 days, divide by 365. Multiply all three together and divide by 100. The result is your simple interest. Here is a concrete example. Someone takes out a loan for $10,000 at 8 percent annual interest for 3 years. You multiply 10,000 by 8, which gives you 80,000. Then multiply by 3, which gives you 240,000. Divide by 100 and the interest comes to $2,400. The total amount owed back is $12,400. That is the entire calculation. No compound formulas. No amortization schedules. Just one straightforward multiplication and division.
What most people miss on the first try
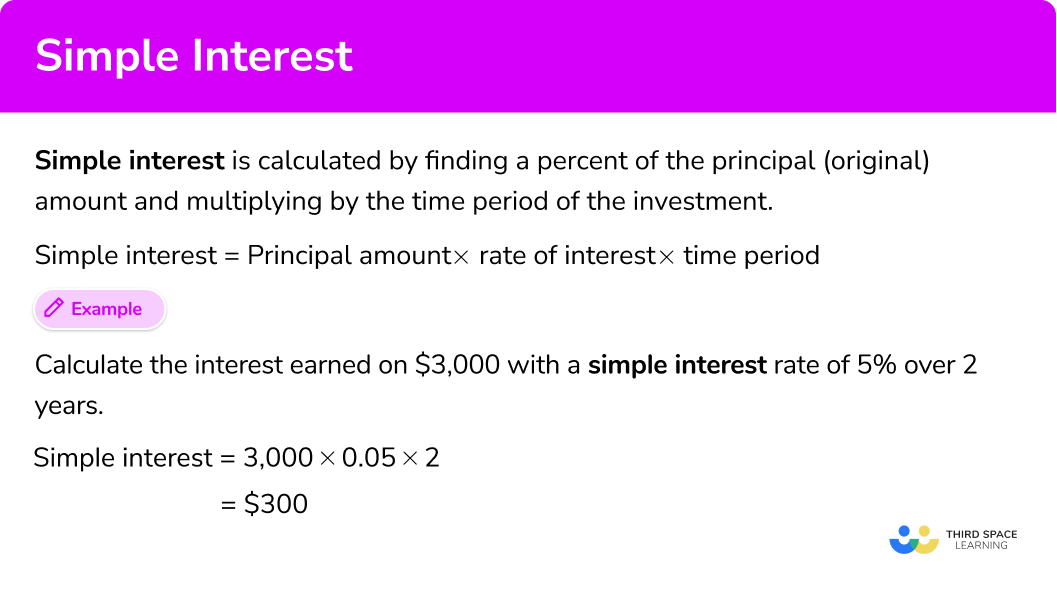
The rate and the time period need to match. This is the #1 error I see. If the rate is quoted annually but the time is in months, you have to convert one or the other before multiplying. Some banks quote monthly rates. Some quote daily. You need to check the actual terms of the contract. I once worked on a small business loan file where the lender stated an 11 percent annual rate but calculated interest using a 360-day year instead of 365. That difference looked small but added nearly $40 to the interest charge over one year. It is called the banker's year convention, and it is everywhere in commercial lending even though it quietly costs borrowers money. Another thing nobody warns you about is what happens when payments are made partway through the term. Simple interest does not automatically adjust when you make a partial payment unless the contract says so. Some people assume that paying down early reduces the total interest proportionally, but that is not always true. I had a client who made three mid-term payments on a simple interest note and expected the final interest calculation to reflect those reductions evenly. The lender used the original principal for the entire term because the note specified no prepayment adjustment. We ended up renegotiating the payoff statement, but it cost us about two weeks and roughly six hours of back-and-forth emails to sort out. The workaround was pulling the exact note language and pointing to the clause that said the interest was calculated on the unpaid balance at the end of each period. That changed the outcome significantly. You should also know that simple interest only applies to the original principal. It does not accumulate on previously earned interest. This is the defining difference from compound interest and it matters enormously over longer timeframes. A $5,000 investment at 6 percent simple interest over 10 years earns exactly $3,000 in interest. The same amount at 6 percent compounded annually over 10 years earns about $3,874. That gap widens the longer you go. Simple interest favors the borrower on loans and favors the lender on investments compared to compounding, depending on which side of the table you are sitting on.
Get the Full Details
Where simple interest breaks down
It is not a universal solution. Simple interest completely fails as a model for any scenario where balances change frequently, where payments are irregular, or where the financial product actually compounds by design. Mortgage amortization, credit card balances, and most savings accounts do not use simple interest at all. Trying to force simple interest calculations onto those products will give you wildly incorrect results. If you are working with a loan that has monthly payments reducing the principal, you need an amortization schedule, not a simple interest formula. The simple interest method also ignores the time value of money in any meaningful way beyond the basic rate, so it is a poor tool for comparing investment opportunities that have different cash flow timings. I once advised someone who was comparing two investment offers. One paid 7 percent simple interest annually. The other paid 6.5 percent compounded monthly. The simple interest rate looked higher at first glance, but when I ran the actual numbers over a 5-year horizon with reinvestment assumed, the compounded option came out ahead by about 4 percent in total returns. People often pick the higher nominal rate without understanding what the compounding frequency does to the effective yield. Always calculate the effective annual rate when you can, even if the product claims to be simple interest. There is also a legal edge case worth mentioning. In some jurisdictions, simple interest caps apply to certain consumer loans. If the stated rate exceeds the legal maximum, the excess interest may be unenforceable or even penalized. I encountered this with a payday loan product that disguised a 390 percent annual rate under a flat fee structure. The fee was calculated using a simple interest framework on paper, but the effective annual rate far exceeded state limits. We had to involve a consumer protection attorney to get the lender to recalibrate the charges. The lesson here is that the formula itself does not protect you. Regulatory compliance and actual rate checks matter just as much.
One final practical note. If you are doing this manually and dealing with fractional years like 45 days or 73 days, rounding errors add up fast. I switched to a spreadsheet template that kept all intermediate calculations at full precision and only rounded the final dollar amount to two decimal places. This cut my reconciliation time from about 45 minutes per loan file down to roughly 8 minutes. The difference is noticeable when you are processing more than a handful of files in a week.