What Actually Shows Up When You Run a Background Check
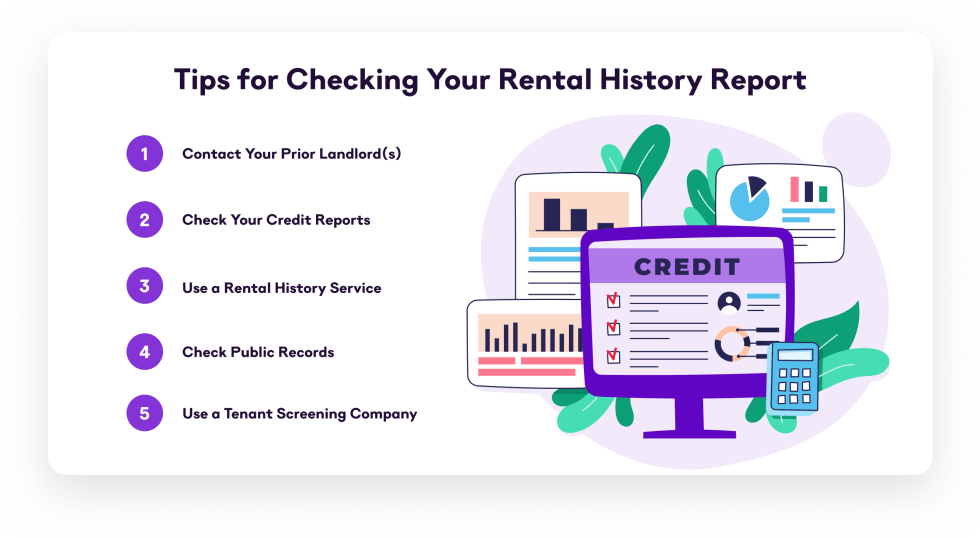
Rental history isn't a single database you can query like a credit score. It's a patchwork of eviction records from county courts, proprietary screening databases maintained by companies like CoreLogic and LexisNexis, and informal landlord references that vary wildly in quality. Understanding that fragmentation is the difference between walking into an application process confident and getting confused when three different reports show three different versions of your past. Start with the basics: pull your credit reports from AnnualCreditReport.com. All three bureaus, all at once, free of charge once a week. While these don't contain rental data directly, they can surface judgments, collections, and public records tied to unpaid rent or lease violations. A civil judgment from a small claims or housing court will appear here and can sink an application faster than most people realize. From there, request your report from the major tenant screening platforms. CoreLogic's SafeRent and LexisNexis instantID are the two most widely used. You can order a consumer report from each for a fee, typically between $15 and $30 per bureau. These reports aggregate eviction filings, lease terminations, and payment history from property management companies that feed data into their systems. The problem is that not every landlord or management company reports, so a clean report doesn't necessarily mean you have an unblemished record.
County court records are the most reliable source because they're public, but they're also the most fragmented. If you've lived in five different states across ten years, you're looking at roughly fifty counties to search. Most county clerk websites allow free search by name and date range, but the interfaces are inconsistent. Some require exact spelling matches. Others return hundreds of results for a common name with no way to filter by case type. I spent an afternoon hunting down a 2018 eviction filing in Maricopa County only to discover the defendant's name was listed as "Jane Doe dba J. Smith" under a DBA registration, which the basic search tool wouldn't surface. The workaround was to pull the docket index for landlord-tenant cases that year and scan through manually, which took about twenty minutes and confirmed the record was actually sealed and expunged two years later. The third option, and the one most people skip, is to contact your previous landlords directly. Not to ask for favors, but to get written confirmation of your move-out date, rent payment history, and any damages charged against your deposit. A signed letter on company letterhead carries more weight with screening companies than a database entry that might be outdated or incorrect. I've seen applications approved on the strength of a landlord reference letter that contradicted a stale screening report listing a vacated apartment as an active lease violation.
Common Pitfalls That Derail Applications
Data freshness is the biggest issue. Tenant screening databases update on their own schedules, often quarterly or annually. If you resolved an eviction in 2022 through a settlement or bankruptcy discharge, that resolution may not appear in the database for eighteen to twenty-four months. Meanwhile, the original filing is still visible and flagging applications. The fix is to obtain the court document showing the disposition and submit it alongside your application as an explanation addendum. Property managers encounter this regularly enough that most have a process for reviewing supporting documents, but you have to initiate it. Name variations create another frequent problem. If you've been known as "Robert" on leases but "Bob" on other documents, or if a hyphenated surname appears inconsistently across records, screening algorithms may fail to merge your data correctly. This can result in a ghost profile that looks like a stranger's rental history attached to your name. The solution is to submit a formal name variation statement with each application, listing every name and alias you've used for rental purposes along with the corresponding time periods and addresses. Some screening reports include a "risk score" similar to a credit score, but these are proprietary and unregulated. A score of 620 on one platform might mean barely acceptable risk while the same number on another platform indicates high risk. Don't fixate on the number. Focus on the underlying data points: eviction filings, unpaid balances, and lease termination reasons. Those are what matter to a human reviewing your application.
Get the Full Details
When the System Fails Completely
There are scenarios where checking your rental history yields nothing useful. If you've always rented from individual owners who never report to screening agencies and don't participate in data-sharing programs, you may have no digital footprint at all. Conversely, if you lived in subsidized housing or public housing, those records are governed by different privacy laws and typically don't appear in commercial screening reports. In both cases, the burden shifts entirely to documentation. Build a rental resume: a single PDF containing lease agreements, payment histories, landlord contacts, and any correspondence related to move-ins and move-outs. Keep it organized by address and date. This document becomes your primary proof of rental history when no database can provide it. Another hard limit: expunged or sealed records. Legally, screening companies should not report these. In practice, data brokers sometimes fail to purge them correctly. If you discover an expunged record on your report, the correction process involves filing a dispute with the screening company, attaching the court order, and waiting thirty to forty-five days for resolution. It's straightforward if you have the paperwork. It's frustrating if you don't, because recreating court documents from a closed case can require a formal records request that takes weeks to process. The reality is that no single source gives you a complete picture. Combining credit bureau checks, tenant screening reports, county court searches, and personal documentation gets you as close as you're going to get. It takes time, usually two to three hours spread across a weekend if you're thorough, but that investment prevents the kind of surprises that cost you a deposit on an apartment you otherwise qualified for.