What Real GDP Actually Measures
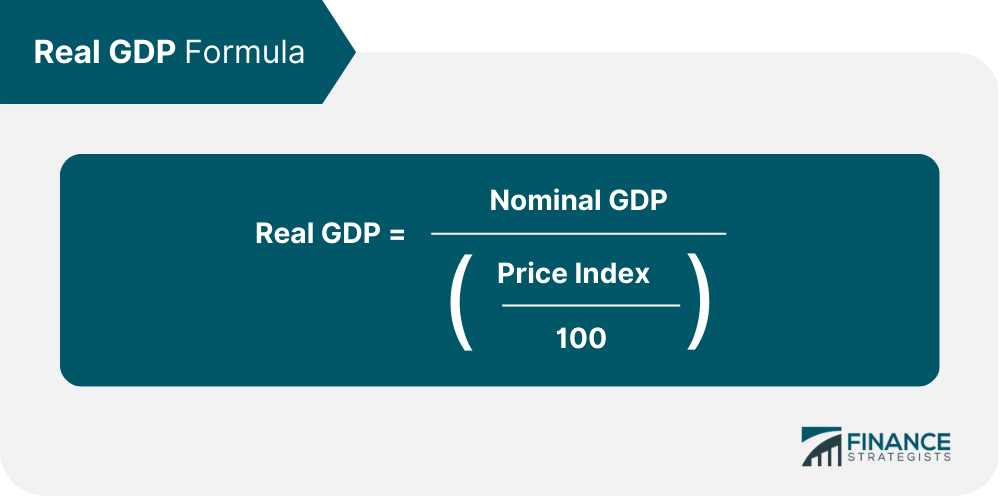
Real GDP strips out price changes so you can see whether an economy is genuinely producing more stuff or just charging more for the same stuff. That distinction matters way more than people admit. Nominal GDP rises every time inflation ticks up, even if factories aren't running any harder. Real GDP is the only number that tells you if output actually changed. The basic mechanism is straightforward: you take current-year prices and divide them by a price index to get constant-dollar values. But the devil is in the details, and most guides skip the parts that make your actual work harder.
How To Compute Real Gdp Using a Chain-Weighted Index
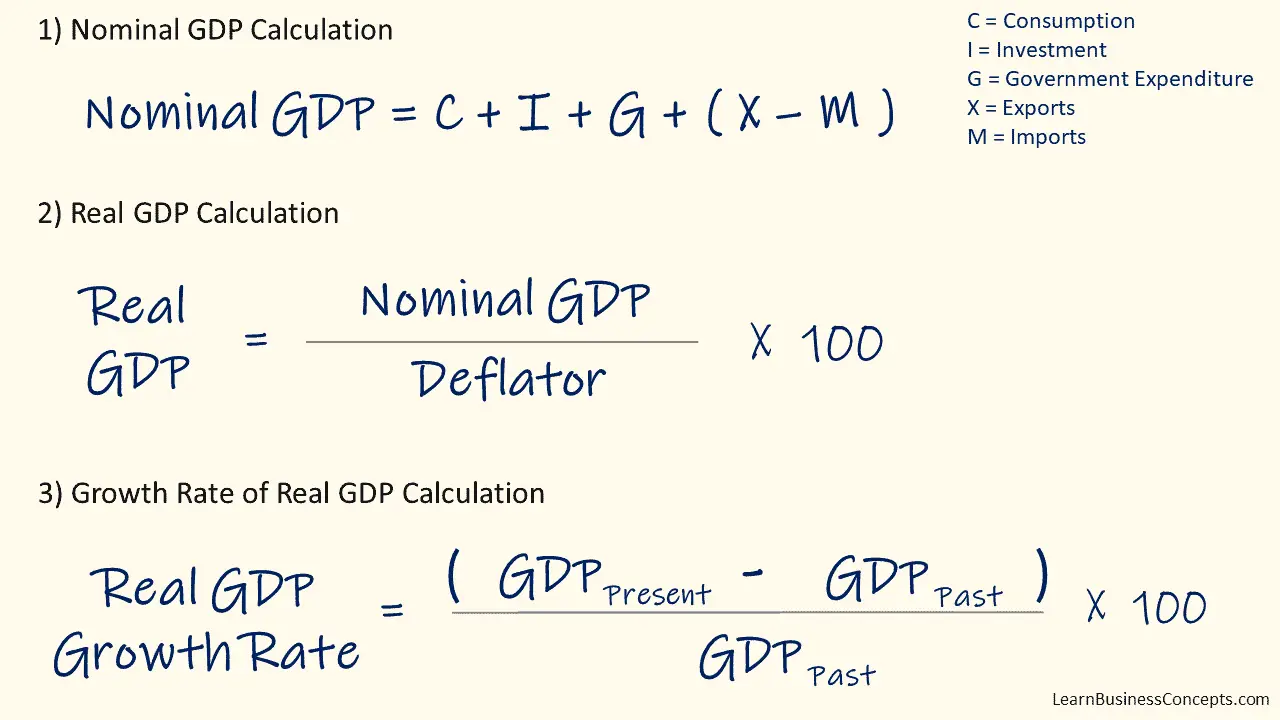
The Bureau of Economic Analysis switched to chain-weighting in 1996, which means you can't just pick a base year and call it done. The base year rotates every period. If you're working with NIPA Table 1.1.5 or the equivalent from your national statistics office, you'll see real GDP reported directly. When you have to compute it yourself from component data, here's the path that actually works. You need two things: nominal values for each component and the corresponding price deflateators. Nominal GDP is just market prices times quantities summed across all categories—consumption, investment, government spending, net exports. The deflator for each category comes from the relevant price index. Personal consumption expenditures use the PCE price index. Gross private domestic investment uses the fixed investment price index. Government consumption uses the government consumption expenditures and gross investment price index. You do not use one blanket CPI for everything. That's the single biggest mistake I see in graduate student papers and amateur economic models. The formula for each component is:
Real Component = (Nominal Component / Price Deflator) × 100 Then sum the real components. The 100 is just to match the index scale. If your deflator is expressed as 125.4, dividing by 125.4 and multiplying by 100 gives you the real value in base-year dollars. For chain-weighted real GDP specifically, you compute link ratios. Take real GDP at current prices from year t-1, divide by real GDP at chained dollars from year t-1, and multiply by the chained-dollar value. This links each year to the previous one instead of anchoring to a single distant base year. The BEA publishes these chained-dollar series directly, but when you're reconstructing them from raw data, the linking process is where things get messy.
Get the Full Details

I spent three weeks in 2019 trying to reconcile a country-level real GDP series from IMF data against national accounts from the Ministry of Finance, and the discrepancy came down to one thing: inventory valuation. The IMF uses average market prices for inventory changes while the national accounts use purchase prices. The gap showed up mostly in the investment component and accounted for about 0.3 percentage points of the growth rate. I ended up adjusting the inventory investment line by the ratio of the two price measures and the series aligned. Nobody writes about inventory valuation adjustments in textbooks, but it will quietly wreck your numbers if you ignore it.
Common Data Sources and Their Quirks
If you're using US data, the BEA's GDP website is the source. Download Table 1.1.4 for nominal GDP by component and Table 1.1.6 for chain-type quantity indexes or price indexes. The NIPA tables are freely available and updated quarterly. For international work, the World Bank's national accounts data and the OECD's Main Economic Indicators are reasonable starting points, but always check the methodology notes. Definitions vary enough between countries that stacking them without adjustment produces garbage. One thing nobody warns you about: seasonal adjustment. Nominal GDP is often reported both seasonally adjusted and unadjusted. Make sure you're not mixing the two. I've seen it happen in policy briefs where the real series was SAAR but the price deflator was not, creating a ghost inflation trend that looked alarming until someone actually traced it back to the data processing pipeline.
Edge Cases Where This Method Breaks Down
Real GDP is not a perfect measure, and it fails in predictable ways. Hyperinflation environments break the chain-weighting approach because price relative changes become so extreme that the Laspeyres and Paasche indexes diverge dramatically. In those cases, you may get more reliable results by recalibrating to a very recent base year and rebuilding the chain from scratch rather than relying on published series that were anchored to a pre-crisis period. Another failure mode is economies with large informal sectors. Real GDP simply cannot capture transactions that don't pass through market prices. Haiti, parts of sub-Saharan Africa, and rural economies elsewhere have substantial informal activity that skews the real GDP number downward relative to actual living standards. No computational trick fixes this. You either supplement with household survey data or you accept that the number underreports. Quality change is another silent distortion. If a smartphone costs the same nominal price as five years ago but has twice the processing power, the hedonic adjustment built into the price index tries to account for it, but the adjustment is rough. Your real GDP growth may understate genuine improvements in output quality. This is a known limitation that the BEA openly acknowledges in their methodology papers, and it affects every advanced economy.
A Practical Step-by-Step Walkthrough
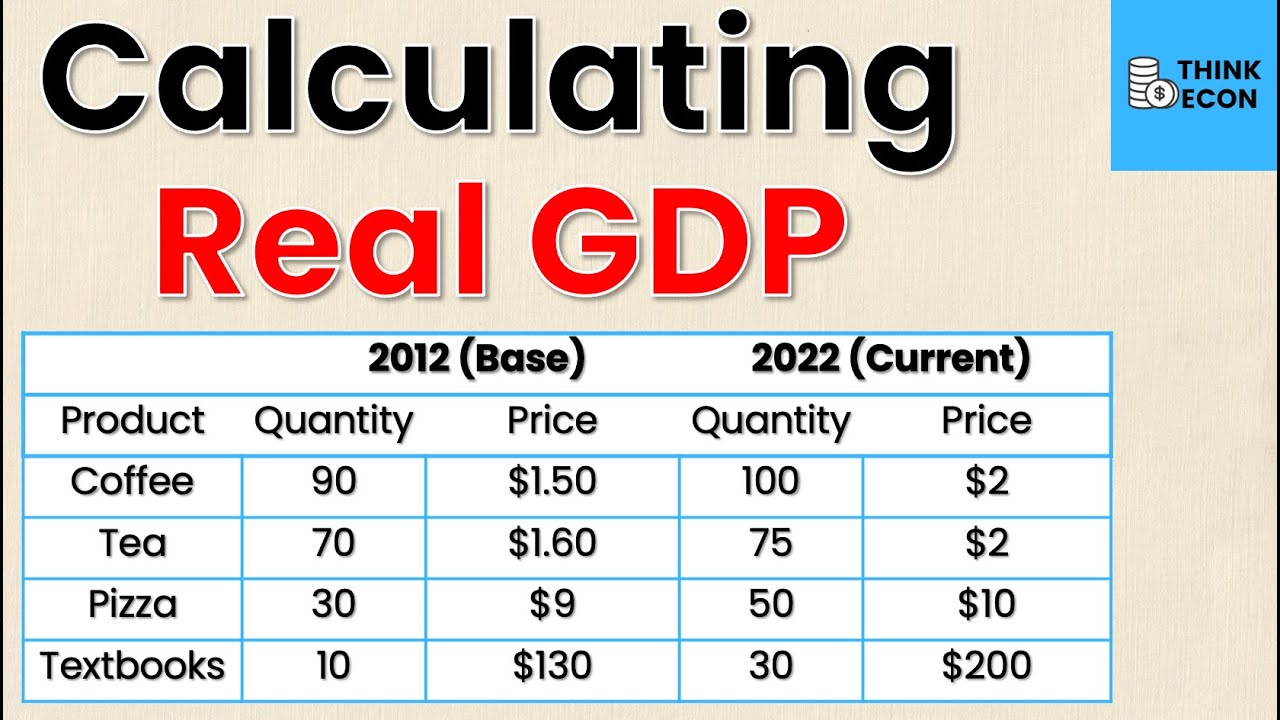
Say you have the following annual data for a fictional economy: Consumption: nominal 500 billion, deflator 112.3 Investment: nominal 200 billion, deflator 108.7
Government: nominal 150 billion, deflator 115.2 Net exports: nominal -50 billion, deflator 110.1 The calculations go like this:
Real consumption: 500 / 112.3 × 100 = 445.24 Real investment: 200 / 108.7 × 100 = 183.99 Real government: 150 / 115.2 × 100 = 130.21
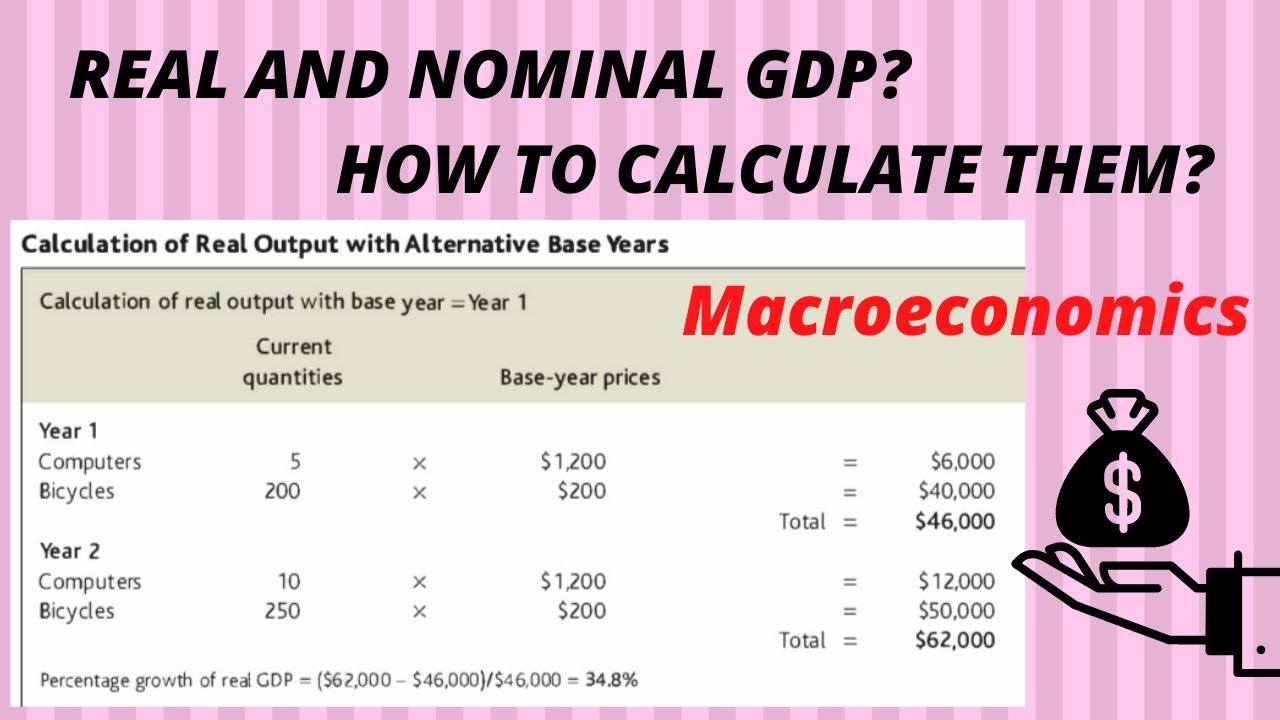
Real net exports: -50 / 110.1 × 100 = -45.41 Sum: 445.24 + 183.99 + 130.21 - 45.41 = 714.03 billion in base-year dollars. Check your work against the published real GDP figure for the same year. If they don't match within rounding tolerance, one of your deflators is wrong or you're using the wrong component definition. Mismatched definitions are far more common than calculation errors. Verify that your investment category matches the BEA or national source definition before trusting the spreadsheet.
When working with quarterly data, convert to annual averages for the deflators before applying the formula, or use the exact quarterly deflators if they're available. Mixing annual deflators with quarterly nominal data introduces seasonal artifacts that look like real economic when they're actually just data structure noise.
Why People Get This Wrong
The most frequent error is using the CPI as a blanket deflator for everything. The CPI measures consumer prices, not business investment prices or government procurement prices. The difference between the PCE deflator and the CPI is small in normal times—usually half a percentage point or less—but it compounds across decades and becomes a material error in long-run growth comparisons. Use the correct deflator for each component. It takes ten minutes to find the right table and saves you from having to explain away a systematic bias later. Another trap is treating real GDP per capita as a welfare measure without accounting for population aging, immigration, or changes in the labor force participation rate. Real GDP per capita rose steadily in many countries through the 2010s while median household income stagnated. The gap isn't a calculation error. It's a feature of what the metric actually measures. The chain-weighted approach itself has a known issue called the unit-of-measurement problem. The level of real GDP depends on which year you choose as the reference period for the weights, even though the growth rates remain consistent. This is mostly an academic concern unless you're comparing level estimates across countries using different base years. Just standardize to a common reference period and document it.
Where to Get the Data
For the United States, the BEA's downloadable tables at bea.gov are the primary source. Tables 1.1.4, 1.1.5, and 1.1.6 cover nominal GDP, real GDP in chained dollars, and the GDP price deflator. The data is in Excel and CSV format and updates within three weeks of each quarter's release. For other countries, start with your national statistics office, then cross-check with the World Bank's National Accounts Data and the OECD Stat database for consistency. When the numbers disagree, the national source usually has the more complete breakdown, but the international sources are better for side-by-side comparison because they apply standardized definitions across countries. If you're building a model or doing research that requires a long historical series, be aware that many countries revised their methodologies around the 2008 SNA update. Pre-2008 data may not be directly comparable to post-2008 data without a bridging adjustment. Check the revision history notes before pulling data from before 2010.