Why Your Journal Entries Keep Looking Weird
An accounting journal is just a chronological list of every financial transaction a business records. That's literally it. Most people overcomplicate this because they treat it like math class instead of bookkeeping. The core concept is double-entry bookkeeping: every transaction touches at least two accounts, and the debits and credits must always balance to zero. When you understand that, everything else is just mechanics. Here is the actual process I use when setting up journal entries, whether manually or in a spreadsheet. First, identify the transaction. Be specific. "Paid vendor" is not enough. You need the date, the amount, the vendor name, and what was purchased. I once had a client who sent me a spreadsheet with entries that said "Office supplies – $4,200" across three different months. When I asked what the supplies were, they couldn't tell me. Turns out $2,800 of that was software licenses that should have been amortized, not expensed outright. That was a tax issue that took two months to fix. So always dig into the detail before you book it.
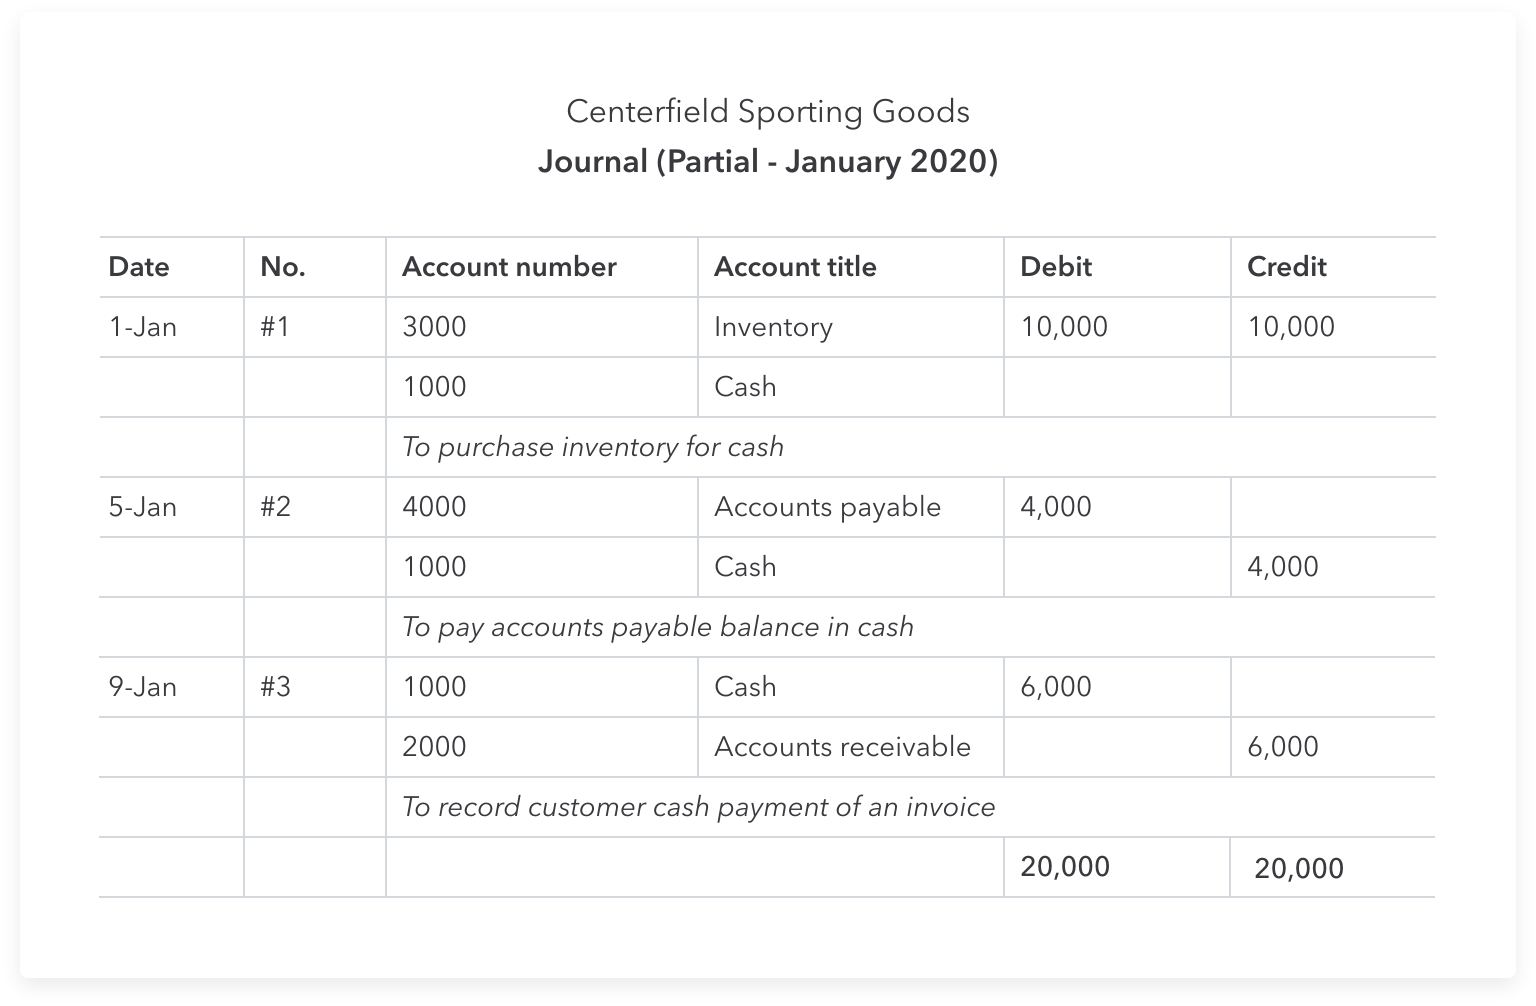
Second, determine which accounts are affected. Every transaction moves value between accounts. If you pay cash for equipment, your Cash account goes down and your Equipment account goes up. If you buy on credit, Cash doesn't move but Accounts Payable appears instead. This is where most beginners get stuck—they can't figure out which accounts to touch. Make a quick reference sheet of your chart of accounts with a column noting whether each one normally carries a debit or credit balance. Assets and expenses carry debits. Liabilities, equity, and revenue carry credits. Third, assign the debit and credit. The rule is simple: debits go on the left, credits on the right. The total debits must equal total credits. For every transaction. Always. If they don't match, something is wrong and your books are now unbalanced. A single mismatched entry throws off every downstream report—your trial balance, your income statement, your balance sheet. Fix it before you move on. Fourth, write the description. Include enough detail that anyone reviewing this twelve months from now will understand what happened without having to ask you. Date, accounts, amounts, and a one-line explanation. That's all you need.
Here is a real example. You purchase a delivery van for $35,000, paying $7,000 down and financing the rest. Debit: Vehicle Asset account — $35,000 Credit: Cash — $7,000
Get the Full Details
Credit: Vehicle Loan Payable — $28,000 Debits total $35,000. Credits total $35,000. Balanced. Another example, simpler. You receive a $1,200 payment from a client for work already billed.
Debit: Cash — $1,200 Credit: Accounts Receivable — $1,200 Cash goes up, money the client owes you goes down. No revenue is recorded here because you already recognized it when you sent the invoice.
What People Get Wrong About Journals
The biggest mistake I see is people recording revenue when they send an invoice instead of when they receive payment, or vice versa, without thinking about their accounting method. If you're on cash basis, revenue is recorded when cash hits the account. If you're on accrual, it's recorded when the invoice is sent. Mixing these up in the same journal is how fraud gets hidden and how audits go sideways. Another thing nobody warns beginners about: recurring journal entries. Once you set up a monthly entry for things like depreciation, prepaid rent amortization, or subscription expenses, your software should handle it automatically. If you're manually entering the same adjusting entry every month, you're wasting time and creating error risk. Set it and forget it, but audit it quarterly to make sure nothing broke. Here is a specific edge case I ran into last year. A client was using a flat depreciation rate for all their equipment at 20 percent per year. One of their machines was actually a specialized piece of furniture that wore out faster. I suggested switching to a units-of-production method for that asset instead, calculating depreciation based on actual usage hours rather than time. It changed their annual depreciation expense by about $3,400 and made their cost of goods much more accurate. Sometimes the standard approach is wrong for your situation and you need to adjust it.

Tools and Formats
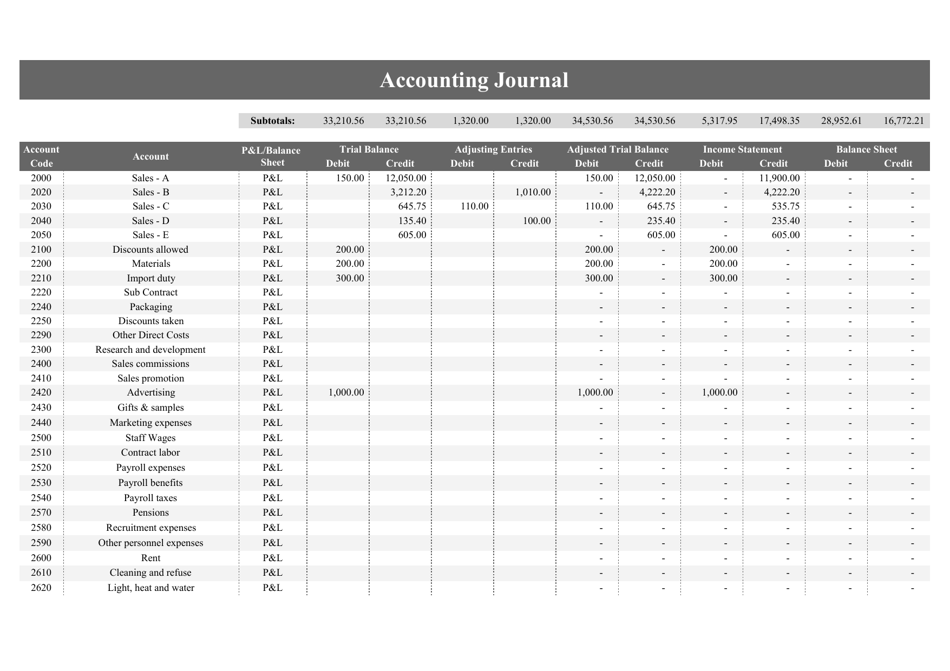
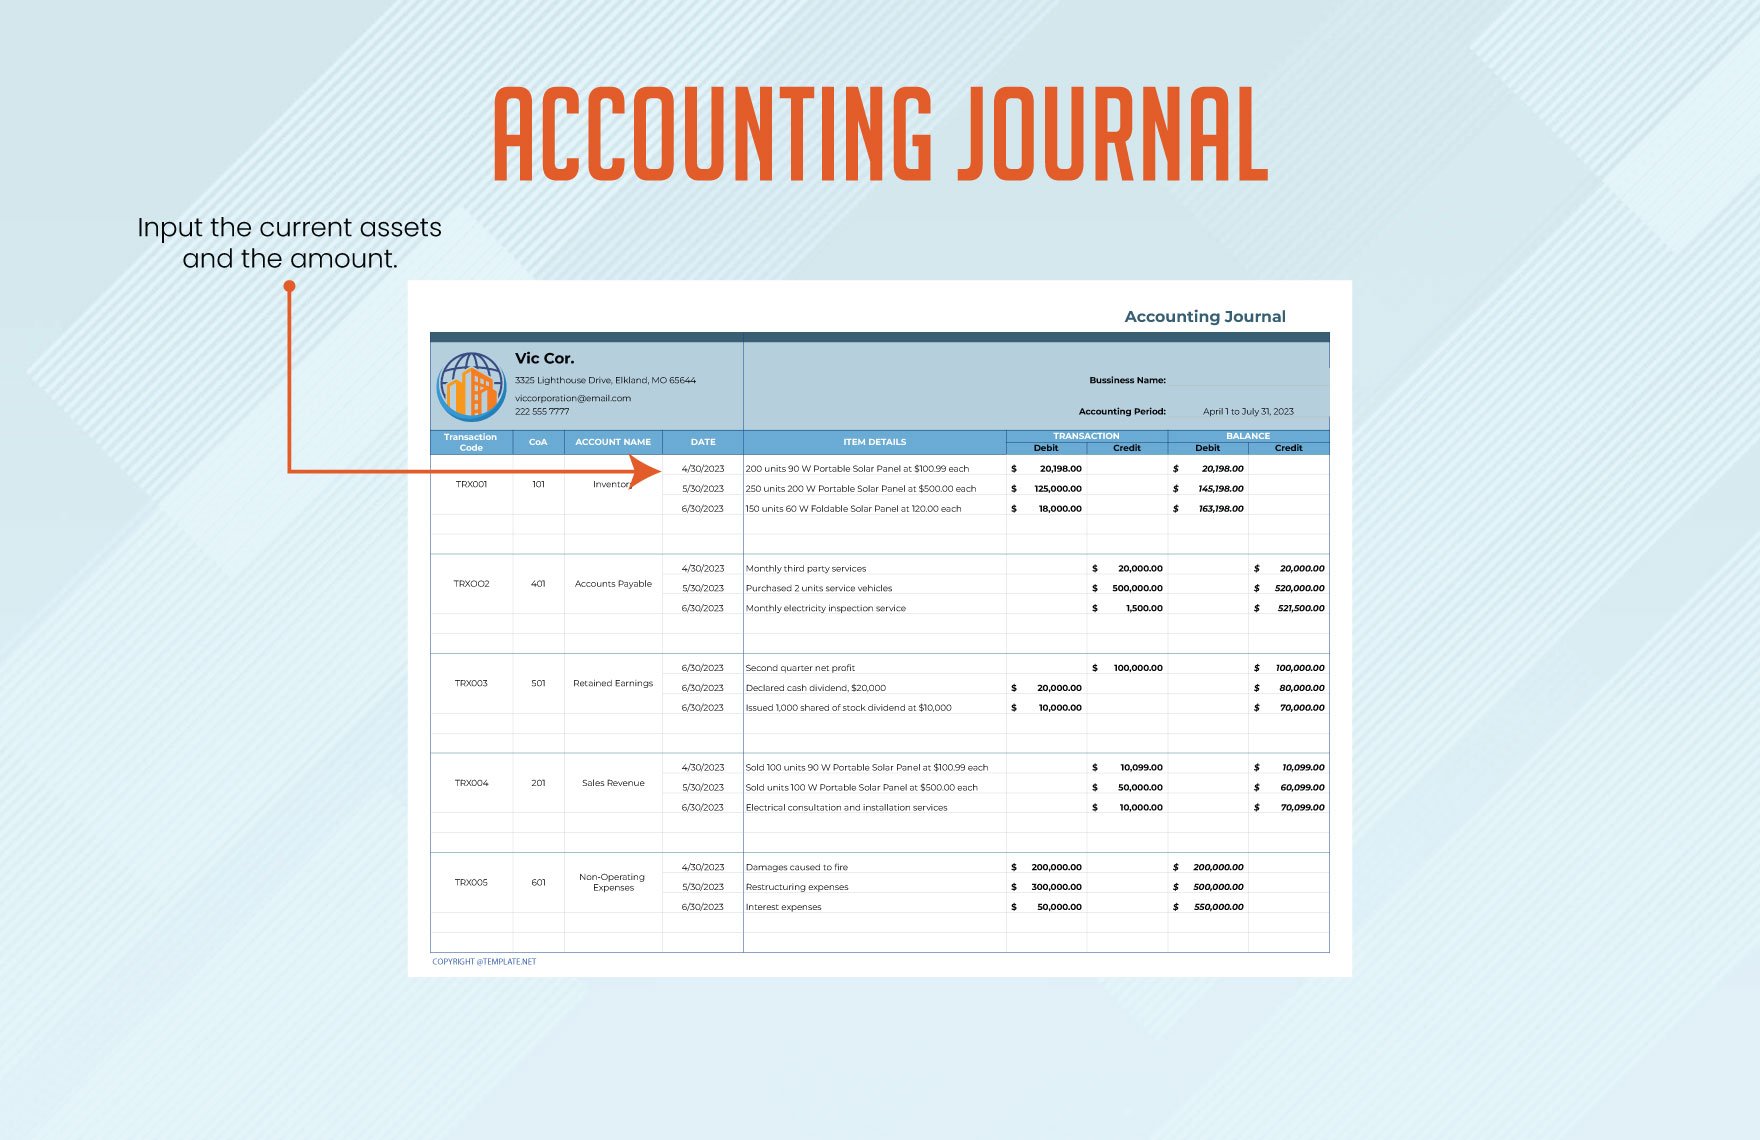
You can create journal entries in a spreadsheet, in accounting software like QuickBooks or Xero, or even in a physical ledger if you are running something small and straightforward. Spreadsheets give you full control but require manual discipline. Accounting software automates a lot of it but can punish you when something doesn't fit its workflow. If you want a free downloadable template, I keep a basic journal entry spreadsheet with pre-formatted columns for date, description, account, debit, credit, and running balance. It includes validation that flags any entry where debits and credits don't match. I don't host it publicly but it is straightforward to build yourself in under an hour if you have basic Excel or Google Sheets skills. Just create columns in that order, use a SUMIF formula to total debits per entry, and add a conditional format rule that highlights rows where the debit total differs from the credit total by more than a penny.
Where This Falls Apart
Journals work well until your transaction volume gets large enough that manual entry becomes a bottleneck. At that point you need automated data feeds from your bank and payment processors. Even then, reconciliation is where journals break down. Banks don't always match your records perfectly. Fees appear without explanation. Chargebacks show up retroactively. If you are not reconciling monthly, you are flying blind and the errors compound. The other hard limit is multi-currency transactions. If your business deals in more than one currency, a journal entry needs the exchange rate at the time of the transaction and then a separate adjusting entry when rates shift. Most small-business software handles this poorly. If you do significant international work, you will need dedicated multi-currency accounting tools or a plugin that actually tracks FX gains and losses correctly. Ultimately, a journal is only as good as the data going into it. Garbage in, garbage out. Take the time to get the entries right the first time and you save weeks of cleanup later.