The Spreadsheet That Actually Works
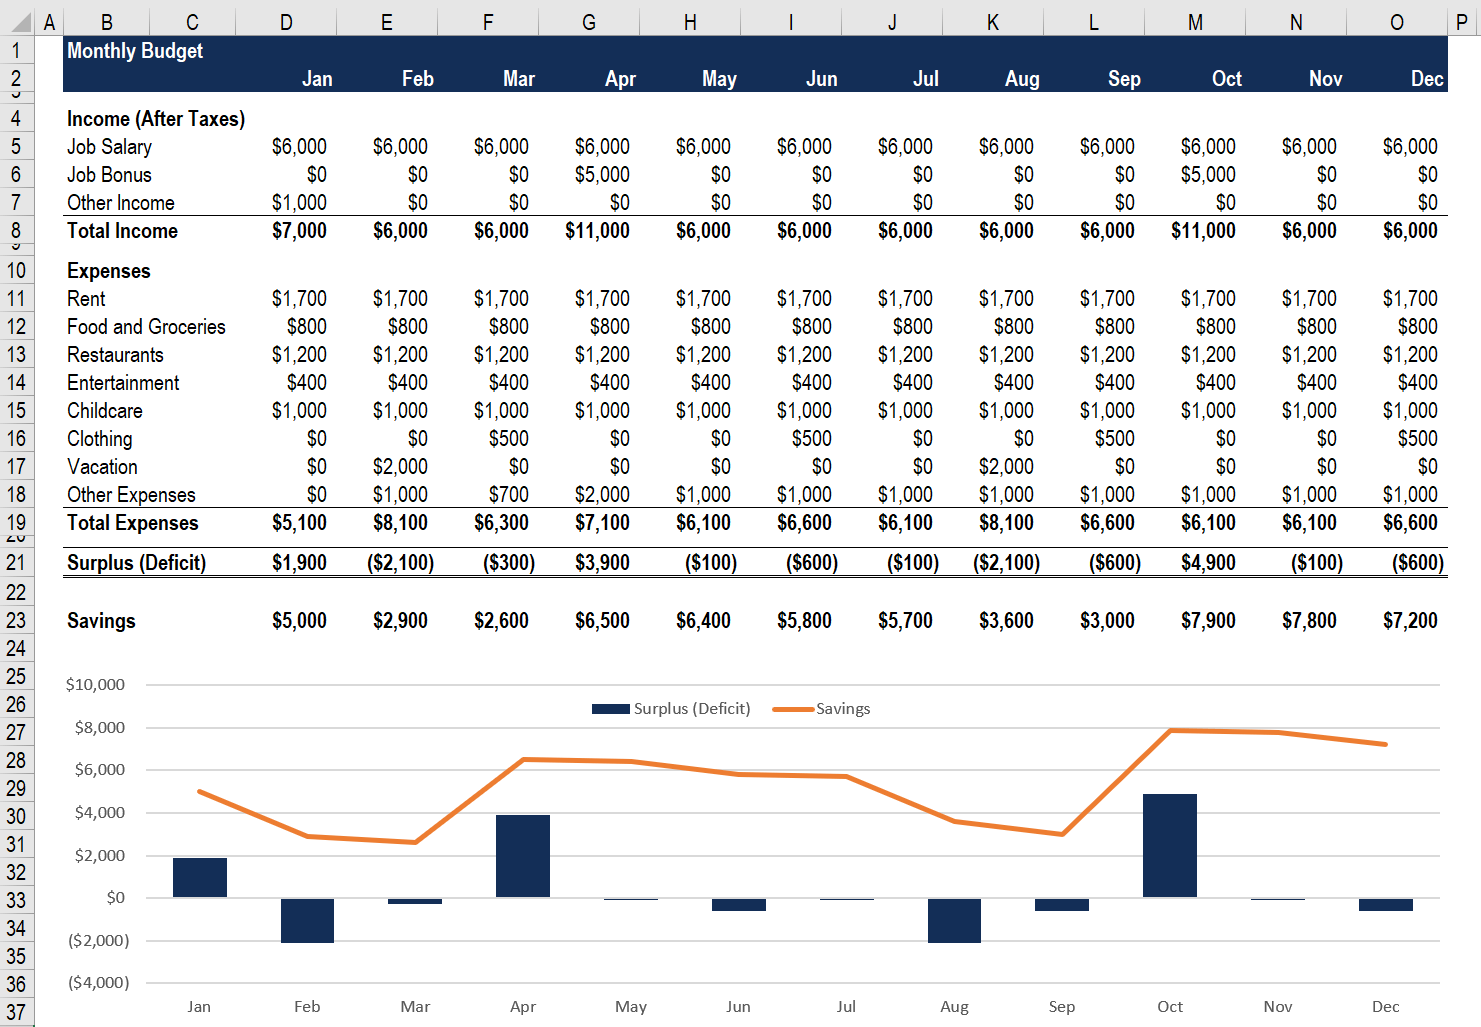
A finance worksheet is not a magic number machine. It is a structured layout where income, expenses, assets, and liabilities sit side by side so you can see where money goes each month. Most people build these poorly, which is why half of them end up being abandoned after three weeks. Start with the columns. I usually go with: Category, Budgeted, Actual, Difference, Year-to-Date Budgeted, Year-to-Date Actual, and Notes. The Notes column is where most templates cut corners, but it is the single most useful field when you are trying to remember why you spent $340 on plumbing in March. Set up your rows in this order: fixed income first, then variable income if you have it, fixed expenses, variable expenses, debt payments, savings contributions, and a miscellaneous bucket at the bottom. The miscellaneous row catches everything that does not fit neatly elsewhere. Without it, you will start throwing irregular expenses into the wrong category and your variances will look worse than they actually are.
Use simple SUMIF formulas rather than hard-coding totals. A proper setup looks like =SUMIF($A$2:$A$50,"Groceries",$F$2:$F$50) for year-to-date tracking. It takes slightly longer to build initially but saves roughly forty-five minutes per month when reviewing or adjusting categories later.
Handling the Carryover Problem
Here is a realistic edge-case I ran into repeatedly: when a budget category comes out significantly under-spent one month, most beginners just let that leftover money vanish and start fresh the next month. This looks clean on paper but produces wildly inaccurate annual projections. The workaround I settled on is a carryover column. At the end of each month, you calculate the variance and move the surplus or deficit into a "Carry Forward" row that pulls into the next month's opening balance. The formula is essentially: next month's budget = original budget + prior month's variance. This keeps your annual total honest without requiring a separate spreadsheet to track it. They make the worksheet too granular. I once saw someone with forty-three expense categories for a household of two people. The overhead of maintaining that level of detail eats into the actual benefit. Six to eight top-level categories is usually sufficient. You can always drill down into subcategories inside the Notes column when something warrants attention. Another mistake is tying the worksheet too tightly to bank feeds from day one. Automated imports sound convenient but they introduce categorization drift over time. I recommend manual entry for the first sixty to ninety days until you understand your actual spending patterns, then layer in automation afterward. The resulting data quality is noticeably higher.
Get the Full Details

When a Spreadsheet Is Not the Right Tool
A finance worksheet built in Excel or Google Sheets works well for individuals and small households managing up to about five accounts and twenty recurring transactions per month. Beyond that threshold, especially if you are tracking multiple business entities, investment portfolios, or partnership distributions, the spreadsheet starts to crack. Data entry becomes a full-time job, reconciliation errors creep in, and version control turns into a problem. In those cases, dedicated personal finance software like Money Manager or actual accounting platforms are worth the switch, even if the initial learning curve is steeper. If you want a starting template, I keep a basic version in Google Sheets with the structure described above. Search for "finance worksheet template no budgeting apps" and you will find several community-shared files. Pick one that has separate tabs for monthly entry and annual rollup, then delete everything you do not need rather than fighting against a template that forces features on you.
Keeping It Usable Long Term
Commit to entering data within forty-eight hours of each transaction. Anything older than that and the numbers stop reflecting reality and start becoming historical fiction. Pick a single day each week, Sunday evening works for most people, to do the full month review. That review should answer three questions: what was over budget, what was under budget, and why did the variances happen. The worksheet itself does not need to be beautiful. It needs to be accurate and it needs to be updated. A plain grid with correct formulas beats a fancy design with broken calculations every time. Most of the people who successfully maintain these long-term do it because they kept the structure simple enough that updating it did not feel like extra work on top of their regular bills.