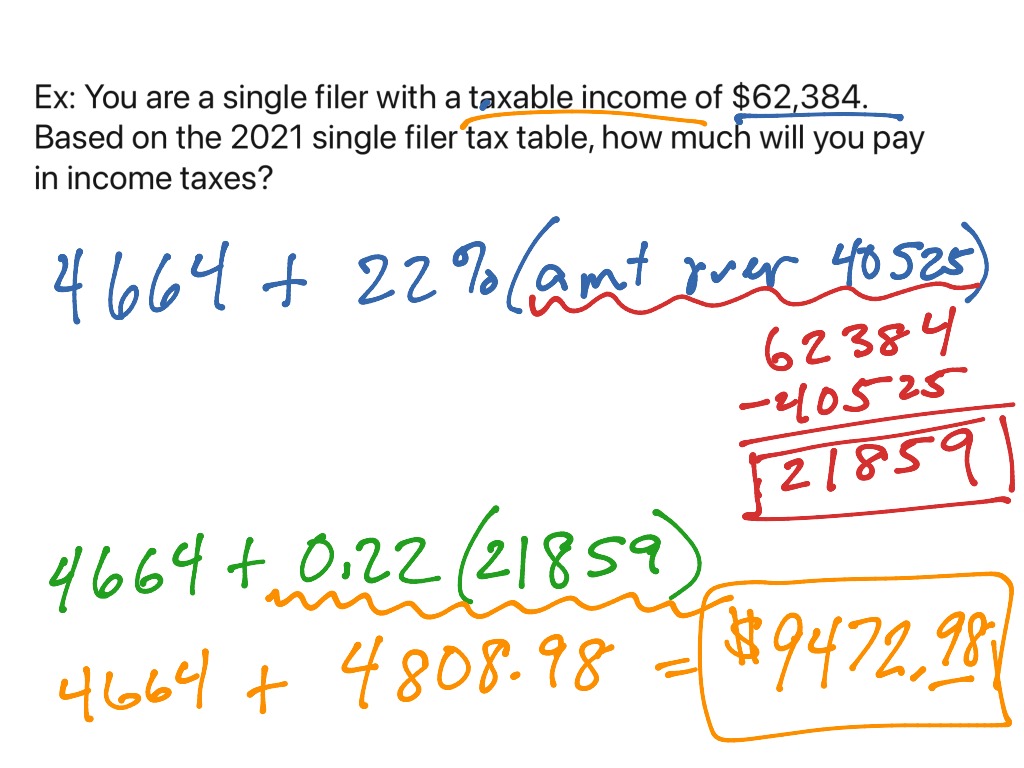
Mathematical Tax Computation: How It Actually Works
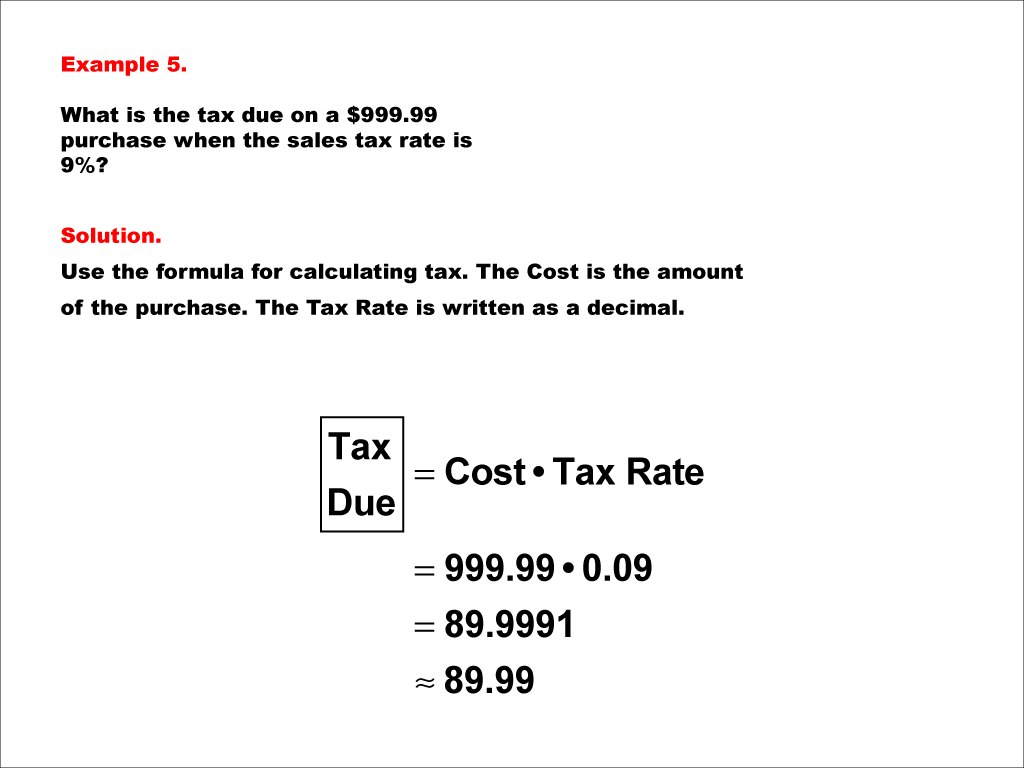
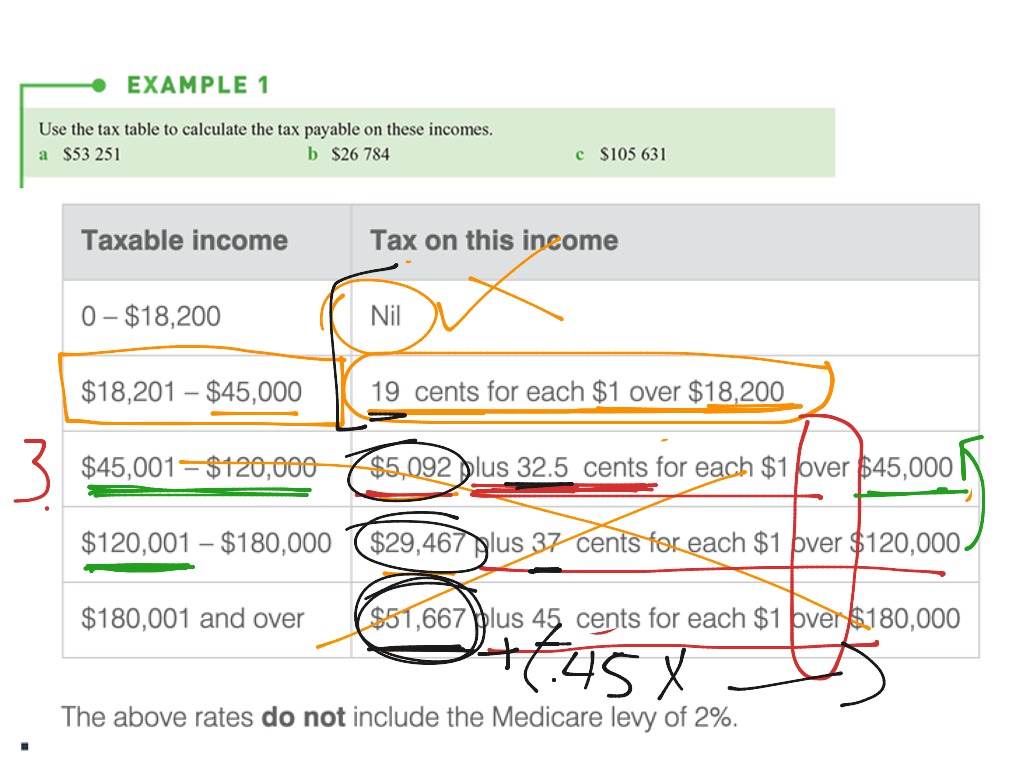
Tax in math isn't really a separate subject. It's arithmetic applied to brackets, thresholds, and rates. People complicate it because they overthink the terminology. The mechanics are straightforward once you strip away the jargon. At its core, doing tax math means applying percentage rates to income portions that fall within defined ranges. That's it. Progressive taxation simply means each slice of income is taxed at its own rate, not the total sum. Here's the practical method. Take your gross income. Subtract any allowable deductions to get taxable income. Then walk through each bracket from the bottom up. Multiply the portion of income within each bracket by that bracket's rate. Sum the results. That's your total tax liability.
A common mistake beginners make is applying the top bracket rate to their entire income. If you earn just enough to cross into a higher bracket, only the amount above the threshold is taxed at that higher rate. The rest stays in the lower brackets. I've seen this error repeatedly in exam settings and in actual payroll calculations. It costs people money, sometimes significantly so. Let me give you a concrete example with real numbers. Say the tax brackets are structured like this: zero percent on the first 10,000 dollars, ten percent on income between 10,000 and 40,000 dollars, and twenty percent on anything above 40,000 dollars. Your gross income is fifty thousand dollars. After a standard deduction of five thousand dollars, your taxable income is forty-five thousand dollars. The first ten thousand is untaxed. The next thirty thousand falls in the ten percent bracket, which gives three thousand in tax. The remaining five thousand sits in the twenty percent bracket, adding another thousand. Total tax is four thousand dollars. Not complicated. Just careful. Now there's a detail most guides skip. Tax tables versus tax calculators. In practice, many tax authorities publish lookup tables rather than clean formulas. When I was handling quarterly estimates for a small consultancy, we used tables because the rates had marginal quirks that formulas didn't capture cleanly. Tables prevented rounding disputes with the revenue service. The trade-off is that tables are harder to work with manually, which is why spreadsheet automation became standard in our office. One afternoon I spent three hours reconciling a table-based calculation against a formula-based one only to discover a forty dollar discrepancy caused by a bracket edge case at exactly 40,000 dollars. The formula gave a slightly different answer because it treated the boundary differently than the published table did. I switched to table-based calculations after that.
Another counter-intuitive point: deductions don't always save you money at your marginal rate. They save you money at your marginal rate only if the deduction reduces your taxable income within a single bracket. If a deduction pushes you below a bracket threshold, the savings can be higher than expected. Conversely, if you're near a phase-out threshold for certain credits or deductions, taking an additional deduction might cause you to lose a credit worth more than the tax saved. This is especially relevant with education credits and retirement contributions in the United States system. I learned this the hard way when a client deducted a large business expense that dropped them below the threshold for a smaller credit they were eligible for. The net result was worse by about two hundred dollars. Always model the full scenario, not just the bracket calculation. Standard deductions and itemized deductions represent another practical decision point. You take whichever is larger. Mathematically that's simple. The complexity comes from tracking itemized expenses properly. Medical expenses, charitable contributions, mortgage interest. Each has its own rules about what qualifies and what doesn't. The tax code doesn't reward approximate accounting. I've reviewed returns where people guessed at their itemized totals and came in under by a few hundred dollars. It seemed harmless until an audit flagged the discrepancy. The workaround was keeping a dedicated ledger throughout the year, not trying to reconstruct everything in April. For self-employed individuals, the math gets another layer. Self-employment tax covers Social Security and Medicare and is calculated separately from income tax. The rate is twelve point four percent on the first portion of net earnings and two point nine percent on the remainder. You also deduct half of this tax from your net earnings before calculating income tax. That deduction matters because it reduces your taxable income, which creates a feedback loop in the calculation. The order of operations is important here. Calculate self-employment tax first, take the deduction, then calculate income tax on the reduced amount.
Get the Full Details

A specific edge case I ran into involved foreign earned income exclusion. Someone working abroad could exclude up to a certain amount of foreign earnings from U.S. taxation. The mathematical interaction with the standard deduction is non-trivial. If you claim the foreign earned income exclusion, you cannot also claim the standard deduction. You have to itemize or use the exclusion, and the choice changes the bracket calculation for the remaining income. I built a small spreadsheet to handle this because the manual calculation was error-prone. The spreadsheet now runs the numbers in about two minutes versus the ten minutes it took me doing it by hand, and it catches the interdependency automatically. Capital gains introduce a different tax structure entirely. Short-term gains are taxed at ordinary income rates. Long-term gains use a separate schedule with different rates depending on income level. The crossover points between zero percent, fifteen percent, and twenty percent long-term rates shift annually with inflation adjustments. If you're calculating this by hand, you need the current year's thresholds. Using outdated numbers from a previous year's form will give you the wrong answer. I made this mistake once and overpaid by about one hundred and eighty dollars. The correction took six months to process. Here's the blunt truth about doing tax math well: precision beats speed. Rushing through bracket calculations will cost you more in corrections and potential penalties than any time you save. Spending twenty minutes double-checking your work is usually sufficient. Using a spreadsheet with clear cell references for each step makes verification faster. The alternative is accepting that errors are inevitable and dealing with them when the tax authority sends a notice, which takes considerably longer and often results in underpayment penalties.
When tax law changes, which happens every year, recalibrating your calculations requires updating every threshold and rate. This is tedious but necessary. I maintain a reference file with the current year's brackets and update it each January. Old calculations stay in a separate archive folder labeled with the year. Confusion between years is the most common source of mistakes in my experience, and it's entirely preventable with basic file organization. The mathematics of tax is fundamentally applied arithmetic with layered rules. The rules create the difficulty, not the math. Master the sequence: gross income, adjustments, deductions, taxable income, bracket application, credits, and final liability. Work through each step deliberately. Check your work against a second method if possible. That's essentially all there is to it.