What Actually Happens When You Close the Books
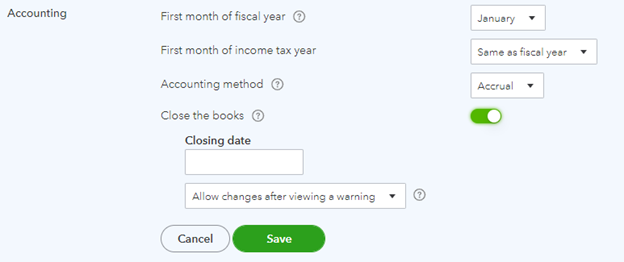
Most people treat year end closing in QuickBooks like it is a magical button you press and everything just works. It is not. You close the books to lock prior periods so nobody can go back and change transactions that should stay exactly as they were. The process creates a closing date, assigns a password, and moves your profit and loss into retained earnings for that fiscal year. That is the mechanics of it. Nothing more.I learned this the hard way back in 2016 when a bookkeeper I was working with went back three years and reclassified a bunch of vendor expenses to avoid a tax issue. The client thought nothing was wrong because QuickBooks still balanced. But the audit trail showed every edit. Once I started requiring closing dates on all client files, that problem disappeared. Now I set the date and password before the accountant even sees the file. The actual steps are straightforward if you already know where to look. Open your QuickBooks Desktop company file. Go to the Company menu at the top. Click on Set Closing Date. You will see a dialog box that asks for the date you want to close. Enter the last day of your fiscal year. Then set a password. Write that password down somewhere safe because once you confirm it, QuickBooks does not give you a backdoor. QuickBooks Pro, Pro Plus, and Enterprise editions all support this feature. QuickBooks Simple Start and Essentials do not have closing date functionality built in. If you are on one of those versions, you need to upgrade or use a workaround like making the file read only for prior periods. Most small business owners do not realize this limitation until they try to close the books and get stuck. I usually recommend upgrading to Accountant Edition or higher if closing dates matter to your workflow. The upgrade cost is less than the trouble of dealing with an unclosed file during an audit.
After you set the closing date, any transaction dated on or before that date becomes locked. Users who try to edit it will be prompted for the password. New transactions dated after the closing date remain editable without any special steps. This is important because it means your accountant can still do current period work while the prior year stays protected. The system does not require you to run any special reports before setting the date, but you should absolutely reconcile every account first. An unclosed reconciliation is the #1 reason closing dates get undone later. One edge case that bites people regularly involves inventory adjustments. If you use QuickBooks to track inventory and you have adjustment transactions in a closed period, you cannot edit them through the normal interface. The workaround is to go to the Accountant Tools menu, select Undo Closing Date, enter the password, make your changes, then reapply the closing date. This adds an entry to the audit report showing someone removed the lock. Auditors do not care that you had a good reason. They just want to see the undo action documented. I keep a simple log file outside of QuickBooks noting every time I remove and replace a closing date. It has saved me from explaining myself multiple times.
Common Mistakes That Wreck the Process
The biggest mistake I see is setting the closing date without first running a balance sheet review. If your accounts do not balance, the closing process will still complete, but you are locking in errors. Check that your assets equal liabilities plus equity. Verify that your retained earnings match what you expect from the prior year. Run the trial balance report. These three checks take about five minutes and prevent hours of troubleshooting later. Another issue involves payroll. If you run payroll through QuickBooks Payroll, the system automatically creates adjusting entries at the end of each pay period. These entries sometimes appear in periods that should be closed. The fix is to make sure all payroll liability accounts are reconciled before you set the closing date. Unpaid wages, tax liabilities, and benefit deductions all need to clear to zero or match your liability account balances. If they do not, you will have a discrepancy that looks like fraud to anyone reviewing the books later. QuickBooks Online users face a different problem. The web version does not have a traditional closing date lock. Instead, you use the closing lock feature available through the Accountant tab. It works similarly but has fewer controls. You cannot set different passwords for different users in the same way. You also cannot undo the closure without involving an accountant user. This limitation is why many small businesses with QuickBooks Online switch to desktop or use a third party tool when they need tighter control over their year end process.
Get the Full Details
The audit trail report is your safety net. After closing, run Report > Accountant > Audit Changes. Review every transaction made in the closed period. If you see edits that should not be there, investigate immediately. The report shows who made the change, what changed, and when. This information is critical if you ever need to defend your books to an auditor or lender. Most people never look at this report until something goes wrong. I check it within 24 hours of every closing date being applied.
When QuickBooks Is Not the Right Tool
QuickBooks handles basic year end closing well for small businesses with straightforward operations. If you run a multi entity company, use complex inventory tracking, or have foreign currency transactions, the built in closing process may not cover all your needs. In those cases, I recommend using a separate reconciliation tool like SharkTank or Acountancy software alongside QuickBooks. Some firms also export their data to Excel or Access and maintain a parallel set of closing records. This is extra work but provides a backup that QuickBooks alone does not offer. The real value of closing your books is not the mechanics. It is the discipline it forces on your record keeping. When periods are locked, you stop making adjustments that should have been caught earlier. Your trial balance stays cleaner. Your accountant spends less time hunting for errors and more time adding value. That is the practical outcome most people miss when they rush through this step at the end of the year. If you are doing this for the first time, budget two to three hours for a clean file. Files with unresolved discrepancies can take all day. Keep a checklist on your desk. Reconcile. Review. Close. Verify. Repeat the verification step. Those four words are all you really need to remember once you have done this a few times.