The actual mechanics behind doubling capital
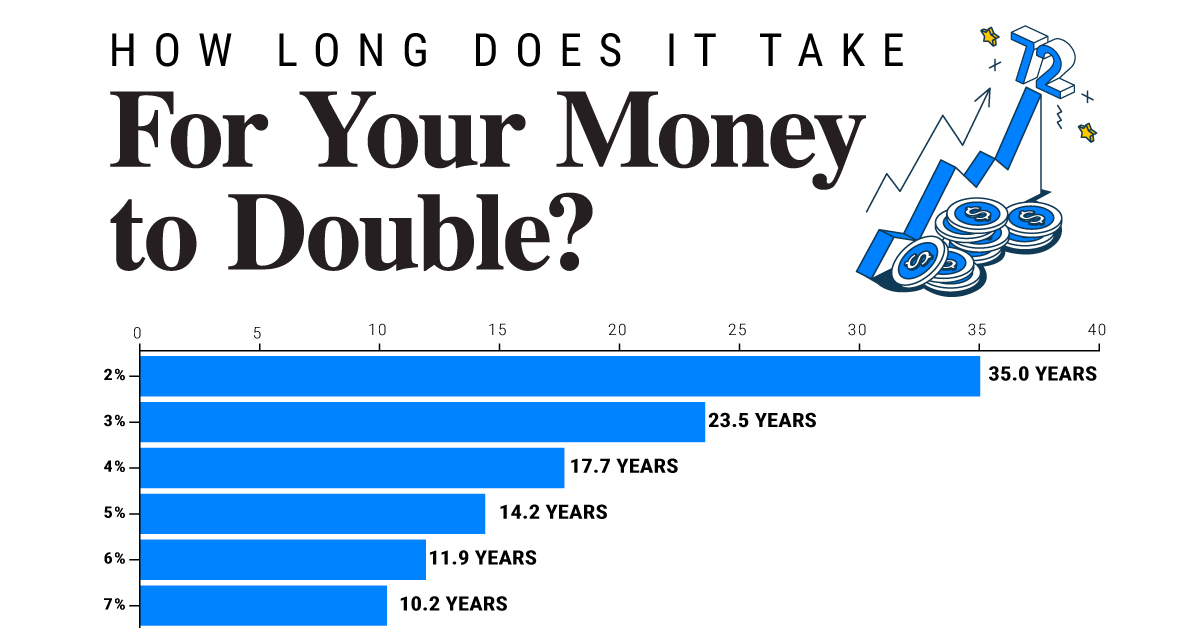
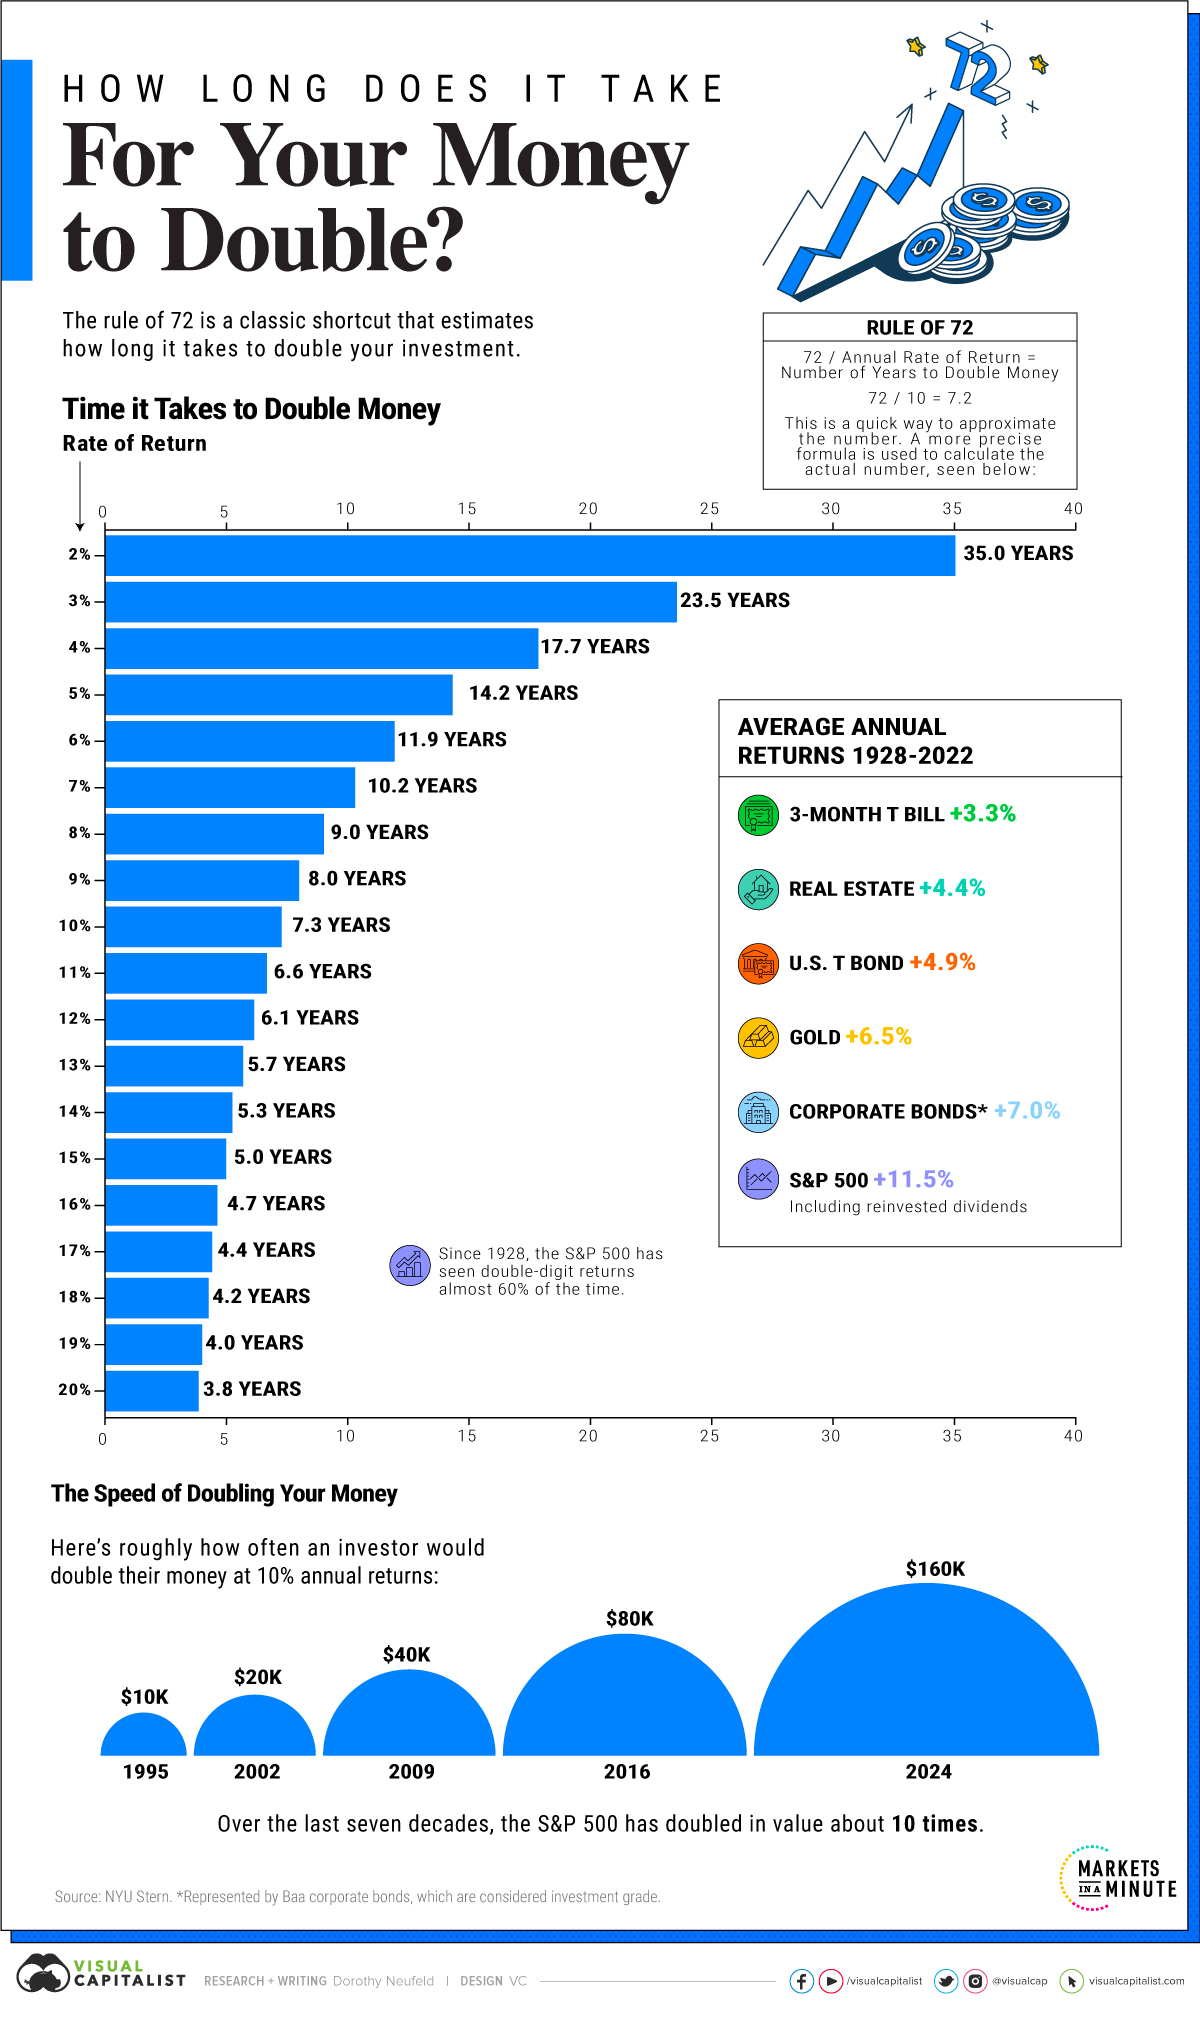
Most people think about doubling their money in terms of get-rich-quick schemes or lottery tickets. That is not the only way. It is also not the realistic way. The actual mechanism involves time, compound growth, and a strategy that does not involve day trading or gambling. Let me be straightforward about this. Doubling your money is mathematically simple but psychologically difficult. The rule of 72 tells you that dividing 72 by your annual return rate gives you the approximate number of years it takes to double. At a 7% annual return, that is roughly 10 years. At 10%, about 7 years. That is the entire calculation. The hard part is staying consistent for a decade or more without panic-selling during downturns.How To Double Your Money Without Losing Sleep
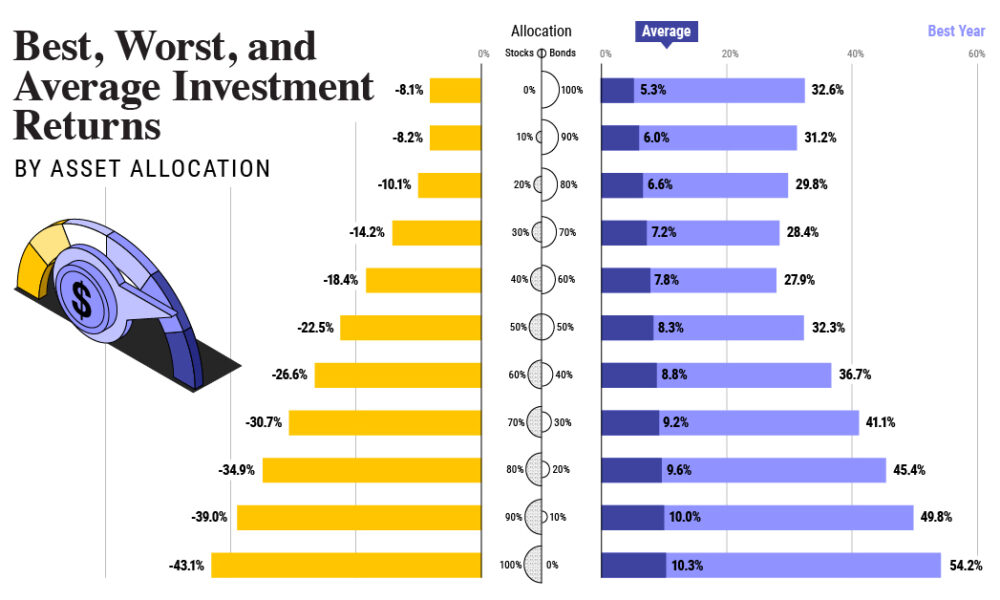
The most reliable path is low-cost index fund investing. Not because it is exciting, but because it is boring and it works. A total stock market index fund or an S&P 500 fund historically returns around 10% annually before inflation, give or take depending on the decade. You buy shares, you stop checking your portfolio every week, and you add money regularly. Dollar-cost averaging removes the timing problem entirely. I have watched people try to beat this system with individual stock picks, crypto, options, and various "proven strategies" they found on forums. I lost money on all of them at some point. The index fund approach is what kept me solvent. It is not glamorous. It does not feel like a win when you are sitting on a 20% drawdown in 2022. But it produces results over enough time. Here is something most beginner investors miss. The order of your returns matters more than the average return. This is called sequence of returns risk. If you lose 50% in year one and gain 50% in year two, you are still down 25%. Most people understand the math of averages but not the math of sequences. This is why starting early and maintaining contributions through volatility is critical. Pulling out during a bad year locks in losses and destroys the compounding effect you are counting on. Another practical detail nobody emphasizes enough. Tax efficiency changes everything. A taxable brokerage account and a tax-advantaged account like a 401k or IRA will produce very different outcomes over 10 years, even with identical investment choices. The tax drag on capital gains distributions and dividend reinvestment in a regular account can cost you well over a percentage point annually. Use the tax-advantaged accounts first before touching a regular brokerage account. I ran into a specific edge-case once where someone had a high-yield savings account balance of about $8,000 sitting idle while also carrying $12,000 in credit card debt at 22% APR. They were trying to invest in individual stocks with the savings. The math was insulting. They were earning roughly 4% on the savings and losing 22% on the debt. The fastest way to double their financial position was not investing at all. Paying off the debt gave them an immediate, guaranteed 22% return. That is better than any stock market return you will find. I recommend everyone calculate their net interest spread before putting money into any investment vehicle.There are genuine limitations to this approach. You need time. If you need the money in less than five years, the stock market is a gamble, not a strategy. You need discipline. Markets will crash. They will go years without meaningful gains. You will see friends get rich on a meme stock or a crypto trade and it will feel unfair. Staying the course during those periods is the actual barrier, not the investing itself. You also need capital to start. Doubling $100 is mathematically identical to doubling $100,000, but the impact on your life is completely different. Consistent monthly contributions matter far more than chasing higher returns. If you cannot commit to a ten-year horizon, consider a ladder of short-term Treasury securities or certificates of deposit. These do not double your money quickly, but they also do not expose you to market risk. For some people, that trade-off is the only rational choice.