Getting Your Business Credit Started
Most people approach this backwards. They worry about the credit score before they worry about the structure. That's why it fails for them. Here's what actually needs to happen, in order, from someone who's watched too many business owners waste six months trying to jump steps.
How To Establish Business Credit For The First Time
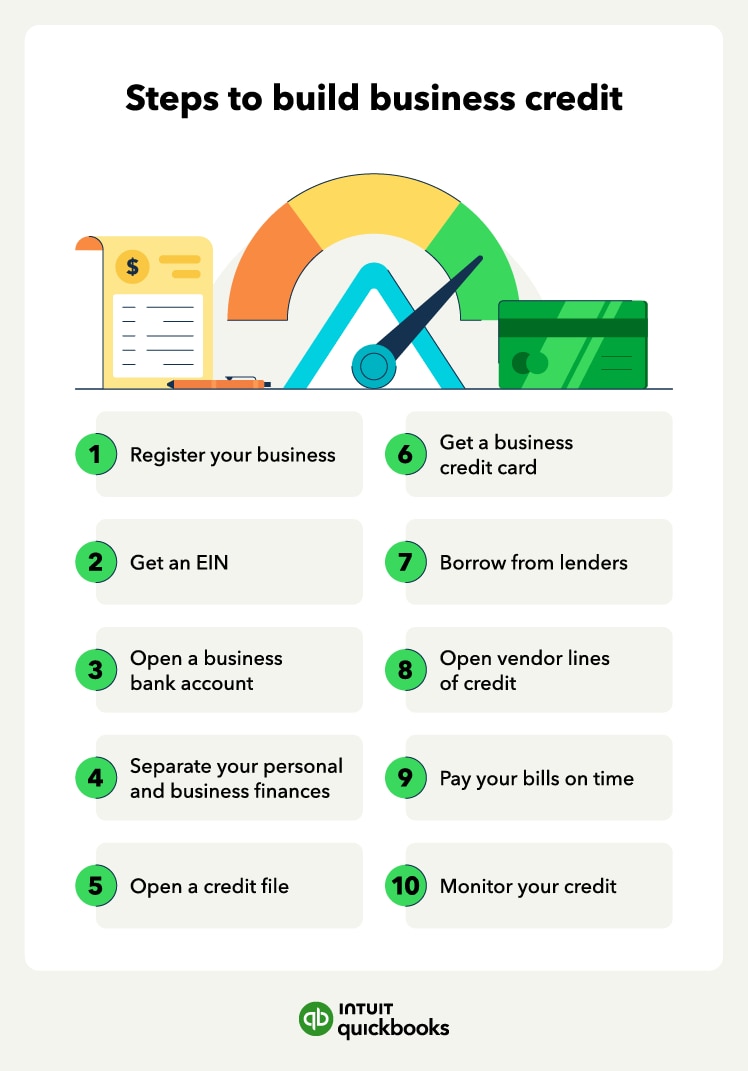
Step one is making sure your business exists on paper as something separate from you personally. This means you have an EIN from the IRS, not just a DBA filing. A sole proprietorship with a business bank account does not count in most creditor systems. You need an entity that can be distinguished from a natural person. Get your business registered with the major data aggregators. Dun & Bradstreet, Equifax Business, and Experian Business each have their own processes. D&B is the one everyone uses, and getting your D-U-N-S number is the bottleneck most people hit. It should take 30 days, but if you call and provide all documentation upfront it can be faster. I once had a client whose D&B number sat dormant for four months because his legal name on the application didn't match his state filing by one character. He'd typed "LLC" without the period in one field and with it in another. Took three phone calls and a scanned copy of his Articles of Organization to fix. After the D&B number comes your Experian Boost for business and your Equifax Business credit file. These are separate. Do not assume one covers the other.
Next you open a business bank account. Not a personal account with "business" in the name. A true business checking account under your EIN. This is where people get sloppy and then wonder why vendors won't extend terms. A bank account that isn't linked to your personal checking in any way carries more weight than you'd think. Some creditors flag accounts that receive regular transfers from a sole proprietor's personal account as a sign the business isn't operationally independent. Then you apply for a Net-30 account. This is the entry point. Companies like Uline, Grainger, Summa Office, and Denver Tools offer trade credit with 30-day terms and report to the business credit bureaus. The key is that you have to use it and pay it off before the due date. Just once. A single Net-30 account that was paid on time and then closed quickly will get you a basic business credit profile. It won't be impressive, but it will exist. Here's something people miss. The Net-30 account doesn't need to be for a large purchase. I've seen business owners buy $200 in office supplies, pay it off in 14 days, and then move on. That's sufficient. The amount doesn't matter as much as the consistent reporting. What matters is that the vendor reports to the bureau consistently. Some smaller Net-30 providers don't report at all. Check before you apply. I lost a client three months of progress once because he opened five Net-30 accounts without verifying which ones actually reported to D&B. Four of them didn't.
Get the Full Details
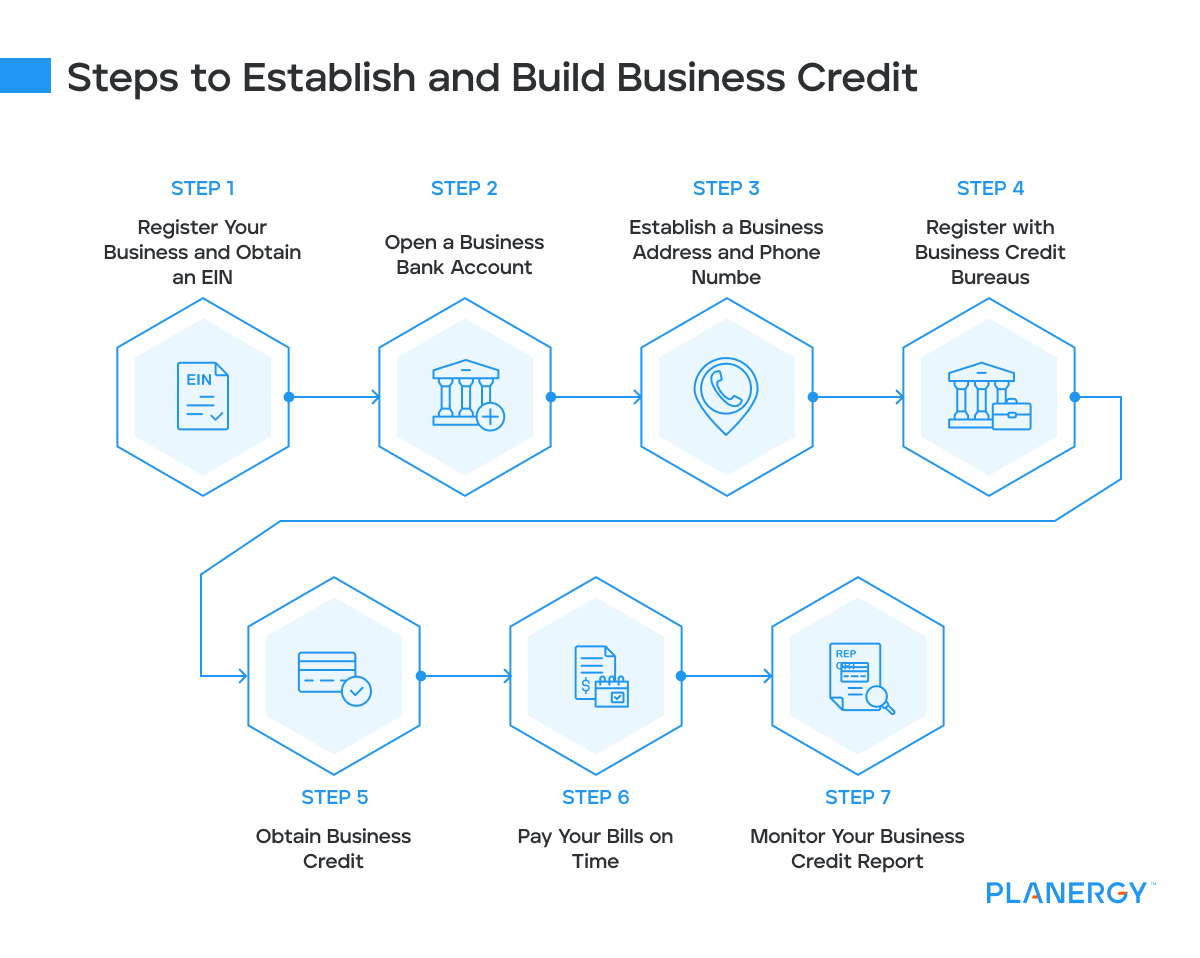
Once you have at least two or three Net-30 accounts with clean payment history, you can move to a store card or a small business credit card that reports to business credit bureaus. Citi, Chase, and Bank of America all have business cards that report. Some report to all three bureaus, some only report to one. Again, check before you apply. This is where the fine print lives and most people ignore it.
The Part Nobody Talks About
Business credit builds slower than personal credit, and the reasons are structural. Lenders see business failures at a much higher rate than personal bankruptcies. They price accordingly. Your first year of business credit will likely show minimal borrowing capacity regardless of how perfectly you manage your accounts. This is normal and not a reflection of your competence. The second thing people don't understand is that your personal credit score still matters more than you'd like to admit in the early stages. Most small business lenders pull a personal credit check alongside the business file. If your personal score is below 650, you're going to face resistance on credit applications even if your business credit is pristine. It's an unfair system but it's the one you're working in. I had a client who built a perfect business credit profile in nine months — three Net-30 accounts, a store card, a small credit card, all paid on time, all reporting. He applied for a $50,000 line of credit and was denied. Not because of his business credit. His personal FICO was 612. The lender didn't even look past the personal score. He ended up going with a community credit union that weighed the business cash flow more heavily than the personal credit number. Took him six additional months of relationship-building with the credit union before they approved him. Worth it in the end but it completely changed his timeline.
Common Mistakes That Set You Back
Applying for too many accounts at once. Each hard inquiry on your personal credit and each new business credit application creates a signal that you're desperate for credit. Vendors can see this. They interpret it as risk. Space your applications out by at least 30 days between each one. Using your business credit for personal expenses. Even once. This muddies the separation between you and the entity, and some creditors flag mixed-use accounts. Keep the finances clean from day one. Missing a single payment in the first year. Late payments on business credit accounts stay on your business file for seven years. Your personal credit gets more forgiveness. Your business credit does not. Set up automatic payments or calendar reminders. Both. I know it feels excessive but the cost of one late payment is disproportionately high when you're building from zero.

What to Expect Timeline-Wise
Months one through three: EIN, business registration, D-U-N-S number, business bank account, first Net-30 account opened and used. You'll have a thin file at this point. Months three through six: Second and third Net-30 accounts, first store card or small business credit card, consistent on-time payments reported to all three bureaus. Your business credit score should be visible now, probably in the low-to-mid range depending on the scoring model. Months six through twelve: You should have enough activity to qualify for a small business credit card with a meaningful limit, possibly a secured business card if your personal credit is dragging you down. Some vendors will begin offering you Net-60 or Net-90 terms instead of Net-30. This is a milestone. It means they're starting to trust the business as a creditworthy entity rather than just a pass-through for your personal spending.
Year two onwards: This is where things start moving faster. Higher limits, better terms, access to business loans and lines of credit. The compounding effect of clean payment history becomes real. If you've maintained everything correctly, you should be looking at credit limits in the $10,000 to $25,000 range by month 18 to 24, depending on your industry and revenue.
When It Doesn't Work
If your business has no revenue, business credit will remain thin regardless of how many Net-30 accounts you open. Creditors want to see that money is flowing through the business. A hobby or side project without actual sales isn't going to generate a strong business credit file. Get revenue first, then optimize the credit side. If you have significant personal debt relative to your income, your ability to establish business credit will be constrained by your personal credit profile. No amount of perfect business payment behavior will fully offset a 560 personal FICO score in the eyes of traditional lenders. In that case, focus on fixing your personal credit in parallel while you build the business file. They reinforce each other over time but the personal number is the gatekeeper in the early stages. Some industries are simply harder than others. High-risk businesses — gambling adjacent, adult entertainment, certain types of consulting — will find that major creditors refuse to report to business bureaus or refuse to extend credit at all. This isn't theoretical. I've seen it happen repeatedly. If your industry falls into a restricted category, you'll need to work with specialty lenders or credit builders that cater to those sectors, and the terms will be worse. Plan accordingly.