Understanding the Structure of Finance Journal Questions
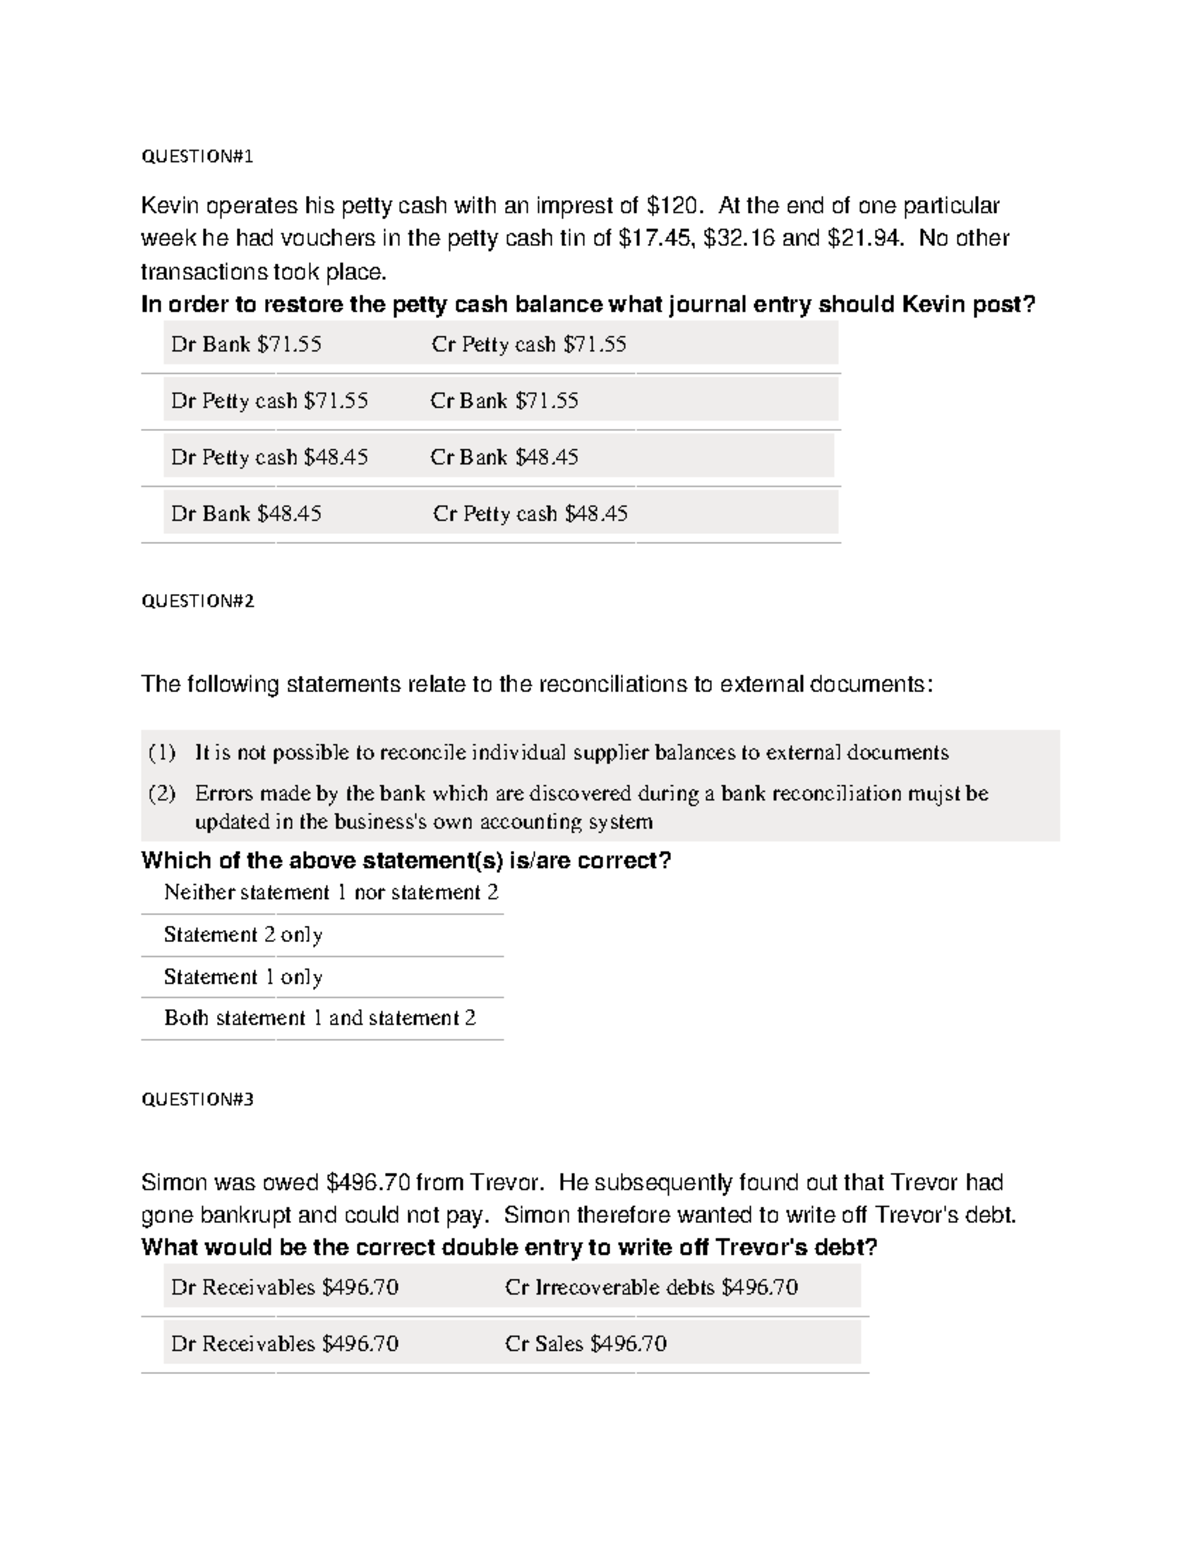
Finance journal questions typically present a scenario involving a business transaction and ask you to record the appropriate journal entries. The format varies depending on whether you are dealing with introductory accounting coursework or advanced financial management assignments, but the core demand is always the same: show you understand which accounts are affected and in what direction. Most journal questions follow a pattern. You are given a transaction description, sometimes with additional data like dates, amounts, and account balances, and you need to produce debit and credit entries that keep the accounting equation in balance. The tricky part is that not all questions are this straightforward.
How To Finance Journal Questions in Academic and Professional Contexts
When students and early-career professionals ask how to approach these questions, the answer comes down to methodical breakdown rather than intuition. I have seen people lose points on assignments not because they did not understand the concept, but because they rushed through the entry format or misidentified the account classification. Here is what actually works. Read the full transaction before touching a pen or keyboard. Identify the accounts involved. Determine whether each account increases or decreases. Apply the debit-credit rules. Record the entry. Then double-check that total debits equal total credits. The accounts you will encounter most often include cash, accounts receivable, accounts payable, inventory, prepaid expenses, accrued liabilities, revenue accounts, and various equity accounts. Each has a normal balance direction. Cash and assets increase with debits. Liabilities and equity increase with credits. Revenue increases equity, so it follows the credit rule. Expenses decrease equity, so they follow the debit rule.
Recording Standard Transaction Types
Most finance journal questions draw from a limited set of transaction categories. Knowing these by heart saves significant time. Cash transactions involve the immediate exchange of money. When a company receives payment from a customer, you debit cash and credit the relevant revenue or receivable account. When it pays a supplier, you debit the payable or expense and credit cash. These are the simplest entries and the ones where people make careless mistakes under time pressure. Accrual transactions require you to record revenue or expenses before cash changes hands. An accrued expense like wages earned by employees but not yet paid requires a debit to wage expense and a credit to wages payable. An accrued revenue like services performed but not yet invoiced requires a debit to accounts receivable and a credit to revenue. These entries are where most students stumble because the cash element is missing from the scenario.
Get the Full Details
Adjusting entries appear at the end of an accounting period and reconcile the books to actual conditions. Depreciation of equipment, amortization of intangible assets, and the expiration of prepaid items all fall into this category. A typical depreciation entry debits depreciation expense and credits accumulated depreciation. Note that accumulated depreciation is a contra-asset account, which means it carries a credit balance and reduces the net book value of the related asset.
The Analytical Layer: Answering the Questions Attached to Journal Entries
Modern finance journal questions rarely stop at the entry. They usually ask follow-up questions that test whether you actually understand the impact of the transaction on the financial statements. You might be asked to calculate the effect on net income, prepare a partial balance sheet, or explain the rationale behind a particular account classification. This is where showing your work matters. State which financial statement each account appears on. Mention the direction of the change. Connect the journal entry to the larger picture. For example, if a question asks about the impact of recording an accrued expense on the current ratio, you need to recognize that current liabilities increase while current assets remain unchanged, which lowers the ratio. Writing out that chain of logic is what separates a complete answer from an incomplete one.
Common Pitfalls and How to Avoid Them
I have reviewed enough student work and entry-level professional submissions to know where people consistently go wrong. The most frequent error is mixing up the debit and credit sides of an entry. This usually happens when someone confuses the normal balance of an account. If you are unsure whether an account normally carries a debit or credit balance, look it up immediately rather than guessing. Another common mistake is failing to adjust for depreciation or amortization when the question provides asset cost, useful life, and residual value. These numbers are not decorative. They are there for a reason. Use them. A third pitfall involves compound entries. Some transactions affect more than two accounts. Recording a purchase of equipment with a partial cash payment and a note payable requires one debit to the equipment account and two credits to cash and notes payable. Do not split this into separate journal entries unless the question explicitly asks you to.

A Realistic Edge Case That Trips People Up
Here is a specific problem I encountered repeatedly when working with finance journal questions involving lease accounting under ASC 842. The scenario described a company entering into a three-year operating lease with monthly payments of $2,500 and an implicit discount rate of 6 percent. The question asked for the initial journal entry and the first monthly entry. Most people I worked with treated it like an old operating lease and recorded nothing at inception. That was the wrong approach under the current standard. The correct initial entry required recognizing a right-of-use asset and a lease liability at the present value of the lease payments, which I calculated as approximately $69,500 using the annuity factor for three years at 6 percent. The monthly entry then required splitting the payment into interest expense and a reduction of the lease liability, with the remainder amortizing the right-of-use asset. The workaround I used was to build a quick amortization schedule in a spreadsheet before writing any entries. This forced me to calculate the interest portion for each period correctly and made sure the liability balance reached zero at the end of the lease term. Without that schedule, the numbers never reconciled.
Tools and Resources for Practice
There is no substitute for repeated practice, but using the right tools accelerates the process. Spreadsheet software is essential for building amortization tables, depreciation schedules, and trial balance tests. Most textbook platforms now include interactive journal entry exercises with instant feedback, which is useful for catching pattern mistakes early. If you are preparing for a certification exam like the CPA or CFA, focus on past exam questions that require journal entries. The question writers tend to recycle certain transaction types and traps. Recognizing the trap before it traps you is a skill that develops through volume of practice, not through passive reading.
Limitations of This Approach
Journal questions test mechanical understanding and basic analytical reasoning. They do not test judgment about whether a particular accounting treatment is the best choice in a real business environment. In practice, accountants often face ambiguity where multiple treatments are defensible. Exams and textbook problems rarely reflect that. They present a single correct answer and expect you to arrive at it using standard rules. This means that mastering finance journal questions will make you better at tests and foundational work, but it will not fully prepare you for the gray areas you will encounter in professional practice. For that, you need experience with real financial statements, regulatory guidance, and client situations. No amount of journal question practice substitutes for that.

Final Notes on Efficiency
The difference between a slow and a fast approach to finance journal questions usually comes down to preparation. If you have memorized the debit-credit rules for every major account type and you can quickly identify transaction patterns, you can complete a standard set of journal questions in ten to fifteen minutes. If you are constantly pausing to look up basic rules or second-guessing account classifications, the same work might take an hour or more. Build your reference material once. Keep a clean summary sheet of account normal balances, common adjusting entry templates, and the key formulas for present value and annuity calculations. Update it as you learn new topic areas. Refer to it during practice until the information moves into long-term memory. Then you can focus your energy on the harder parts of each question instead of spending it on fundamentals.