Understanding Inflection Points Without the Textbook Fluff
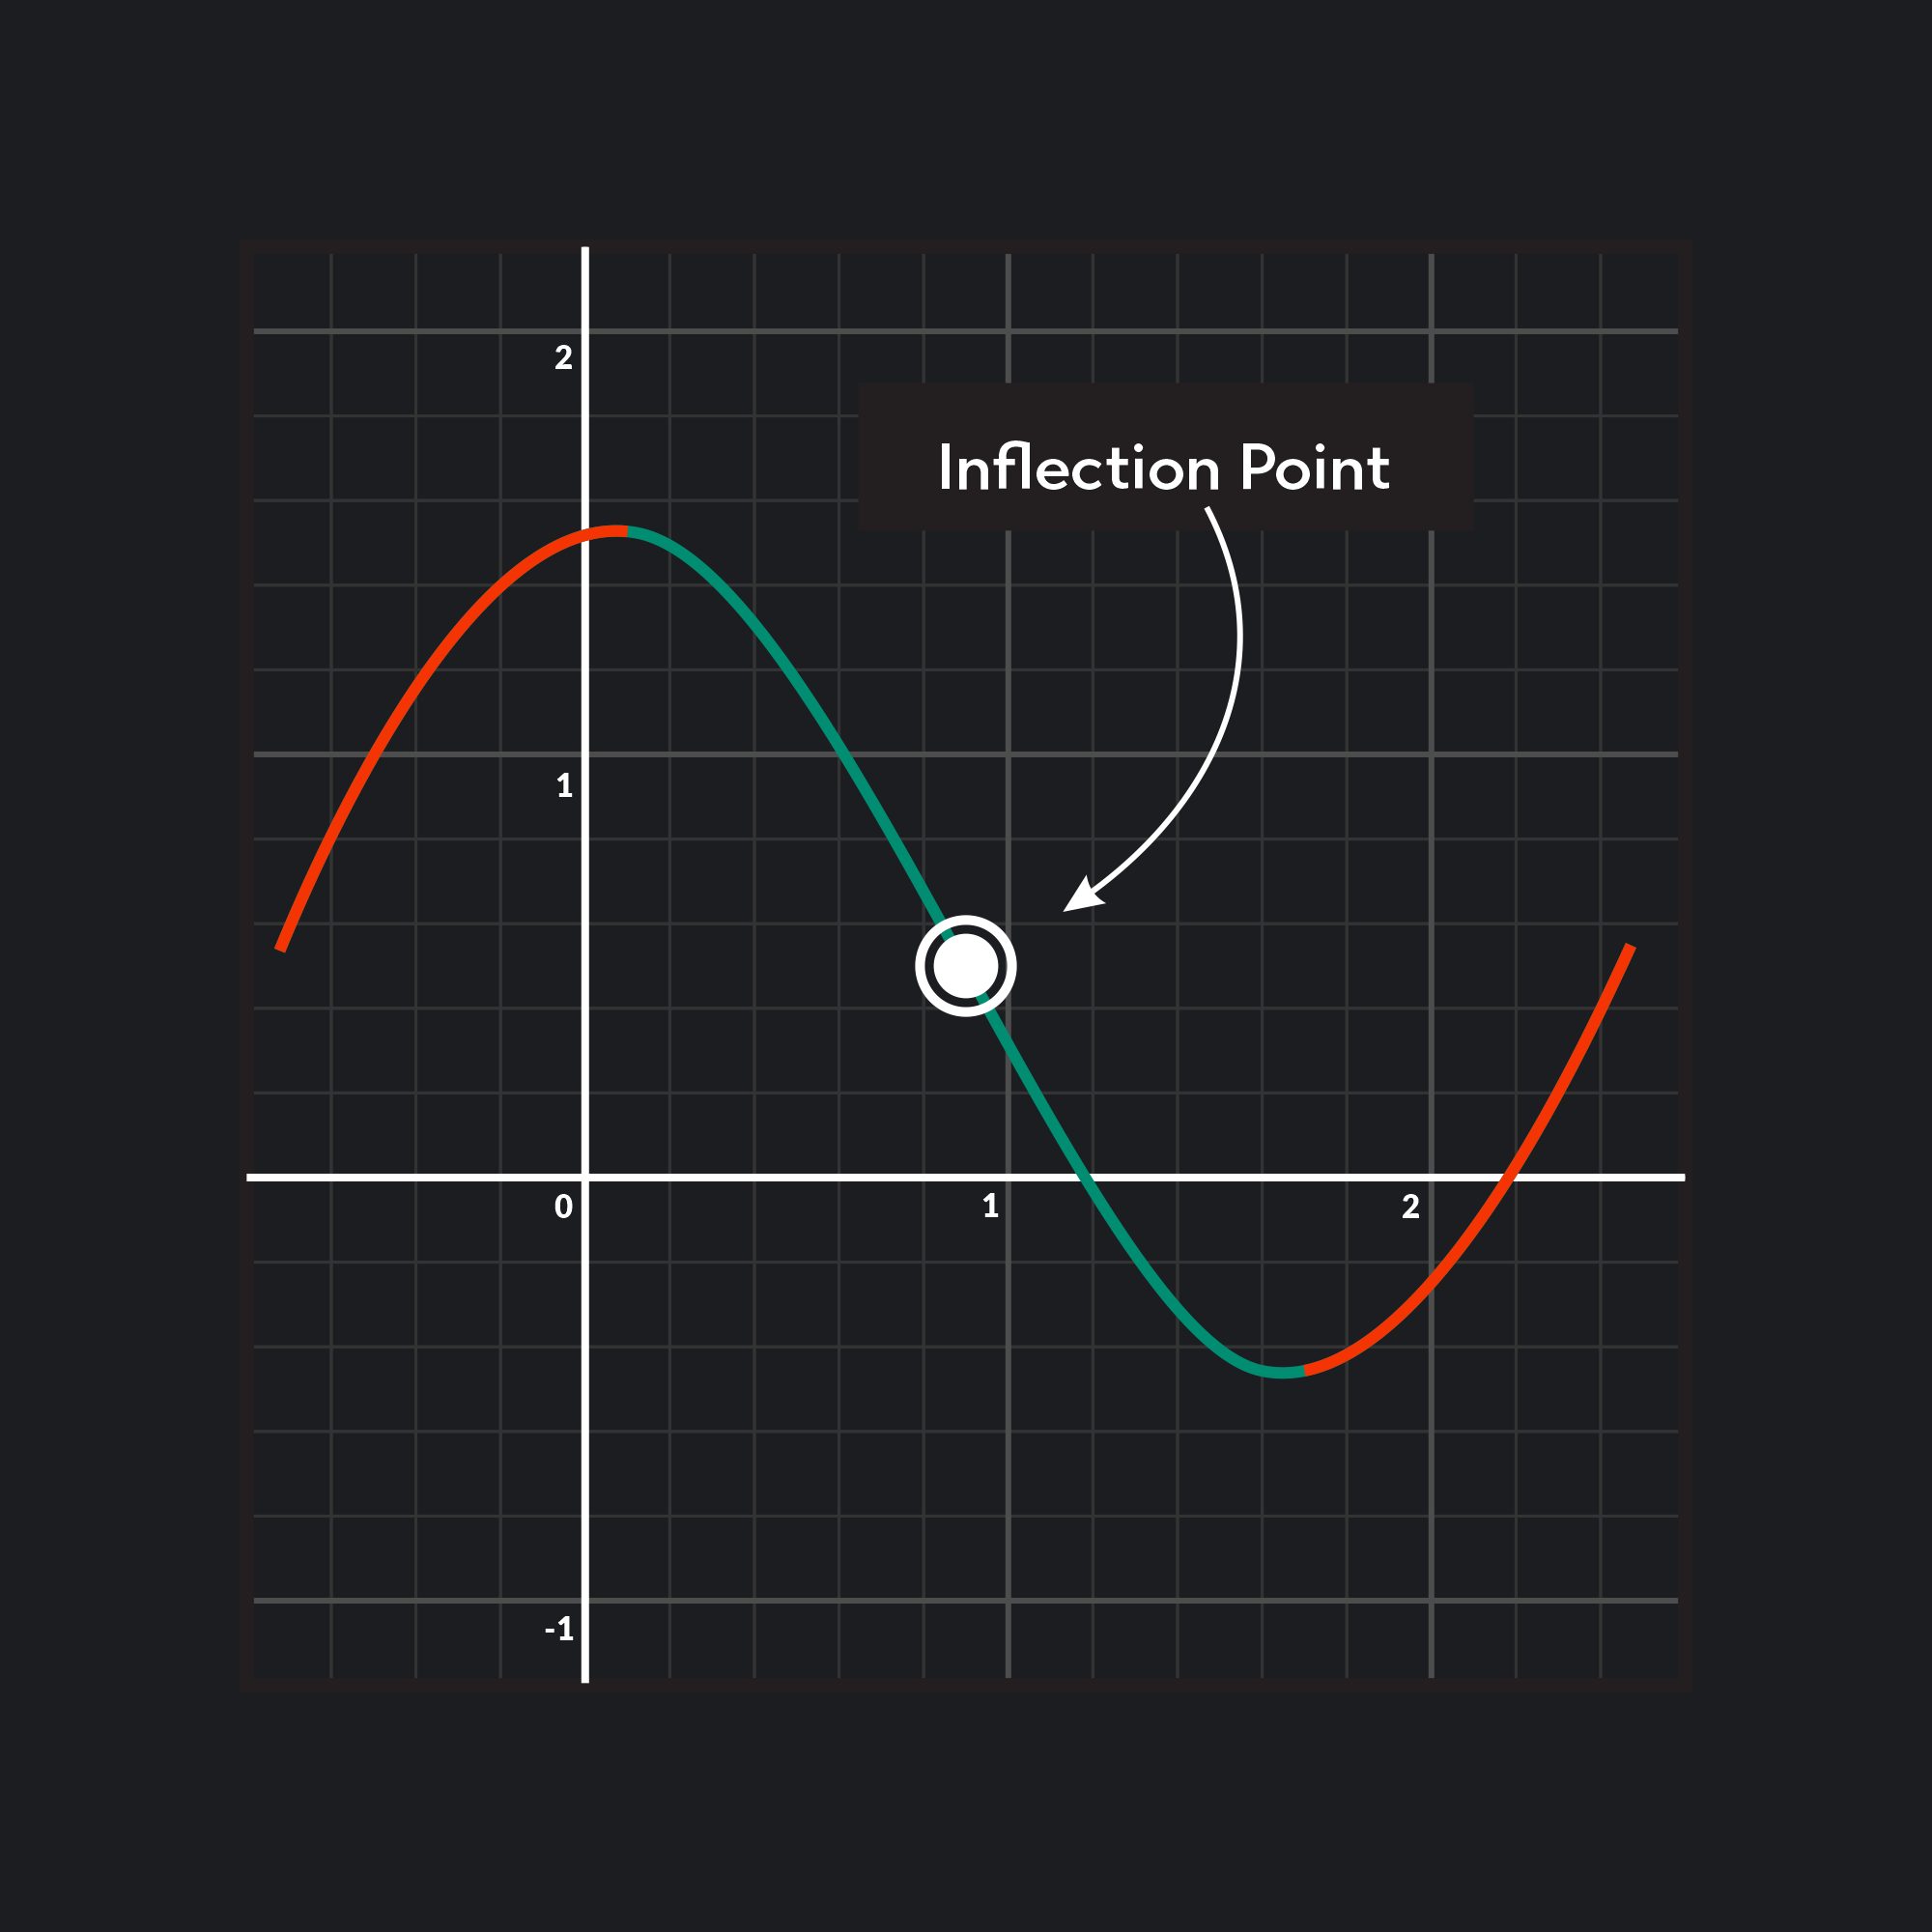
An inflection point is where a function's concavity switches. That's it. In practice, you find them by looking at the second derivative, but the real-world situation is messier than the calculus textbook version makes it look. Here's how I actually handle it. The standard procedure: take the second derivative of your function, set it equal to zero, solve for x, then verify that the second derivative actually changes sign at those values. Most people stop there and call it a day, which is fine for homework problems but gets you into trouble with real data. Sign change is the critical part. A point where f''(x) = 0 isn't automatically an inflection point. Consider f(x) = x^4. The second derivative is 12x^2, which equals zero at x = 0, but the function stays concave up on both sides. No inflection point there. You have to check what happens on either side of the candidate value, not just that the second derivative vanishes.
I ran into a case last year working with a logistic growth curve fitted to clinical trial data where the model had a second derivative that approached zero but never cleanly crossed it due to the way the parameters were constrained. The inflection point in the original theoretical model was well-defined, but after fitting, the curvature flattens near the transition rather than reversing sharply. What I ended up doing was checking the third derivative to see whether the second derivative had a stationary point or an actual root. Where the third derivative was nonzero at the candidate x value, it confirmed a genuine sign crossing. Where the third derivative was also zero, I flagged it as an indeterminate region and reported a range rather than a point estimate. There's also the issue of second derivatives being undefined at a point while the concavity still switches. Cusp-type behavior or absolute value features can produce inflection points where f'' doesn't exist at all. You have to check those separately by examining the sign of the second derivative in neighborhoods around the point, even if you can't evaluate it exactly at the point. For numerical data where you don't have an explicit function, the whole process changes. You can't just differentiate. I use a Savitzky-Golay filter to smooth the data before computing derivatives numerically, then look for zero crossings in the smoothed second derivative trace. The filter width matters enormously here. Too narrow and noise dominates. Too wide and you wash out genuine features. A window of about 10-15 percent of your total data range is usually a reasonable starting point, but you'll need to inspect the results to confirm nothing meaningful got filtered out.
One more thing most people miss: inflection points don't require the first derivative to be zero. A point of inflection with a nonzero slope is perfectly normal and actually more common in applied work. The function just needs to cross its own tangent line in a way that flips concavity. That's the geometric definition, and it applies regardless of whether you're doing symbolic or numerical work. If your function involves piecewise definitions or absolute values, treat each piece separately and then check the boundary points individually. The second derivative test doesn't carry across piecewise boundaries automatically, and that's where false negatives hide.
Get the Full Details

When the Method Fails
Inflection point detection breaks down cleanly in two scenarios. First, noisy experimental data without enough resolution to resolve the curvature change. If your sampling interval is too coarse relative to the feature size, you might completely miss the sign flip. Second, flat regions where the second derivative hovers around zero for an extended interval rather than crossing it. In those cases, reporting a single x value is misleading. You're better off describing the region as approximately flat in curvature and noting the limits within which the inflection could plausibly lie.