The Math Nobody Warns You About
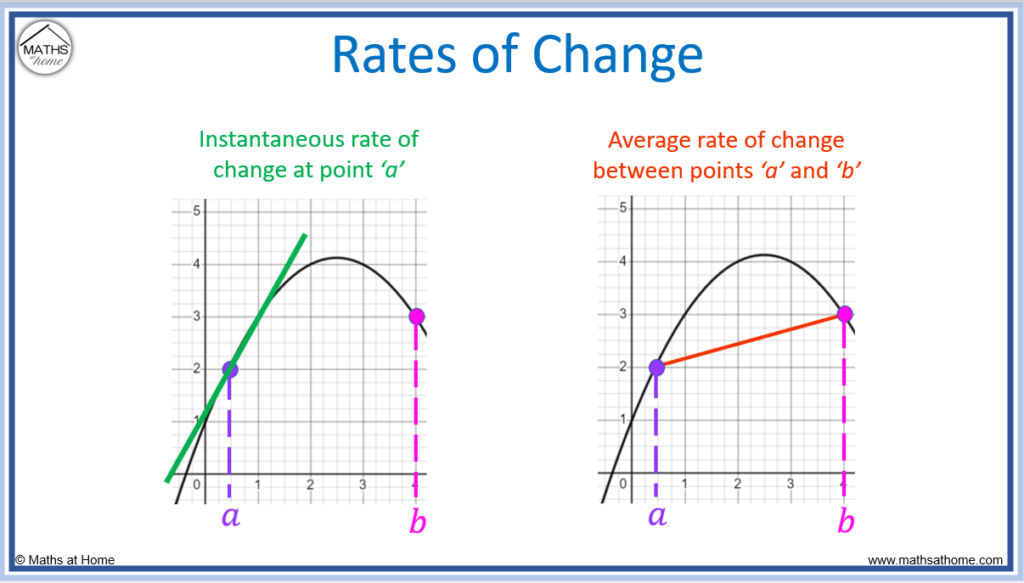
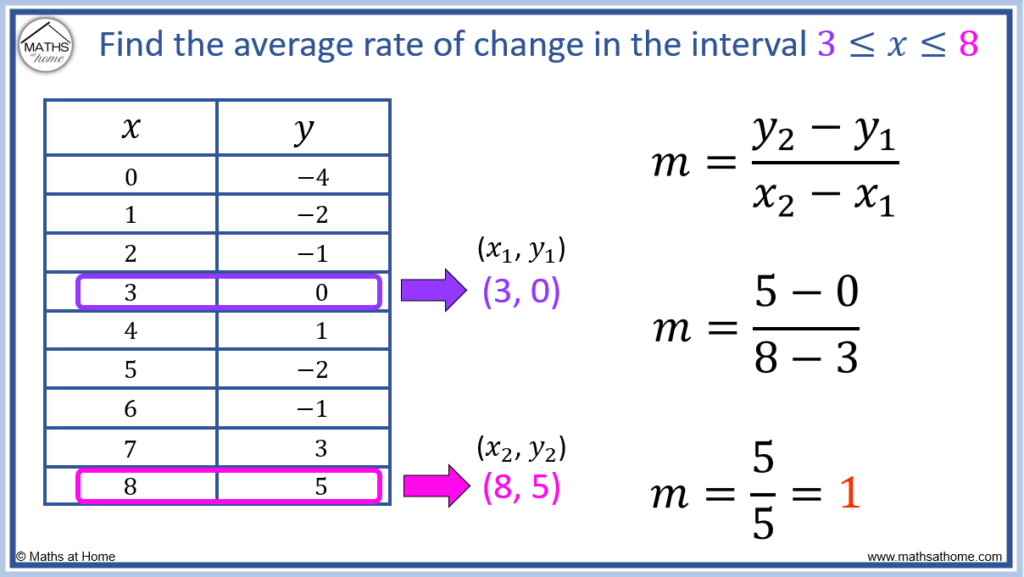
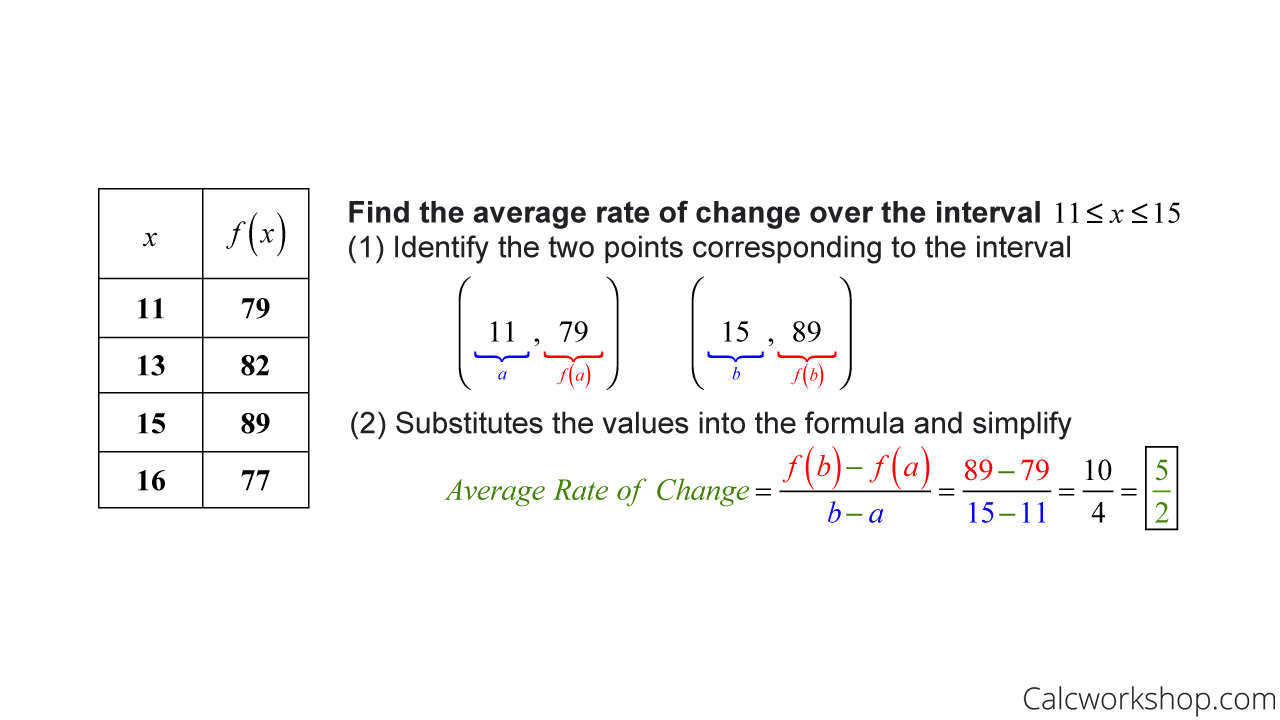
Rate of change sounds simple until you're dealing with real data and the numbers don't cooperate. The basic idea is straightforward — you're measuring how one value shifts relative to another. But the details matter more than most tutorials let on. I've seen people mess this up repeatedly because they skip the setup work.The standard formula is y / x, where you take the difference in your output values and divide by the difference in your input values. If your stock portfolio went from $10,000 to $11,500 over six months, the rate of change is 1,500 divided by 6, which gives you $250 per month. That's it. The calculation part isn't where people get stuck. Find Rate Of Change starts with picking your two data points and making sure they're measured consistently. I once worked with a team tracking conversion rates across three marketing channels. They plugged raw click counts into the formula without normalizing for traffic volume first. Their "rate of change" was completely meaningless because a channel getting ten thousand visits versus five hundred makes a huge difference in what the numbers actually represent. We ended up calculating percentage changes relative to baseline visits instead. Took about twenty minutes to restructure the spreadsheet once we caught the issue. When you're working with continuous data rather than discrete points, things shift. A derivative is really just the rate of change at an exact instant, found by taking the limit as your two points get infinitely close together. If you have a function like f(x) = 3x² + 2x, the derivative is f'(x) = 6x + 2. At x = 4, your instantaneous rate of change is 26. This matters when you're dealing with things like velocity or acceleration where the rate isn't constant.
One thing most guides don't mention is that rate of change can be positive, negative, or zero, and each tells a different story. A negative rate of change doesn't automatically mean failure. If you're measuring the decay rate of a medication in someone's bloodstream, you want that number to be negative. Context is everything here. I spent weeks debugging what looked like a broken model before realizing the negative sign was actually correct for what we were measuring. The model was fine. Our expectation was wrong.
Where People Go Wrong
The biggest pitfall I see is assuming linearity. Rate of change over one interval tells you nothing about what happens in another interval unless the relationship is actually linear. If you're looking at population growth, compound interest, or anything biological, the rate itself changes over time. Taking a single two-point calculation and projecting it forward will give you wildly incorrect predictions. You need either a differential equation or a series of small calculations across shorter intervals. Another issue is confusing average rate of change with instantaneous rate of change. The average over a year doesn't tell you what happened in any given month. If revenue doubled from January to December, the average rate of change suggests steady growth. But if all that growth happened in November and December, your average paints a completely misleading picture. Check whether your data is spread evenly or clustered. Units matter more than they should. Rate of change always carries units of "output per input." If you're measuring temperature change over time, your rate is degrees per hour, not just degrees. I've seen reports where the rate was stated without units, making it impossible to compare against other data or verify against expectations. Always write out the full units when you calculate.
Get the Full Details
Edge Cases That Break Standard Approaches
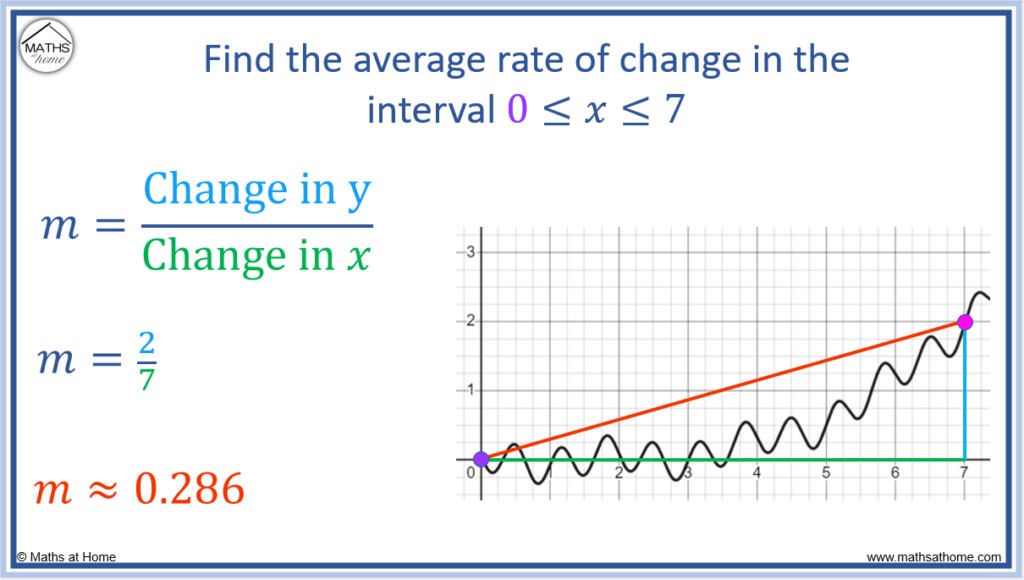
Discontinuous data is where the standard formula starts falling apart. If your measurements jump around or have gaps, averaging between distant points smooths over important behavior. I dealt with a dataset tracking equipment failure rates where sensors went offline intermittently. The standard rate of change between the last working reading and the next one suggested gradual degradation. In reality, the equipment was holding steady until it suddenly failed. Filling gaps with interpolation created false confidence in a trend that didn't exist. What actually worked was switching to a piecewise approach, calculating rates only between consecutive valid readings and flagging any gaps larger than a threshold as unreliable. Non-differentiable points are another headache. Absolute value functions, sharp corners, or data with sudden jumps don't have a well-defined instantaneous rate of change at certain points. If you're using numerical methods to approximate derivatives, your results will be unstable near these points. The workaround is usually to smooth the data first with a moving average or spline fit, then calculate. You lose some precision but gain stability. Sometimes that tradeoff is worth it. Scaling is also a practical concern. When your input variable spans a huge range while your output changes only slightly, the rate of change becomes a tiny decimal that's hard to work with. Logarithmic transforms can help here, or simply rescaling your input. I remember analyzing a chemical reaction where the concentration changed from 0.001 to 0.003 molar over several hours. The raw rate of change looked negligible until we switched to percentage change, which revealed a 200 percent increase — a much more useful number for decision-making.
Tools and Shortcuts
You don't need to hand-calculate everything. Most spreadsheet software has built-in functions for this. Excel's slope function calculates the rate of change across multiple points using least squares regression, which is more robust than picking two arbitrary endpoints. In Python, numpy.diff gives you the differences between consecutive array elements, and scipy.misc.derivative handles numerical differentiation for smooth functions. R users can use the diff function for discrete data or grad from the numderiv package for symbolic differentiation. For real-time monitoring applications, a simple difference between consecutive readings is usually sufficient. The trick is deciding how often to sample. If you're sampling too slowly, you miss rapid changes. Too fast and noise dominates. I typically recommend sampling at least ten times faster than the fastest change you expect to see. This is basically the Nyquist criterion applied to rate calculations. If you need something downloadable or scriptable, there are several open-source libraries. The scipy library for Python includes derivative functions that handle smoothing automatically. For JavaScript environments, math.js has a derivative method that works directly with symbolic expressions. These save time compared to building your own, though they add dependencies you should evaluate against your project constraints.
When Rate Of Change Isn't the Right Tool
Sometimes the concept itself is misleading. If you're comparing two unrelated quantities, a rate of change doesn't give you useful information. Correlation does not imply causation, and a changing ratio between two variables doesn't prove one drives the other. I've seen this mistake in economic reports where unemployment rate changes were linked to GDP changes without controlling for other factors. The rate of change was technically correct but the interpretation was flawed. When data is noisy, rate of change amplifies the noise. Derivatives are sensitive to small fluctuations, which means measurement error gets magnified. If your thermometer reads temperatures with a ±0.5 degree margin of error, your calculated rate of temperature change could be off by several degrees per unit time. Smoothing or aggregation helps, but it introduces its own lag. There's no perfect solution, only tradeoffs you need to manage based on your tolerance for error versus responsiveness. Seasonal or periodic data also complicates things. A sales figure going from December to January might show a steep drop, but that's normal seasonal variation, not a structural problem. Always subtract seasonality or compare to the same period in the previous cycle before declaring the rate of change significant. My rule of thumb is to never interpret a rate of change without first checking whether the pattern repeats in historical data.