Where the Number Actually Lives
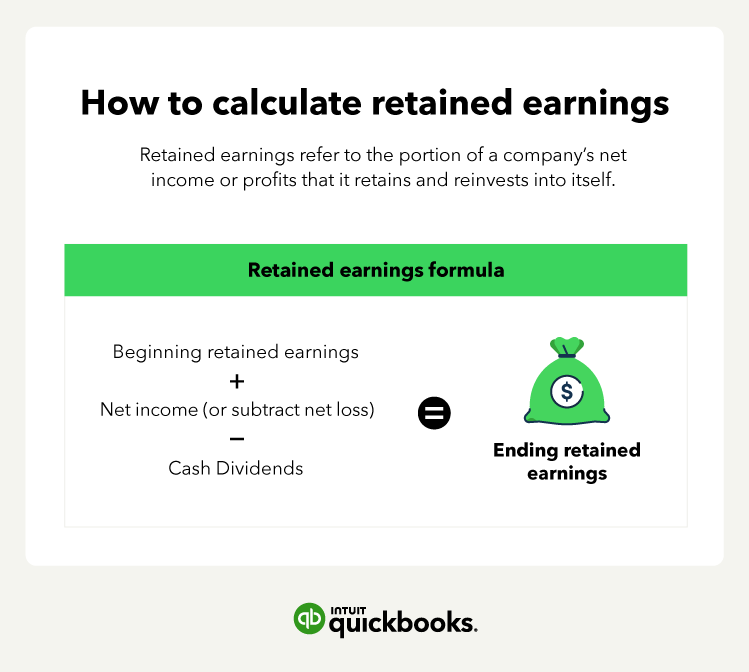
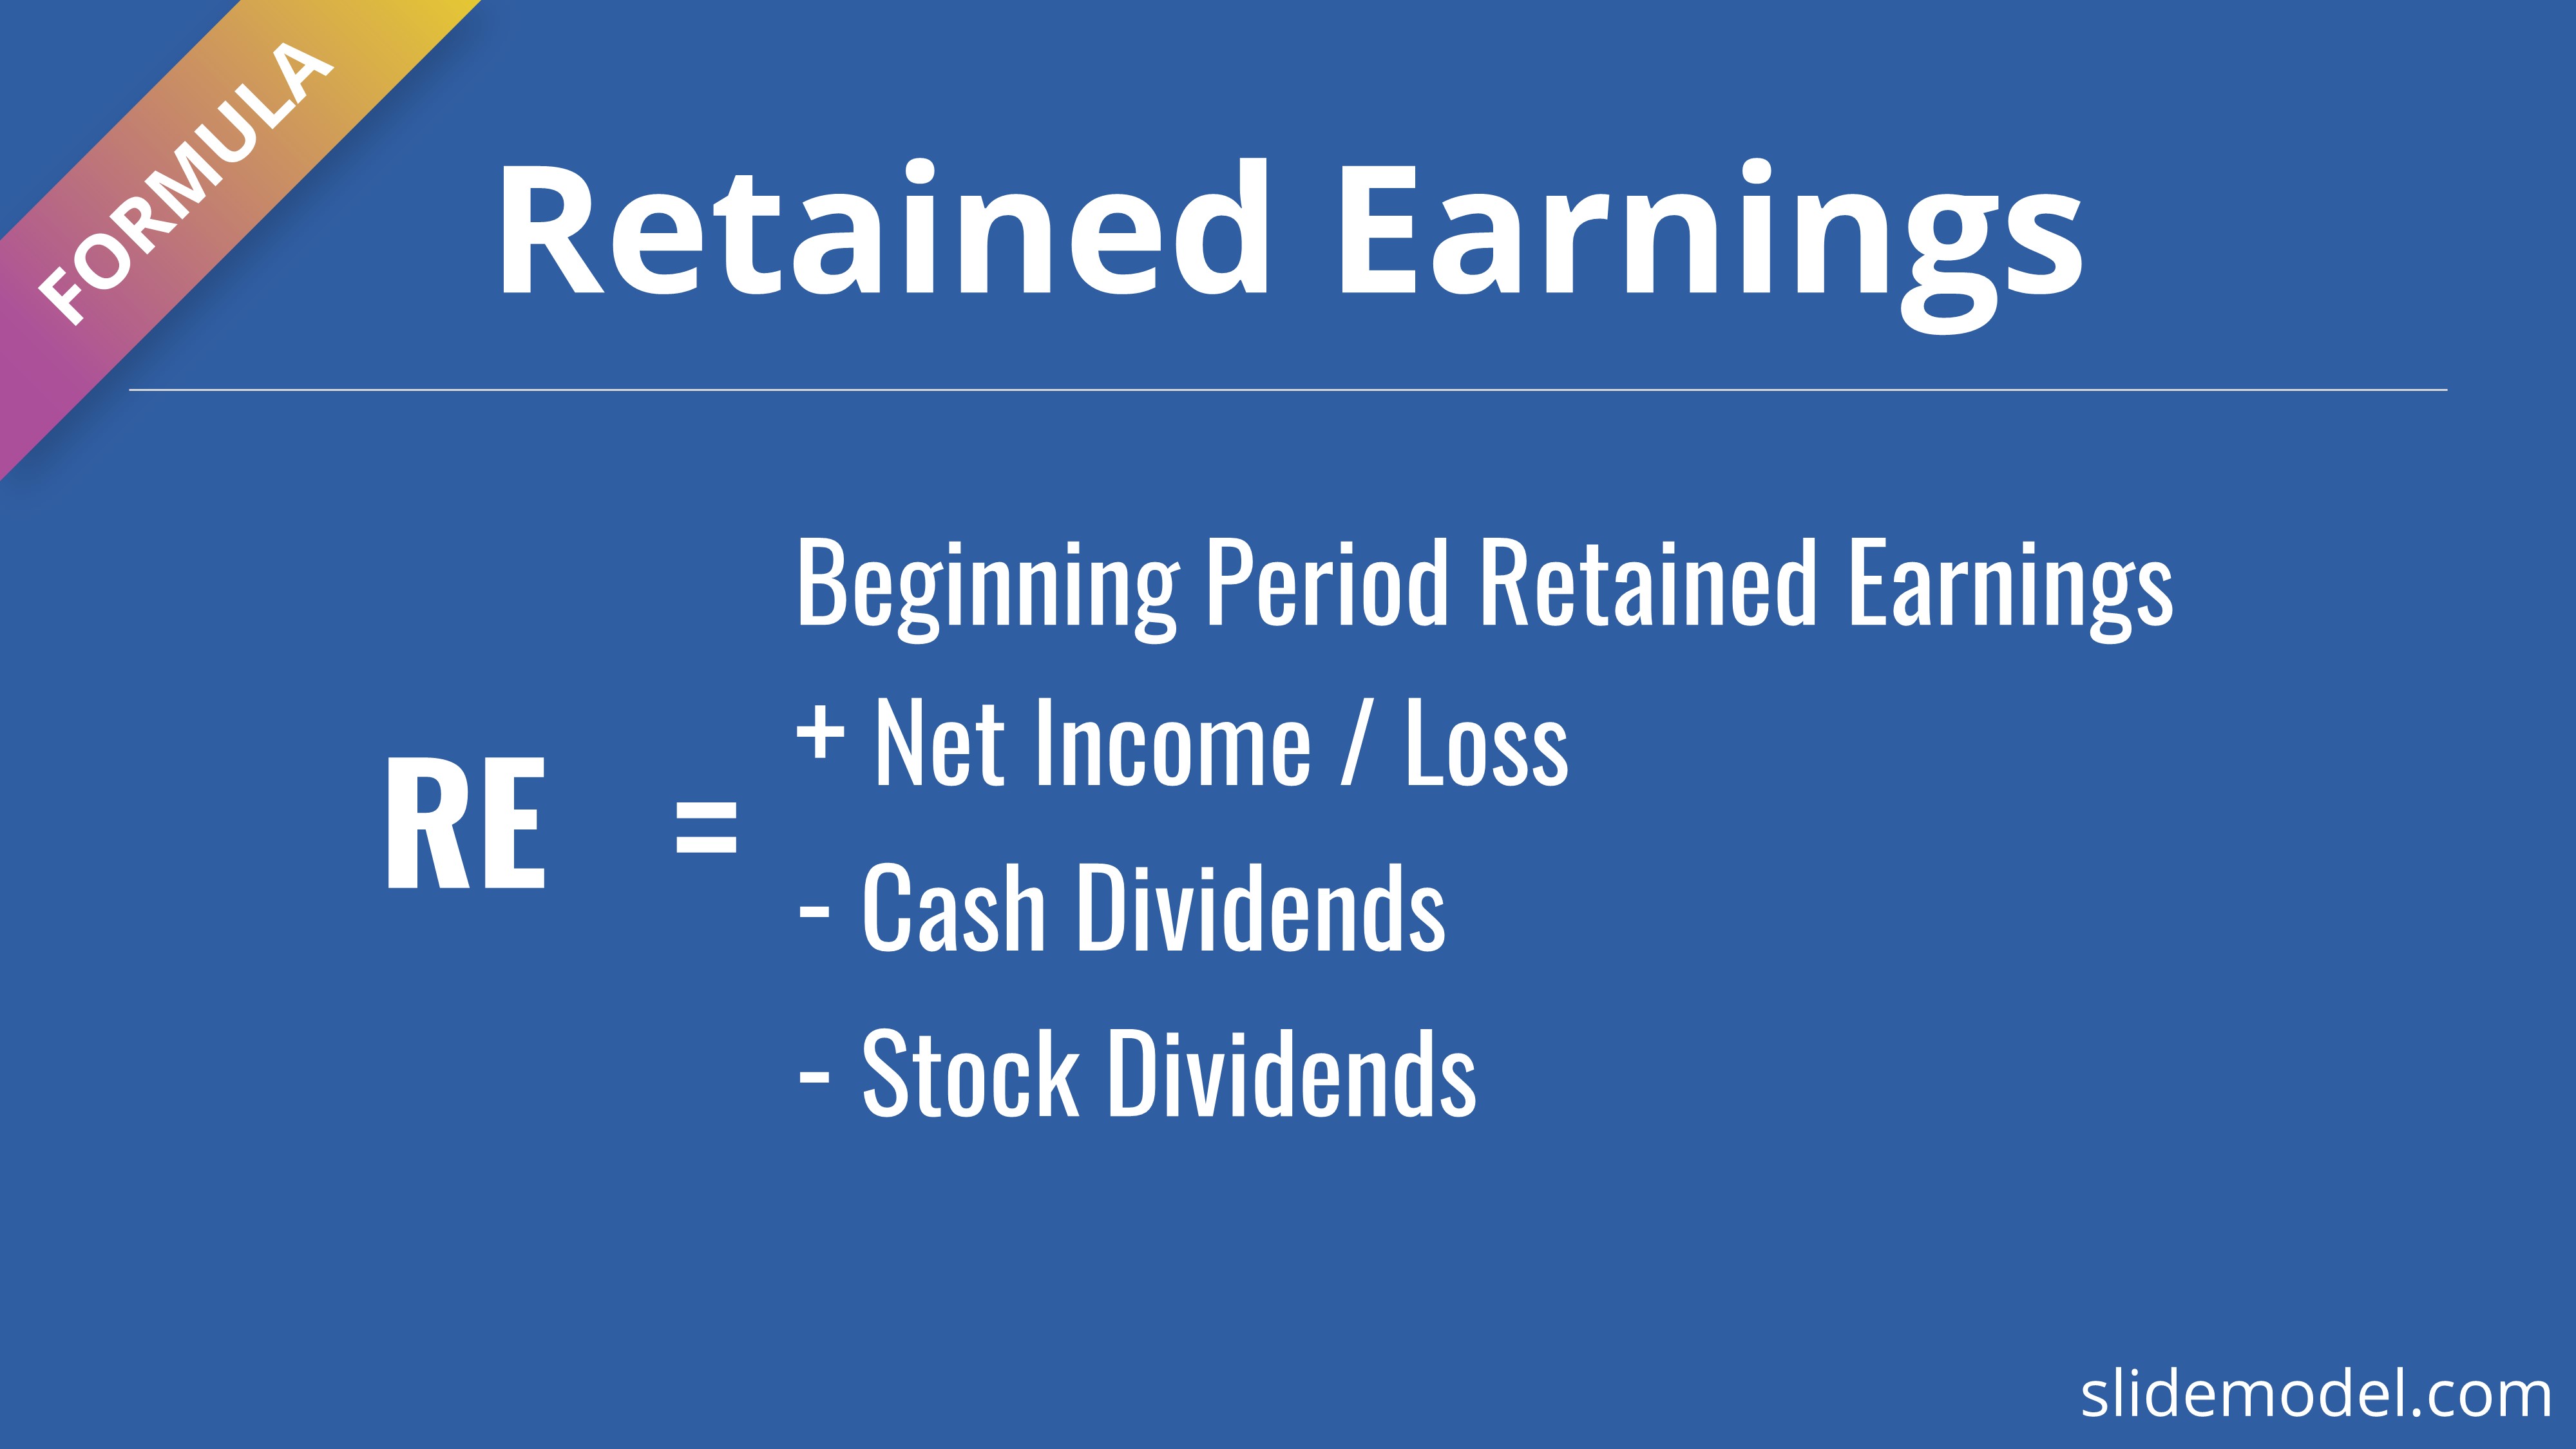
Retained earnings is the accumulated net income a company has kept rather than paid out as dividends. It sits on the balance sheet under shareholders' equity, usually labeled exactly that—retained earnings, or sometimes accumulated deficit if the number is negative. That label is important because negative retained earnings is more common than people realize, especially in older companies that had a rough early decade or went through a restructuring. There are three practical ways to get the number, and which one you use depends on what documents are in front of you. The first is the direct pull from the balance sheet. Open the most recent balance sheet, scroll down to the equity section, and look for the line item. It's typically the last line before total equity. If it's not there as its own line, check the statement of stockholders' equity or the statement of retained earnings—that document shows the full roll-forward from beginning balance through net income and dividends to ending balance. This is the most useful version because you can see what actually moved the number during the period. The second approach is the calculation method, which matters when you're working from incomplete financials or need to verify a reported figure. The formula is straightforward: beginning retained earnings plus net income minus dividends equals ending retained earnings. You pull the beginning balance from the prior period's balance sheet, grab net income from the income statement, and subtract any dividends declared during the period. Do this on a single spreadsheet. Two hours of manual reconciliation across multiple years is avoidable if you set up the links correctly from the start.
The third method is pulling the data from public filings. If you're working with a publicly traded company, go to SEC.gov and search EDGAR. Pull the annual 10-K or the quarterly 10-Q. The retained earnings figure lives in the balance sheet within the financial statements section. For quarterly reports, you'll also see the roll-forward in the statement of shareholders' equity, which gives you the dividends and net income components for that specific quarter. Private companies don't file these documents, so you either request them from management or work from whatever internal financials they maintain. I once spent an afternoon trying to reconcile retained earnings for a mid-market acquisition target and hit a wall. The balance sheet showed $1.2 million in retained earnings, but when I added up the net income and dividends going back five years, the numbers didn't match by about $340,000. The gap turned out to be a prior-period adjustment from a revenue recognition change that hadn't been disclosed prominently. The workaround was pulling the audited financials from the year of the adjustment and tracing the cumulative effect directly. It cost me half a day but saved me from basing a valuation on a corrupted equity figure.
What Most People Get Wrong About This Number
Retained earnings is not the same as net income, and confusing the two is the most common beginner mistake. Net income is a single-period figure. Retained earnings is the lifetime accumulation. A company can report strong net income in a given year and still have negative retained earnings if it accumulated enough losses before that year. I've seen analysts value businesses using a single year's net income and calling it retained earnings. That mistake inflates equity and skews every ratio downstream. Another trap is assuming retained earnings represents cash. It does not. Retained earnings is an accounting equity account. The cash could be tied up in inventory, lent to customers as receivables, or spent on equipment. A company can have $5 million in retained earnings and $200,000 in cash. The two numbers move independently, and treating them as interchangeable will get you in trouble quickly. Retained earnings can also diverge significantly between book and tax purposes. Book retained earnings follows GAAP or IFRS. Tax retained earnings follows the tax code. Differences arise from things like depreciation methods, warranty reserves, and net operating loss carryforwards. If you're analyzing a company for tax planning or assessing its tax position, the book number alone won't give you the full picture. You need the deferred tax schedule to understand where the gap comes from.
Get the Full Details
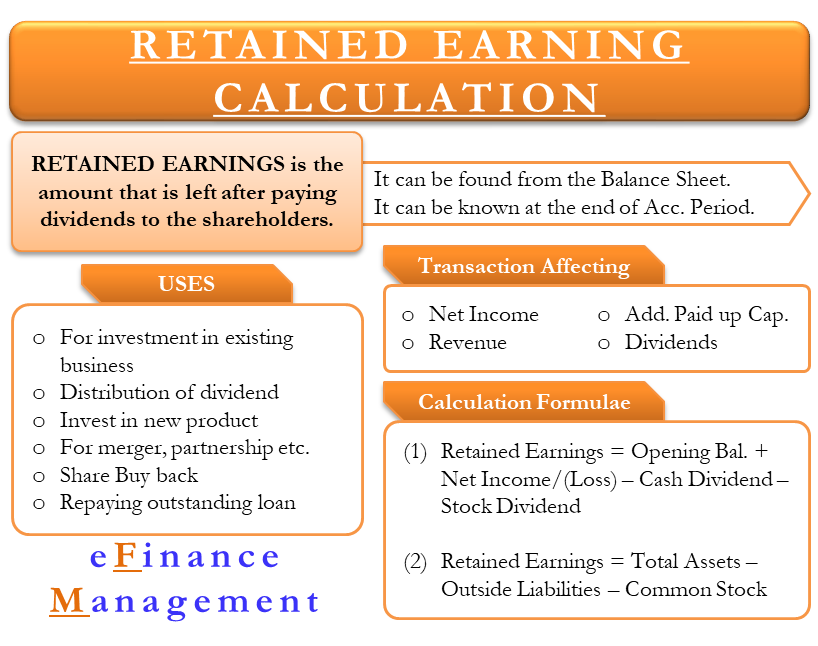
There's also a nuance with share buybacks. When a company repurchases its own stock, it doesn't hit retained earnings directly. It reduces additional paid-in capital or treasury stock depending on how the transaction is structured. But buybacks do reduce total equity, and over time they change the composition of shareholders' equity in ways that make retained earnings look proportionally larger even when the absolute number hasn't moved much. Don't read too much into a rising retained earnings percentage if the company has been aggressively buying back shares.
When the Method Breaks Down
The calculation method fails when the beginning balance itself is unreliable. This happens frequently with companies that have gone through multiple acquisitions, spin-offs, or accounting changes. Each event can reset or restate the equity section, and without clean prior-period restatements, your roll-forward will accumulate errors. In those cases, go straight to the audited financial statements and use the reported balance sheet figure. Don't rebuild it yourself unless the numbers are internally consistent, which they rarely are after complex corporate actions. For companies with off-balance-sheet liabilities or complex derivative positions, retained earnings can mask risk. The equity number looks fine until those contingent liabilities materialize. Always pair retained earnings analysis with a review of the notes to the financial statements and the cash flow statement. If retained earnings is growing but operating cash flow is declining, you're looking at accrual-driven earnings that may not be sustainable. I once flagged this on a potential investment where retained earnings grew 22% year over year while free cash flow turned negative. The company was recognizing revenue aggressively and the equity number looked healthy on paper until the cash told the real story. The other limitation is that retained earnings doesn't reflect current market value. It's a historical cost measure. For asset-heavy businesses, the book value of equity—including retained earnings—can be far below or above what the assets are actually worth today. Depreciation schedules distort the picture, especially for companies with old infrastructure or recently appraised real estate holdings.
Quick Reference for Finding the Figure
Start with the most recent balance sheet. Find retained earnings under equity. If the number needs verification, pull the statement of stockholders' equity and trace the roll-forward. Cross-reference net income from the income statement and dividends from the same equity statement. For public companies, use SEC EDGAR. For private companies, request the financials directly. Set up a spreadsheet with columns for each period, link the formulas, and let it do the work. This approach usually cuts a multi-hour reconciliation down to about twenty minutes once the template is in place.