Locating Retained Earnings on a Balance Sheet
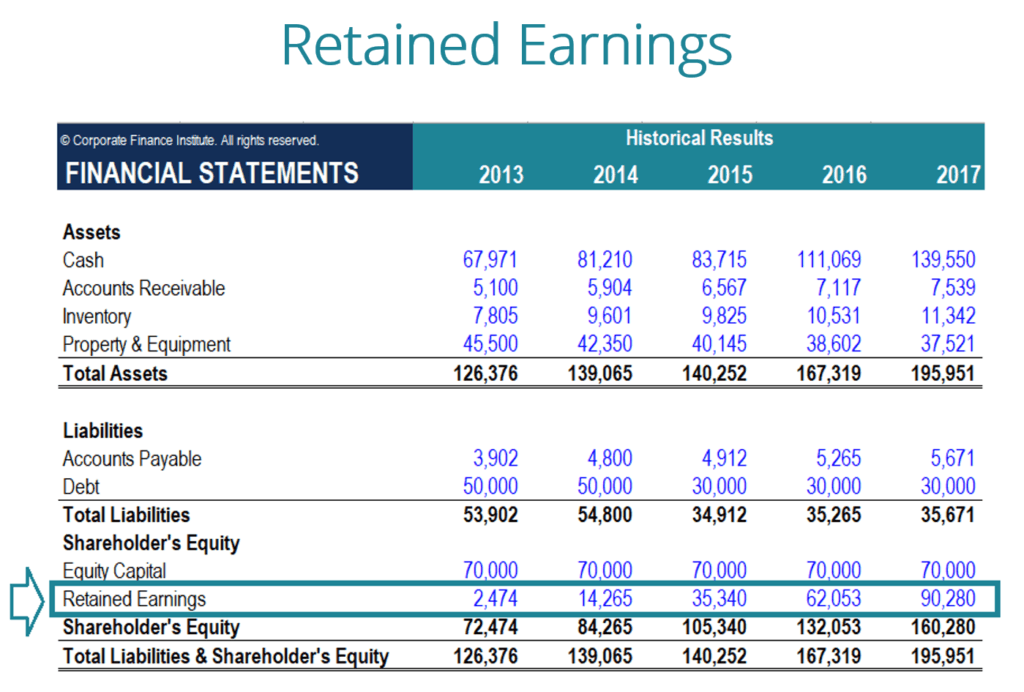
Retained earnings lives in the equity section of the balance sheet. It's not a separate schedule you pull from thin air, it's a line item sitting alongside common stock, additional paid-in capital, and treasury stock. The formula behind the number is simple enough that anyone with a spreadsheet can reproduce it, but finding the actual figure on a real balance sheet often requires knowing where to look and what to do when the label isn't exactly what you expect. Open the balance sheet and scroll to the stockholders' equity section, which typically sits below total assets. Under that heading, you'll see a list of equity components. The line labeled "Retained Earnings" — sometimes "Accumulated Retained Earnings" or "Retained Earnings / (Deficit)" — is your target. If the company is publicly traded in the US, this line will almost always appear as its own row. For private companies or smaller entities, it may be buried inside a broader equity category or combined with other accounts, which makes the lookup less straightforward than you'd hope. The number shown is the ending balance as of the report date. It represents cumulative net income minus cumulative dividends paid since the company was founded, with adjustments for things like prior-period restatements, share-based compensation, and certain tax effects. That last point matters because retained earnings isn't purely a running tally of profits. Accounting changes, correction of errors, and comprehensive income items can all feed into or pull out of that line without ever touching the income statement directly.
One useful detail most people skip: you can back into retained earnings if it's missing from a summary balance sheet by using the fundamental accounting equation. Subtract total assets from total liabilities to get total equity, then subtract contributed capital (common stock plus additional paid-in capital) from that equity figure. What remains is retained earnings. This is a workaround, not a primary method, but it comes in handy when you're looking at a condensed financial summary that only shows total equity rather than the breakdown. I ran into a situation a few years back where a mid-cap company's balance sheet showed a line item called "Stockholders' Equity" with a single lump sum, no retained earnings breakout at all. The notes referenced a separate statement of equity, but the public filing version I had access to only presented the condensed balance sheet. I ended up pulling the prior year's balance sheet, reading the retained earnings figure from that ending position, then adjusting for the current year's net income and dividends to land on the correct number. It took about twenty minutes and confirmed that relying solely on the balance sheet you're staring at is risky unless the equity section is fully detailed.
The mechanics behind the number
Retained earnings moves in a predictable direction, but the inputs aren't always obvious. Net income flows in from the income statement. Dividends flow out. Stock repurchases affect the equity section through treasury stock, which is a contra-equity account that reduces total equity but doesn't directly touch retained earnings. Stock splits change share counts and par values, which affects the common stock and APIC lines, not retained earnings. Those distinctions matter because mixing them up will give you a wrong answer every time. Another nuance that trips people up is accumulated other comprehensive income. AOCI sits in equity alongside retained earnings on most US GAAP balance sheets, but it's a separate bucket. Foreign currency translation adjustments, unrealized gains or losses on certain investments, and pension actuarial adjustments all accumulate there. If you see a large swing in total equity that doesn't match the income statement or dividend activity, AOCI is usually the reason. Treating it as part of retained earnings is a common error, and it skews your analysis in ways that compound over time. There's also the question of retained earnings deficits. When a company has never been profitable or has distributed more in dividends than it earned, the retained earnings line flips negative. Some people read a negative number and assume something is broken. It isn't. It simply means the company has consumed more capital than it has generated through operations. In those cases, looking at the trajectory matters more than the absolute value, because a negative balance that's shrinking is very different from one that's growing worse.
Get the Full Details

What the balance sheet won't tell you
Retained earnings on the balance sheet is a snapshot, not a story. It tells you where the number stands on a specific date, but it doesn't show you the drivers of change between dates. If you want to understand the movement, you need the statement of retained earnings or the statement of changes in equity. Those statements break out beginning balance, net income, dividends, adjustments, and the ending balance in sequence. Without them, you're inferring causation from a static number, which is fine for basic analysis but insufficient for anything requiring precision. I've also encountered cases where the retained earnings figure on the balance sheet doesn't match what you'd calculate from the income statement and dividend history, usually because of a prior-period adjustment or a restatement. A company might restate a prior year due to a revenue recognition change, and that adjustment hits retained earnings directly rather than flowing through the current period's income statement. The result is a jump or drop in retained earnings that has no corresponding line on the current income statement. If your numbers aren't reconciling, that's the first place to look. International filings add another layer. Under IFRS, the equity section is structured differently. Some companies present "retained profits" rather than "retained earnings." Others combine multiple equity components into a single line under broader categories. If you're pulling numbers from non-US GAAP sources, you may need to dig into the notes to confirm exactly which equity items are included in what you're calling retained earnings. The underlying concept is the same, but the presentation varies enough that assumptions based on US filings can lead you astray.
Practical steps when you need the number now
First, check the equity section of the balance sheet for a line explicitly labeled retained earnings. If it's there, read the figure as of the report date and move on. If the line is missing or combined, switch to the notes. The notes to the financial statements almost always contain a reconciliation of equity, which will show you the retained earnings component even if the balance sheet doesn't break it out. This reconciliation is typically the most reliable source because it explains every change during the period rather than presenting an isolated snapshot. When working with condensed financial data, like quarterly summaries or press release figures, the level of detail drops significantly. You may only see total equity without any breakdown. In those scenarios, your best option is to locate the full annual filing, extract the retained earnings figure from the most recent balance sheet, and reconcile forward using the income statement and dividend information from the periods you're analyzing. It adds a few steps, but it prevents you from making assumptions based on incomplete data. There are tools that automate parts of this process. Financial data platforms like Bloomberg, Capital IQ, and even some free aggregators pull equity line items into structured datasets. The trade-off is that these platforms sometimes normalize labels differently across companies, which can cause mismatches if you're comparing retained earnings figures across firms with different presentation conventions. Manual verification against the original filing is still the safest approach when accuracy matters, especially for investment decisions or audit work where the source document is the authority, not the aggregator's interpretation.
The whole exercise takes longer than it should when the balance sheet isn't detailed, but once you know where to look and what to watch for, it becomes a routine lookup rather than a scavenger hunt. The number itself is straightforward. The complexity comes from real-world presentation variability, restatements, and the occasional missing disclosure that forces you to reconstruct the figure from adjacent statements.