Working with matrix inverses is a lot less mysterious than people make it seem, but also more finicky than textbooks suggest.
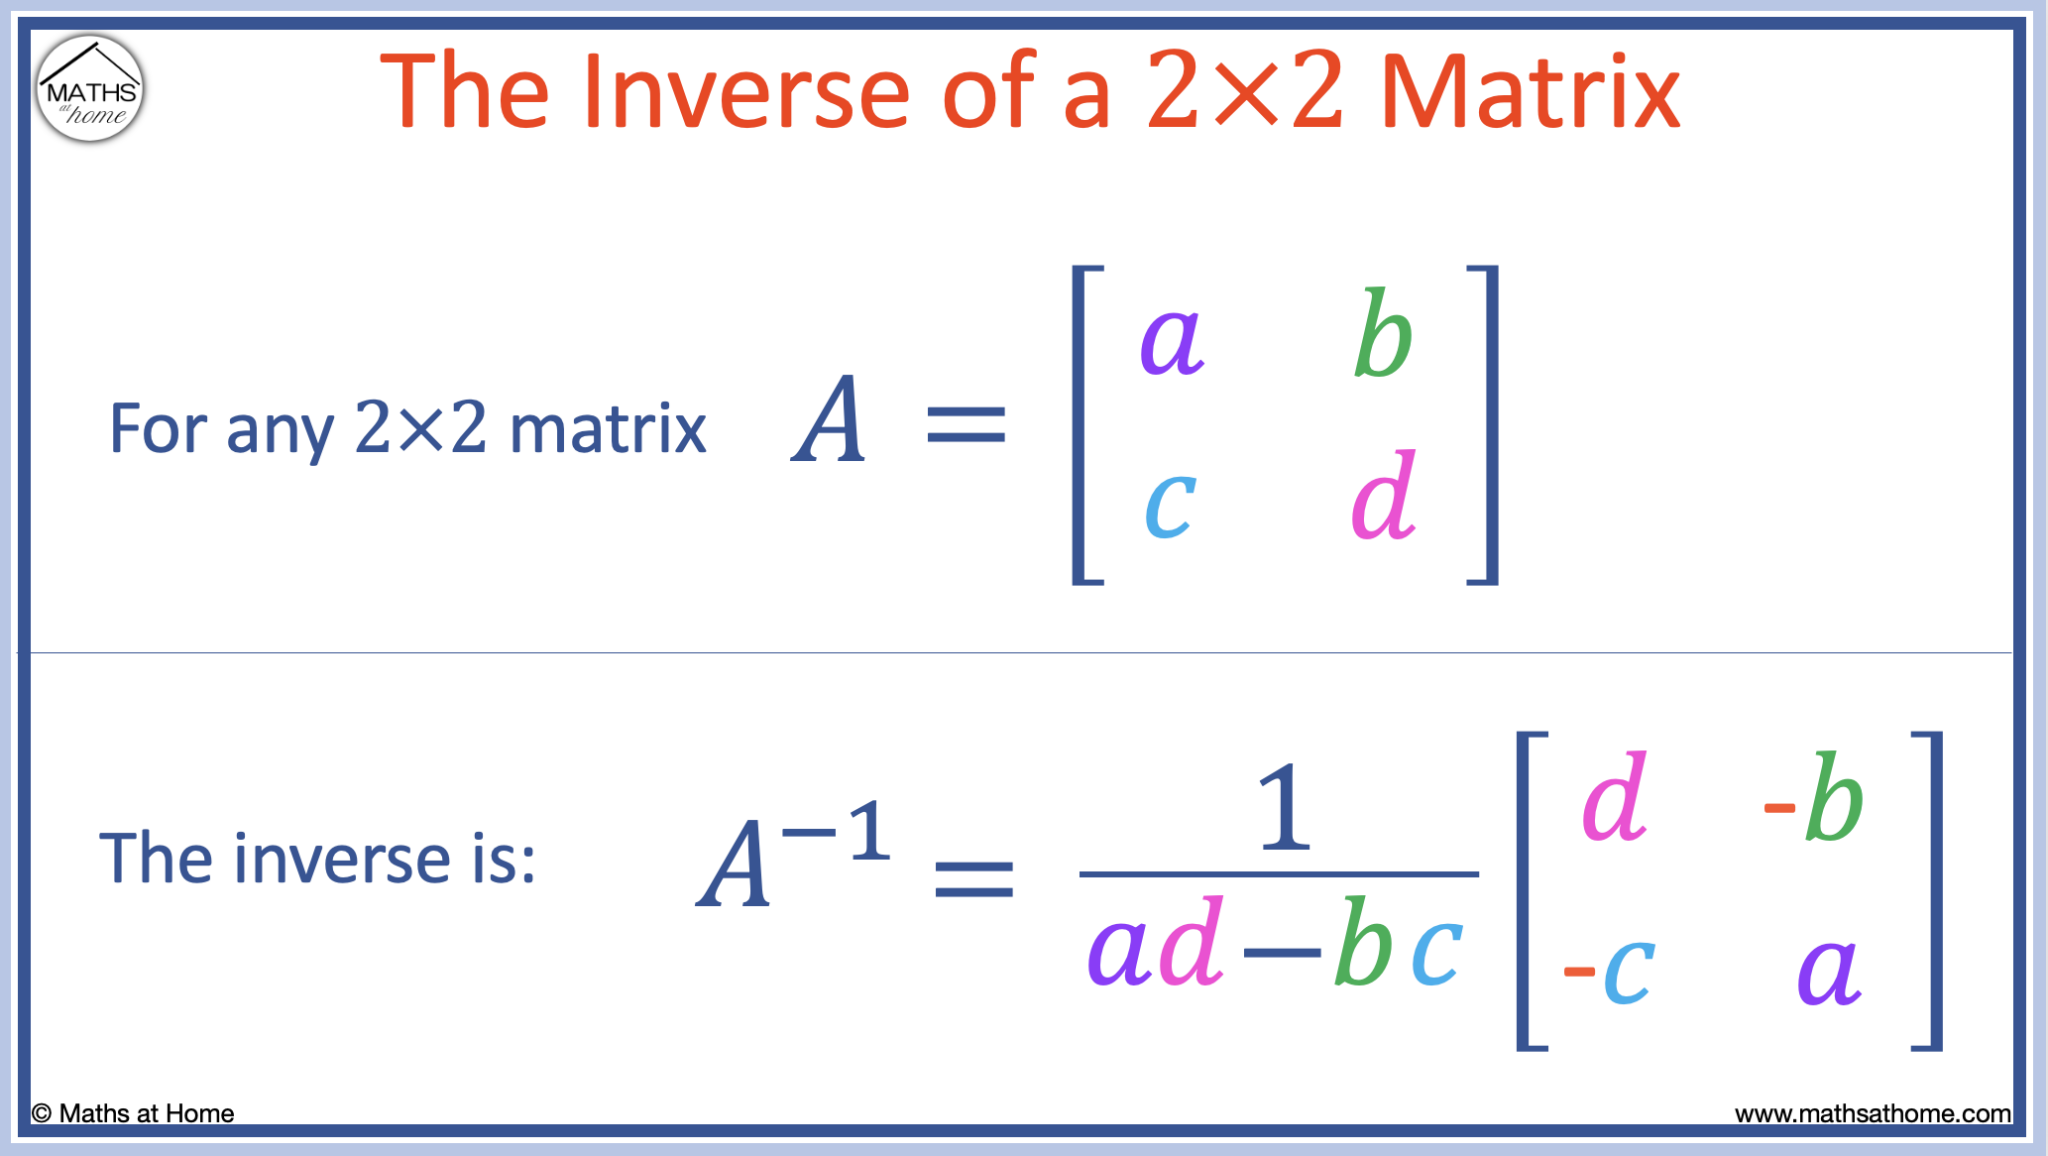
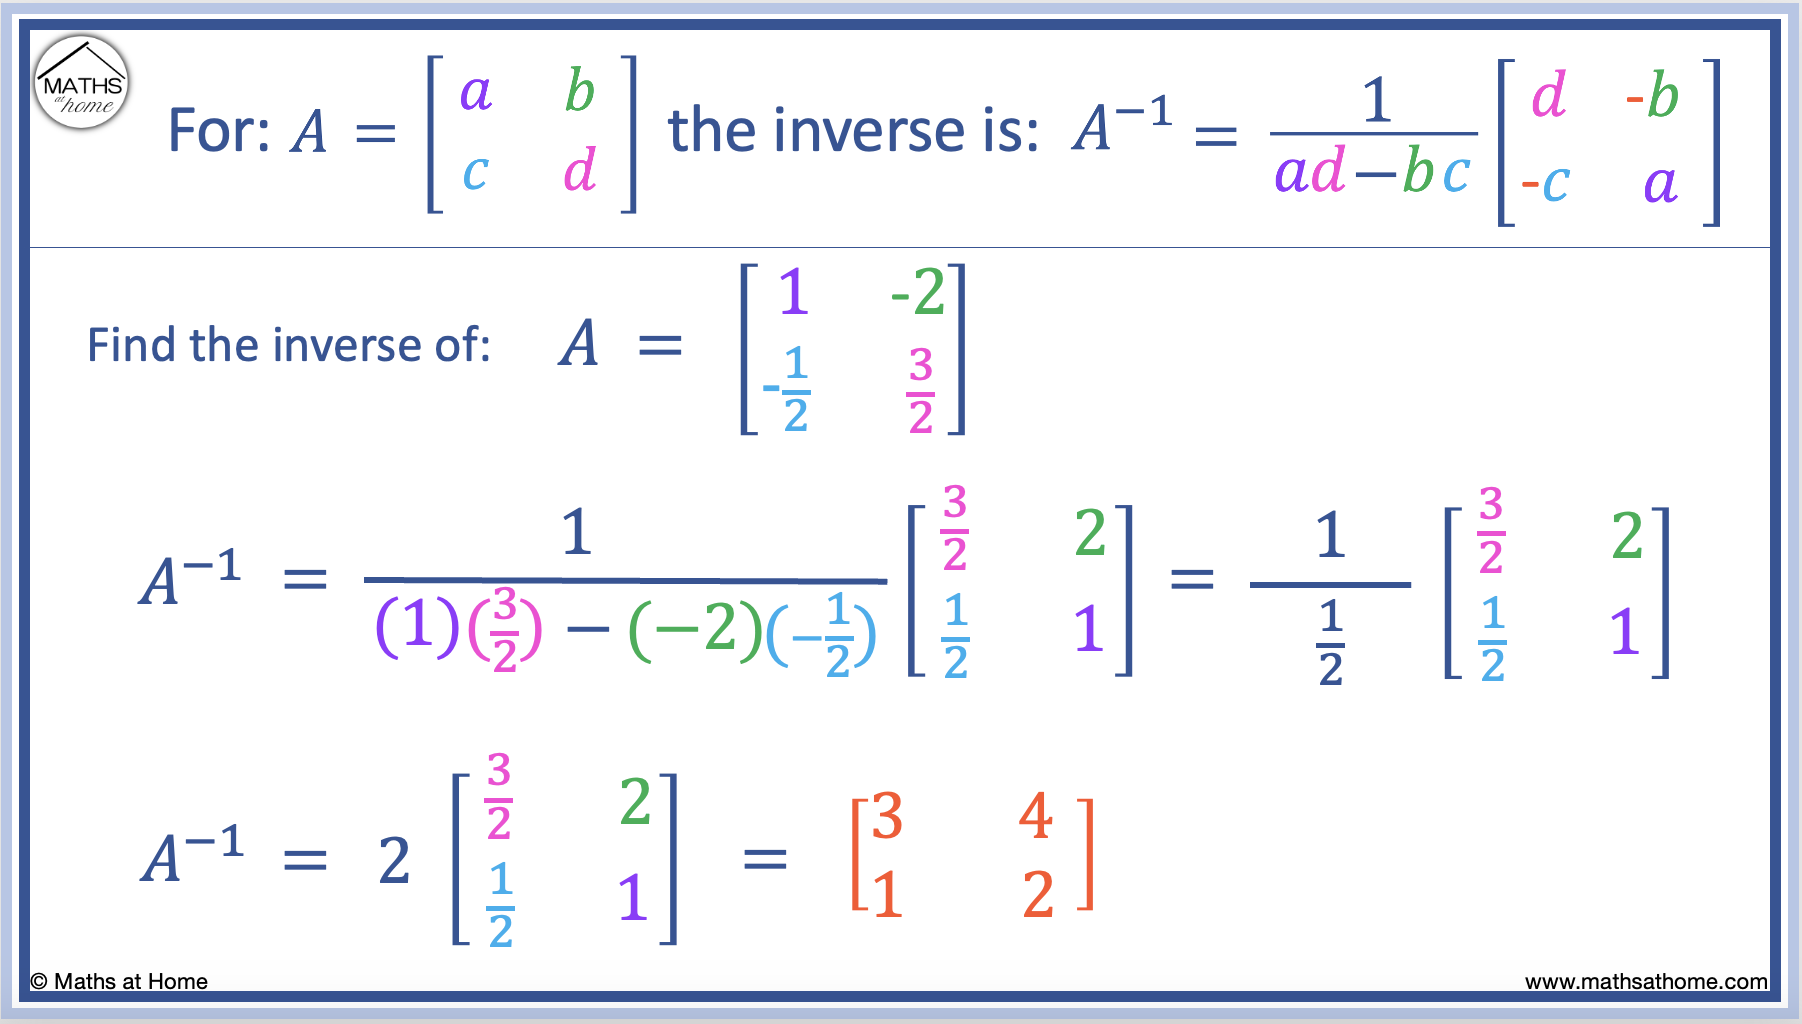
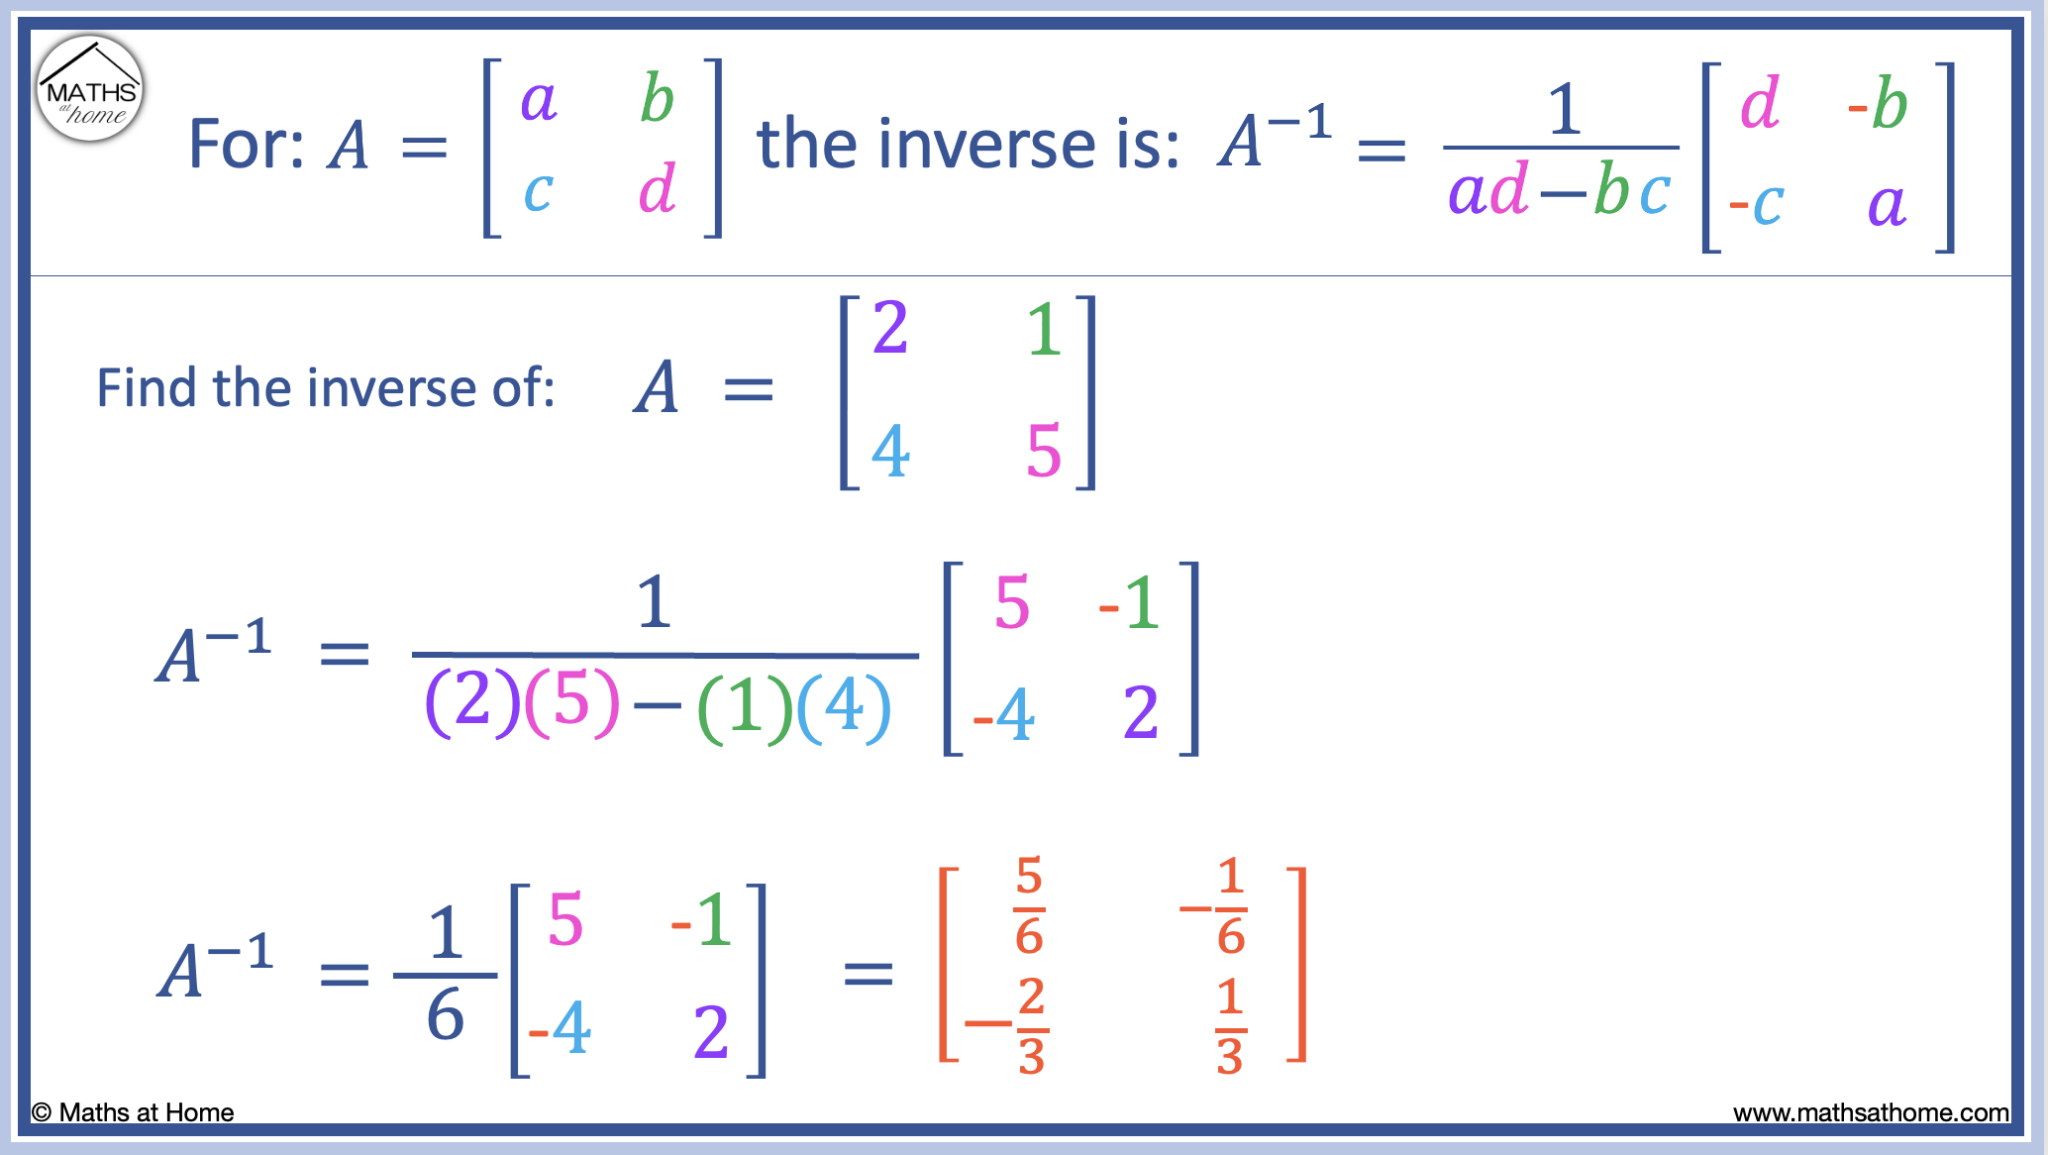
Most people try to find the inverse by memorizing formulas, which works fine for a 2x2 but breaks apart completely as soon as you hit anything larger. I spent years fixing calculation errors in engineering spreadsheets before I stopped trusting the shortcut methods entirely. Here is how I actually approach it now. The mathematical definition is straightforward: for a square matrix A, the inverse A^-1 satisfies A * A^-1 = I, where I is the identity matrix. That is it. Nothing philosophical about it. The problem is that most people learn the adjugate method and try to use it for matrices bigger than 3x3, which is practically guaranteed to produce a wrong answer because the manual calculation becomes unreasonably error-prone. I once spent three hours debugging a student's homework where the entire issue came down to a single sign error in a 4x4 cofactor expansion. The whole thing was wrong by the time she finished. For small matrices, you can use the determinant method. A 2x2 matrix [[a, b], [c, d]] has the inverse 1/(ad-bc) * [[d, -b], [-c, a]]. The determinant ad-bc just needs to be non-zero. If it is zero, the matrix is singular and no inverse exists. Period. There is no workaround. I have seen people try to force an inverse on singular matrices using calculators that silently return garbage instead of throwing an error, which is worse than admitting the problem upfront.
The Practical Methods That Actually Work
Row reduction, also called Gauss-Jordan elimination, is the method I reach for in almost every situation. You set up an augmented matrix by placing the identity matrix next to your original matrix, then perform row operations until the left side becomes the identity. Whatever ends up on the right side is your inverse. It sounds tedious but it scales cleanly to any size, and it is straightforward to code or use in any spreadsheet. Here is a concrete walkthrough. Take the matrix [[2, 1], [1, 3]]. Set up the augmented form [[2, 1 | 1, 0], [1, 3 | 0, 1]]. Divide the first row by 2 to get a leading 1. Subtract half of row 1 from row 2. Now eliminate the 1 above the second pivot. You end up with [[1, 0 | 3/5, -1/5], [0, 1 | -1/5, 2/5]]. That right side is your inverse. Multiply it back against the original to verify. This process takes about two minutes on paper for a 2x2 and maybe fifteen minutes for a 4x4 if you are careful. For larger systems, Gaussian elimination followed by back substitution on each column of the identity matrix is faster than full Gauss-Jordan because you avoid unnecessary operations. Solvers and libraries like NumPy use optimized LU decomposition under the hood, which is roughly three to four times faster than naive row reduction for matrices above 10x10. If you are writing code, just call numpy.linalg.inv and move on with your day.
Edge Cases and Things That Break Your Workflow
Singular matrices are the obvious failure point, but there is a subtler issue that catches experienced people off guard: near-singular or ill-conditioned matrices. A matrix can have a non-zero determinant yet still be numerically unstable enough that the computed inverse is essentially noise. I ran into this when working with a finite element model where the stiffness matrix had a condition number around 10^12. The inverse it returned looked correct on paper but produced wildly wrong displacement values downstream. Swapping to a pseudo-inverse via singular value decomposition gave stable results without the blowup. Another practical pitfall is that computing the inverse explicitly is often the wrong move. If your actual goal is solving Ax = b, using the inverse to compute x = A^-1 b is both slower and less numerically stable than solving the system directly with a factorization. This is one of those things that every linear algebra course mentions but nobody actually remembers until their simulation crashes. I stopped computing inverses explicitly about ten years ago. I use factorizations or iterative solvers instead, which cut computation time significantly for the problems I work with.
Get the Full Details
When There Is No Inverse At All
If your matrix is not square, the concept of an inverse does not apply in the standard sense. You can compute a left inverse or right inverse under certain rank conditions, or fall back to the Moore-Penrose pseudoinverse, but these are different objects with different properties. A rectangular matrix with more rows than columns, for example, generally has no true inverse. Pretending otherwise leads to equations that cannot be satisfied consistently. Sparse matrices are another category where the standard inverse is a bad idea. The inverse of a sparse matrix is usually dense, so storing and computing it destroys whatever efficiency you had. I work with large sparse systems regularly and just never invert them. Direct solvers that operate on the sparsity structure or preconditioned iterative methods handle these cases in a fraction of the time with a fraction of the memory.
How To Find The Inverse Of A Matrix Using What You Actually Have
If you are doing this by hand, stick to Gauss-Jordan for anything up to 4x4 and double-check your arithmetic at every pivot step. If you are doing this in software, use the built-in solver rather than rolling your own elimination unless you have a specific reason to. And before you compute an inverse for any applied problem, ask yourself whether you actually need the inverse or just need to solve a linear system. The answer is usually the latter, and taking that route saves you from a lot of preventable headaches.