The practical guide to finding where functions hit zero
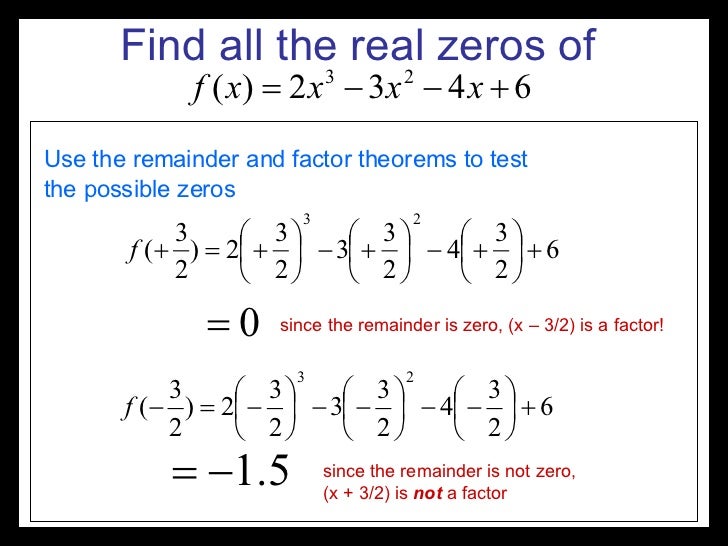
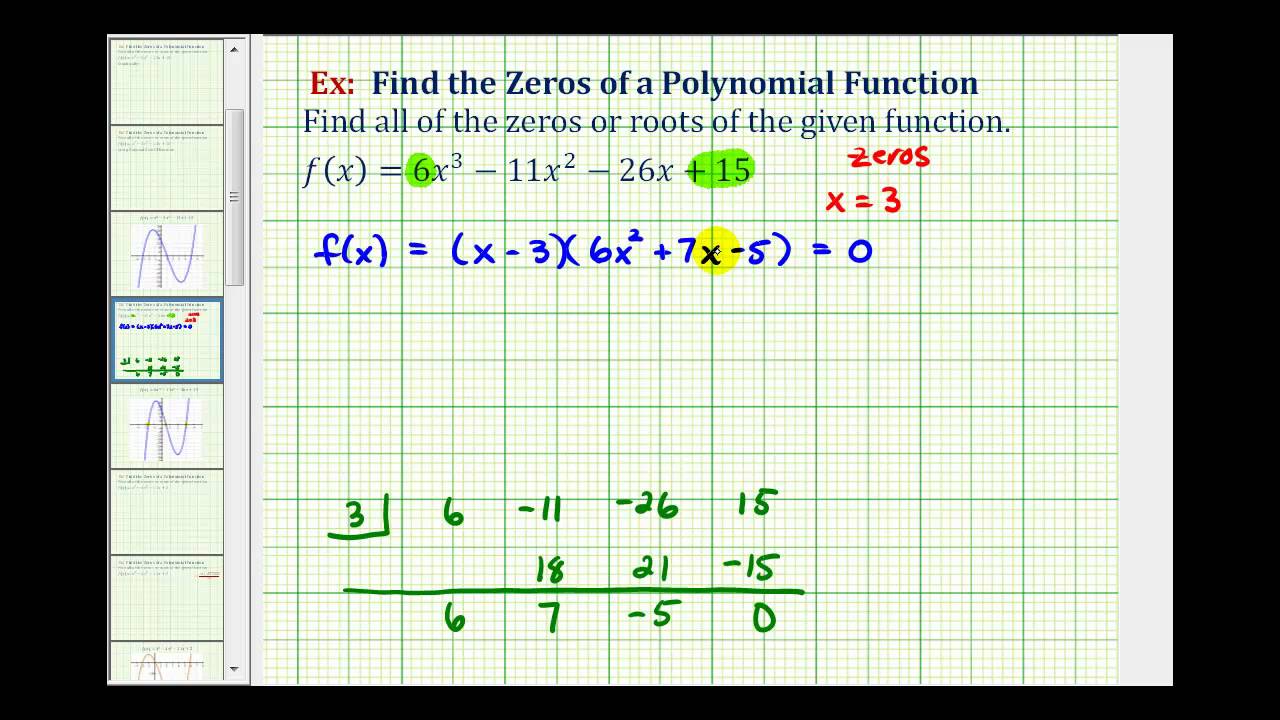
Most people encounter zeros when they need to solve equations or find where a curve crosses the x-axis. The approach changes completely depending on whether you are working with polynomials, transcendental functions, or numerical data. I spent years doing this in engineering software, and the shortcuts matter way more than the theory. Start by classifying what you actually have. A polynomial of degree 1 or 2 can be solved analytically with the quadratic formula. Cubics and quartics have closed-form solutions but they are messy enough that nobody uses them by hand. Once you hit degree 5 or above, you are fundamentally out of luck for exact algebraic solutions, so numerical methods take over. This is where most people get stuck because they keep trying to factor something that refuses to factor nicely. For transcendental functions like trigonometric, exponential, or logarithmic expressions mixed with polynomials, there is no general analytical path. You need iterative methods. The most common approach is the Newton-Raphson method, which uses the derivative to converge toward a root. The formula is straightforward: start with an initial guess, evaluate the function and its derivative at that point, then step along the tangent line to the x-axis. Repeat until the value is close enough to zero.
The catch is that Newton-Raphson can fail spectacularly if your initial guess is in the wrong place. It can diverge, cycle between values, or converge to a completely different root than you intended. I ran into this exact problem when I was modeling a damped harmonic oscillator and needed the zeros of a function involving both sine and an exponential decay term. The derivative had flat regions near the zeros, which caused the iterations to overshoot wildly and send the solver off to infinity instead of converging. My workaround was to bracket each root first using a coarse grid scan, narrowing in on sign changes before applying Newton-Raphson. That single change took my solver from frequently crashing to running reliably on the first try.
Alternative methods when Newton fails
Brent's method is generally safer than pure Newton-Raphson because it combines bisection with inverse quadratic interpolation. It requires a bracketed interval where the function changes sign, and it guarantees convergence as long as the function is continuous within that interval. The trade-off is that it is slower than Newton-Raphson once it gets close to the root, though usually only by a small margin. In most production code I have written, Brent's method is the default choice precisely because the reliability outweighs the minor speed difference. The bisection method itself is the simplest possible approach. Pick two points where the function has opposite signs, evaluate the midpoint, and replace whichever endpoint shares the same sign as the midpoint. Each iteration halves the interval. It is boringly reliable but converges linearly, meaning you gain roughly one bit of precision per step. For high-precision work this can feel glacially slow compared to superlinear methods. For polynomial-specific root finding, the companion matrix approach is worth knowing about. You construct a matrix whose eigenvalues are exactly the roots of the polynomial, then use a standard eigenvalue solver. This works for any degree and handles multiple roots and complex conjugate pairs naturally. The downside is that rounding errors in floating-point arithmetic can make the computed eigenvalues slightly inaccurate, especially for high-degree polynomials with closely spaced roots.
Get the Full Details
Common pitfalls that waste hours
One issue that catches everyone at least once is assuming that a function has a zero when it actually just touches the axis and turns around. A double root, for instance, means the function is zero and its derivative is zero at the same point. Newton-Raphson will converge to such a root but only linearly instead of quadratically, so it takes far more iterations than expected. If you notice your solver stalling with diminishing returns, check whether you might be dealing with a multiple root rather than a simple crossing. Another frequent problem is domain violations. Functions involving logarithms, square roots, or division by expressions that can reach zero will throw errors or return NaN values when an iteration lands outside the valid domain. I once wrote a solver for a control system transfer function that kept failing because the iterations wandered into regions where the logarithmic terms were undefined. The fix was straightforward domain clipping: after each Newton step, I checked whether the new point was still in the valid domain, and if not, I halved the step size until it was. This added negligible overhead and eliminated the crashes entirely. When working with discrete or experimental data rather than analytical functions, there is no derivative to use. Linear interpolation between sampled points gives you an approximate zero within each interval where a sign change occurs. This is good enough for most practical purposes and is what many data analysis libraries do under the hood. The accuracy is limited by your sampling rate, so if you need precision better than roughly one sampling interval, you need either a denser grid or a different strategy entirely.
When no method works at all
Sometimes a function genuinely has no zeros in the domain you care about, and the only way to know is to prove it. This is where analytical reasoning matters. For a polynomial, the fundamental theorem of algebra guarantees that every non-constant polynomial has at least one complex root, but real zeros depend on the specific coefficients. Sturm sequences or Descartes' rule of signs can tell you the exact number of real roots in a given interval without computing them. These are classical results but they are often skipped in introductory courses, which means most people just throw numerical methods at everything and hope for the best. Numerical solvers also break down for functions that are discontinuous or not differentiable at or near the root. If your function has a jump discontinuity, a sign change does not imply a zero exists at the jump. You might observe a sign flip between two sample points and falsely conclude a root is there. Always verify that the function is continuous on the interval before trusting a bracketed method to deliver a valid zero. For multi-dimensional systems, finding zeros becomes significantly harder. You are solving a system of equations simultaneously, and there may be no zeros at all, a continuum of zeros, or a finite set of isolated solutions. Numerical continuation methods and homotopy-based approaches exist but they are computationally expensive and require careful setup. In practice, if you are working with multivariate systems, you are usually better off reformulating the problem or using a dedicated library rather than trying to implement something from scratch.
The bottom line is that finding zeros is a broad topic with no single correct approach. The method you choose should depend on the function type, the required precision, and how much you can afford to spend on computation. Brute-forcing every problem with Newton-Raphson works until it does not, and by then you have usually wasted a lot of debugging time. Classify first, bracket when possible, verify continuity, and use the simplest method that meets your accuracy requirements.