What Manual Underwriting Actually Is
Manual underwriting is the opposite of an automated approval. Instead of a computer running your credit score, debt-to-income ratio, and reserves through Fannie Mae or Freddie Mac guidelines in thirty seconds, a real human underwriter looks at your entire financial picture and makes a judgment call. The software says no. The underwriter says maybe, depending on what they see when they look past the numbers. I spent years working loan files where the automated system would flag a borrower the moment it saw a gap in employment history or a single late payment from three years ago. The computer didn't care that they'd been current for twenty-four straight months after that. It just flagged. So the file went to manual underwriting, where a person actually read the story behind the data. Most of those loans closed. A few didn't. That's the difference. The most common programs that allow manual underwriting are FHA loans, VA loans, and some USDA loans. Conventional loans through Fannie and Freddie generally don't offer it outside of specific non-warranted condo situations or portfolio products from individual lenders. FHA is by far the most widely used path for this approach, which is why most people looking into it end up on that track.
How To Get A Manual Underwriting Mortgage
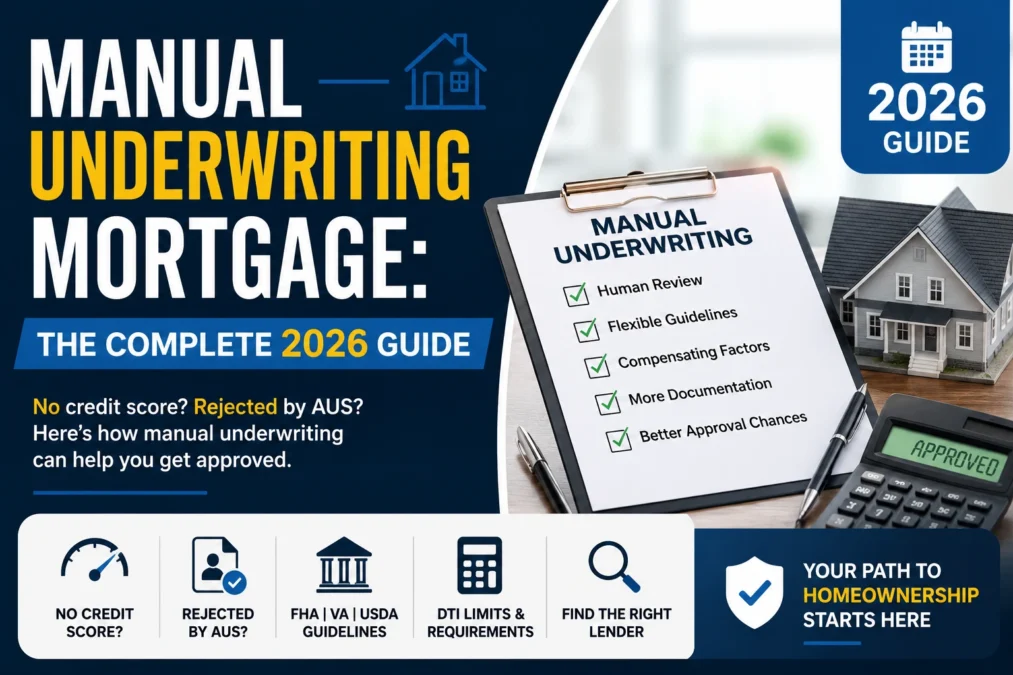
The process starts the same way any mortgage does: you apply with a lender. The difference is you specifically tell them you need manual underwriting, not an automated one. They should already know this if you have a thin credit file or non-standard income, but saying it outright prevents your application from getting sent down the wrong pipeline. Once your file is flagged for manual review, the requirements shift significantly, and here's what you'll need to prepare. FHA manual underwriting requires two years of employment history. Not necessarily the same job. Not necessarily the same industry. Two years where money came in consistently and you had a reasonable explanation for any changes. If you were between jobs for four months because you relocated, that's fine. If you were unemployed for eleven months and then worked retail for six months before returning to your field, the underwriter will want a letter explaining that gap. I've had underwriters accept a paragraph. I've had others require a three-paragraph narrative. It varies by human being. Credit requirements under manual underwriting are lower than automated, but not as low as people assume. FHA technically allows approval with a 500 credit score if you put 10 percent down. In practice, almost no lender will touch anything below 580. The realistic floor most manual underwriters will accept is around 580 to 620, depending on the rest of the file. A score of 580 with a solid two-year rental payment history and no recent delinquencies can work. A score of 640 with three evictions on record probably won't, because the underwriter is judging the whole story, not just the number.
The debt-to-income ratio calculation also changes. Automated underwriting uses a rigid DTI cap, usually 43 percent for FHA. Manual underwriting doesn't have a hard cap, but the accepted range is typically 45 to 50 percent with strong compensating factors. Those compensating factors are what separate the approved files from the denied ones. A large cash reserve covering twelve months of payments, a low loan-to-value ratio, or a documented history of on-time housing payments all help. Without them, a 48 percent DTI is likely going nowhere. Documentation is heavier than automated. You'll provide tax returns, W-2s, pay stubs, bank statements, and a letter of explanation for any anomalies. But you'll also need additional items like a rent payment history from your landlord, utility bills showing on-time payments if you rent, and sometimes even a letter from your employer confirming your position and expected continuation of employment. The more you can document, the easier the review becomes.
Get the Full Details

Common Situations That Require Manual Underwriting
Self-employed borrowers with significant deductions on their tax returns often end up here. The automated system sees your adjusted gross income and your business expenses and calculates a low qualifying income. A manual underwriter can look at your Schedule C, add back legitimate depreciation or amortization, and determine your actual cash flow is higher than the computer reported. This is one area where manual underwriting genuinely helps borrowers who would otherwise be disqualified. People with recent bankruptcy or foreclosure face the same situation. Automated systems have strict waiting period calculators. Manual underwriters also enforce waiting periods, but they can weigh circumstances. A bankruptcy caused by a medical emergency during a job loss might receive more consideration than one caused by chronic overspending. The waiting period is still two years for FHA after bankruptcy discharge and three years after foreclosure, but within that framework, the underwriter has discretion on whether to approve. Non-traditional credit is another category. Some borrowers don't have credit cards or installment loans. They pay rent, utilities, and phone bills in cash or by check. Automated systems can't evaluate these, so they see no credit history and decline the application. Manual underwriters can use substitute credit, analyzing those payment histories as a stand-in for traditional credit report lines. This is a significant advantage for immigrants or younger borrowers who've simply never opened a credit account.
A Problem I Encountered and How I Solved It
I once worked with a borrower who had a credit score of 610 and a DTI of 46 percent. She had two late payments in the past year, both for credit cards, and she'd explained them as oversights from a difficult quarter at work. The automated system would have denied her immediately. The manual underwriter was sympathetic but resistant. The file was getting stuck on the combination of low score plus high DTI plus recent delinquencies. Nothing in the file was wrong. Everything together just wasn't compelling enough for the person reviewing it. The workaround was documentation she hadn't thought to provide. I asked for six months of bank statements showing her paying off each credit card balance in full every month despite the late payments. That demonstrated she had the ability to pay but had been careless with timing. I also had her landlord write a letter confirming she'd paid rent on time for two years. Combined with a letter from her employer confirming a raise she'd received three months after those late payments, the picture changed. The underwriter approved the loan. The same file without those documents would have been declined. That's the practical reality of manual underwriting: the depth and quality of your supplementary documentation determines the outcome as much as your numbers do.
What Manual Underwriting Costs and Takes
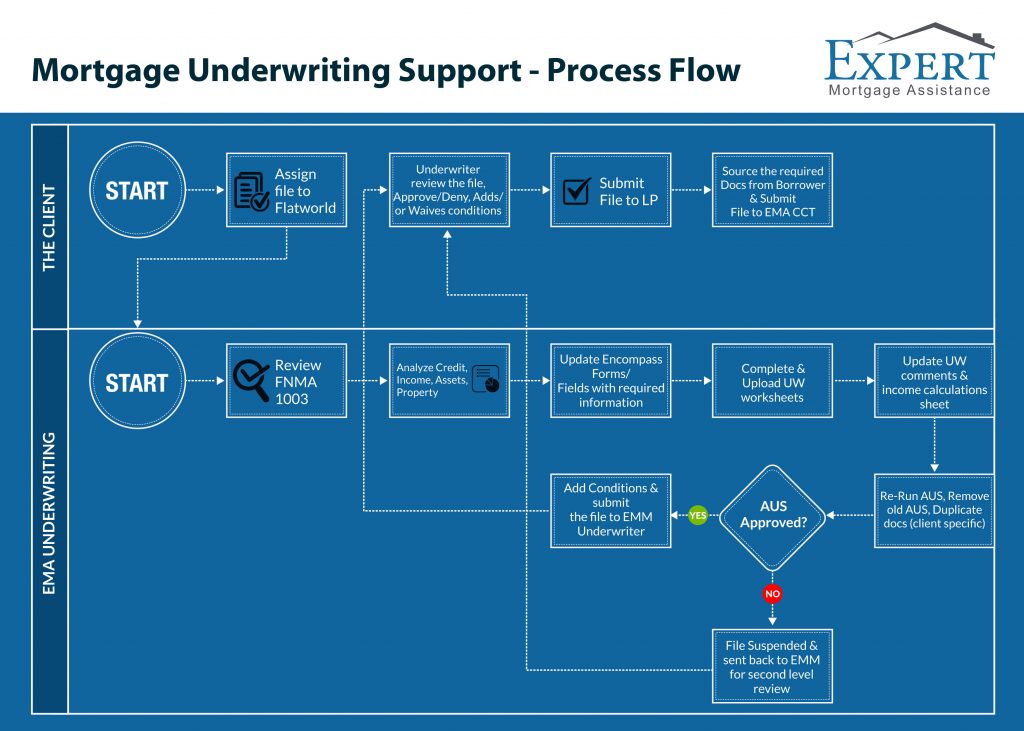
Manual underwriting is slower and more expensive than automated. Processing time typically runs 45 to 60 days from application to closing, compared to 30 to 45 days for an automated approval. The reason is that manual reviews require more document requests, more back-and-forth, and a human actually reading and interpreting your file rather than running it through a decision tree. Each request for additional documentation adds several days to the timeline. Lenders often charge an additional underwriting fee for manual review, sometimes between $500 and $1,500 on top of standard closing costs. Not every lender charges this explicitly. Some bake it into their pricing. You should ask before applying whether a manual underwriting fee applies. If a lender says they don't charge extra, verify that they aren't offsetting it with a higher interest rate, which is another common way lenders recover the additional processing cost. Interest rates for manual underwriting loans are typically slightly higher than the best-qualified rates available through automated underwriting. The difference is usually 0.125 to 0.375 percent, though this varies by lender and market conditions. A borrower with excellent credit who qualifies for an automated approval under conventional guidelines will almost always get a better rate than a borrower needing manual underwriting through FHA, even if their manual file is strong. That's the tradeoff: access versus price.
Pitfalls That Derail Manual Underwriting Files
The biggest mistake borrowers make is assuming manual underwriting means looser standards across the board. It doesn't. It means more holistic review, not no review. Underwriters are still bound by FHA or VA guidelines. They can exercise discretion within those guidelines, but they cannot approve a loan that violates the program's basic requirements. A borrower who hasn't made minimum payments on their mortgage for six months cannot get an FHA loan through manual underwriting, regardless of how compelling their story is. The rule is three months of delinquency on any housing payment within the past year, and no underwriter will waive that. Another common failure point is incomplete documentation. Borrowers often provide tax returns but forget bank statements for the periods those returns cover. They give pay stubs but not W-2s from the prior two years. They submit a letter explaining a job gap but not proof of what they were doing during that gap. Every gap in the story needs a documented answer. If you were freelance during an employment gap, provide invoices or 1099s. If you were caring for a family member, a letter from the patient or their physician is helpful. If you were in school, provide transcripts or enrollment verification. The underwriter needs to see continuity, and they need it on paper. Borrowers also sometimes make the mistake of applying with multiple lenders simultaneously while seeking manual underwriting. Each application generates a hard credit inquiry and creates a new file to review. If your score is already borderline, multiple inquiries can push it down further and complicate the underwriter's assessment. Apply with one lender you trust, build the relationship, and let them guide you through the document process. Rushing to shop around when you need manual underwriting often backfires.
When Manual Underwriting Is the Right Choice
If your credit score is above 680 and your DTI is below 40 percent with clean payment history, you likely don't need manual underwriting. Automated underwriting will approve you faster and cheaper. Manual underwriting is worth the extra time and cost when the automated system would reject you outright or when your financial situation has nuances that a computer can't evaluate. That includes self-employment income with deductions, non-traditional credit histories, recent major life events that affected your finances, or employment gaps with clear explanations. It's also worth considering if you're purchasing a property that doesn't meet certain automated system criteria, such as some condominium projects that aren't on the approved list but have a spot approval from FHA. Or if you're a borrower with seasonal income that averages out well over the year but shows large zero-income months on your pay stubs. The automated system sees the zero months. The manual underwriter averages them. There are situations where manual underwriting simply won't help. If you have a foreclosure less than three years old, a bankruptcy less than two years old, or current delinquencies on any obligation, no amount of documentation will overcome those hard waiting periods under FHA guidelines. In those cases, the advice is straightforward: wait until the waiting period expires, rebuild your credit and payment history during that time, and then apply. There's no workaround for the waiting period, and any lender who promises one is not being honest with you.
Choosing the Right Lender for Manual Underwriting
Not all lenders handle manual underwriting well. Large national lenders often have streamlined processes for it, but they may also have less flexibility because their underwriters follow stricter corporate guidelines. Community banks and credit unions can be more flexible because their underwriters have more discretion and the borrowers tend to have longer relationships with the institution. Online lenders fall somewhere in between, with varying levels of hands-on support. The lender you choose should explain the manual underwriting process upfront, provide a clear checklist of required documents, and give you a realistic timeline. If they can't do that, look elsewhere. The process is document-intensive and communication-heavy. A lender who isn't organized about it will waste your time and potentially cost you money through delayed closings and rate lock extensions.