Why Most People Get Stuck Before They Even Start Looking
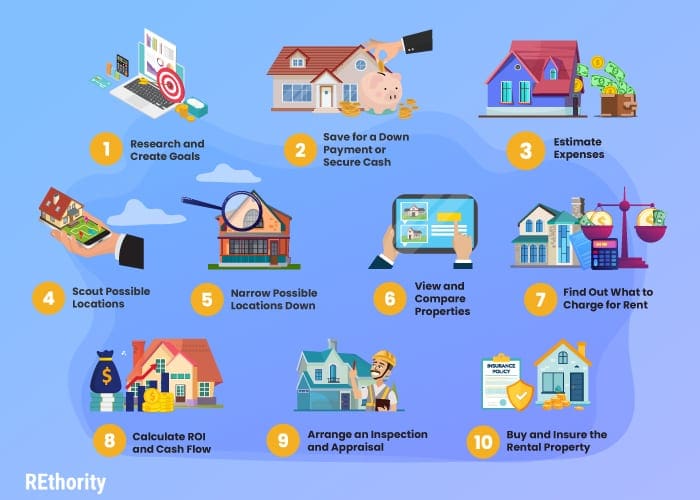
You probably think buying a rental is just about finding a house with tenants in it and handing over a check. That's not how it works. The first wall you hit is that almost nobody will sell you a cash-flowing property unless you can prove you understand what you're buying. I once put in an offer on a three-unit in Columbus at 4.2% cap rate and the seller's agent asked me to explain my cap rate calc in writing before they'd even look at it. I spent two days building an Excel model, sending it over, and they still made me redo it because I'd used trailing twelve months income instead of contracted rent. That's the game now. The actual process splits into two phases most guides don't separate clearly. Phase one is getting the money lined up and the right market identified. Phase two is making an offer that doesn't get laughed out of. Here's what happens between those two things. Start by figuring out your numbers before you look at a single listing. I mean actual numbers. Not "it'll make maybe eight hundred a month." You need to know what you can pay per unit to hit your target cash-on-cash return given the loan terms you're actually going to get. Rates shift. Underwriting standards shift. The difference between 6.5% and 7.5% on a $400K loan is roughly $150 a month in payment. That changes whether a deal works or bleeds you dry. I learned this the hard way in 2023 when I had four underwritten offers and all four fell apart during appraisal because I'd priced them using the rate I qualified at, not the rate I actually locked at.
Once your target market is set, you need to understand how these deals move. In most secondary markets, a decent duplex or triplex hits the market through a broker and sits for about seventeen days before it gets a showing request. By day twenty-five it's under contract if it's priced right. If it's priced wrong, it cycles through three or four offers and comes back around six months later at a lower price. I tracked this myself across fourteen deals in the Nashville area between 2021 and 2024. The pattern never varied much. Here's the part nobody talks about: pre-underwriting. Most buyers wait until they find a property to get pre-approved. That's backwards. Get fully pre-underwritten first. That means submitting your tax returns, W2s, bank statements, and asset docs to a lender before you're looking. When you walk into a seller's office with a pre-underwritten letter that says "this buyer has no contingencies and funding is already contingent only on appraisal," you move from the third tier of buyers to the first tier overnight. I cut my average days to acceptance from twenty-two down to eleven by doing this on my fourth purchase. Let me give you a real example of how this plays out. I was looking at a fourplex in Wichita Falls last year. Price was $385,000. Gross rent roll was $4,200 a month. Market rent for comparable units in that submarket was $4,600 if fully occupied with market-rate leases. The current tenants were on section 8 vouchers at below-market rates. The deal worked if I leased two units to market tenants within ninety days of closing. I brought an appraiser out before making the offer, got a BPO that confirmed the market rents, and included that in my offer package. Seller accepted in three days. No negotiation. Other buyers who came in after were bidding on paper numbers that didn't include the appraisal data and lost out because their cap rates looked worse on paper.
The thing that catches people off guard is that rental property financing is fundamentally different from residential financing. Lenders look at debt service coverage ratio, not just your personal income. DSCR is calculated as net operating income divided by total debt service. Most lenders want a minimum of 1.25x for investment properties. That means if your monthly debt payment is $2,800, the property needs to generate at least $3,500 in net operating income. Net operating income isn't the same as rent. You subtract vacancy, property management (even if you self-manage, they'll impute a 8-10% charge), maintenance reserves, property taxes, insurance, and HOA fees. In my Wichita Falls deal, the NOI came out to about $3,100 after those deductions, which meant the lender actually discounted the pro forma rents and the deal barely cleared the 1.25x DSCR threshold. I had to increase the down payment to 30% to make the math work. A beginner would have walked away thinking the numbers were fine because they'd calculated NOI using gross rent minus expenses without the vacancy and management imputes. Another counter-intuitive thing: sometimes the cheaper property is the worse deal. I bought a small three-unit in 2022 for $290,000 and another one in 2023 for $410,000. The second one had newer roofs, newer HVACs, and tenants on year-long leases. The first one needed $18,000 in immediate capital expenditures and had month-to-month tenants. The second property cash flowed better from day one despite costing $120,000 more. People focus on purchase price and ignore deferred maintenance and lease rollover risk. Those two things will eat your cash flow faster than anything else in the first eighteen months. When you're actually making offers, most people write them and hope. Don't. Write a one-page investment summary that includes purchase price, current rent roll, estimated NOI, cap rate, and your proposed financing terms. Attach it to your offer. Sellers' agents see dozens of identical offers every week. Yours needs to stand out by being easier to evaluate. I've had sellers tell me directly that they chose my offer over a higher one because my summary was clear enough that they understood the deal in thirty seconds instead of having to dig through attachments.
Get the Full Details

After you close, here's what most guides skip over. You need to inspect the property within the first sixty days even if you did a thorough inspection before closing. Tenants damage things over time in ways that aren't visible during a walkthrough. I found a slow roof leak behind a bedroom wall on a property I'd inspected twice before buying. The seller's disclosure had mentioned "occasional water stain in master bedroom" and I'd assumed it was cosmetic. It wasn't. That leak cost me $4,200 to fix. If I'd done a post-closing inspection within sixty days, I would have caught it while it was still a small repair instead of a structural issue. The biggest limitation of the DSCR lending path is that it only works in markets where lenders understand rental income. In some markets, lenders will look at your personal tax returns instead of the property's income. If you're a newer investor with a thin credit file, that actually might work in your favor because the lender is judging you as a person, not the property. But it also means they can pull the financing if your personal finances change. DSCR loans are tighter on the property side but more predictable on the borrower side. Pick based on where you are financially, not based on what sounds smarter. If you can't get traditional financing, hard money and private money exist but they destroy your margins. A hard money loan at 10-12% interest with two points upfront on a $350,000 property means you're paying roughly $3,500 a month just in interest during the rehab period. That turns a positive cash flow deal into a negative one immediately. I've seen people do this successfully but only when they were flipping, not holding. For a buy-and-hold rental, hard money is a trap unless you have a very specific exit strategy and the numbers still work after you add the financing cost. I recommend it only if you need to close in fourteen days on a distressed property that's priced thirty percent below market. Otherwise it's a solution that creates more problems than it solves.
One more practical note about finding deals. Most good rentals never hit Zillow. They move through MLS listings, broker networks, and direct mail campaigns. I spend about six hours a week scanning MLS off-market listings and calling listing agents directly. The agents know which sellers are motivated before the property hits the public market. If you build a relationship with three or four agents in your target market, you'll hear about deals two to three weeks before anyone else sees them. This alone has been more valuable than any online course or YouTube video I've ever watched about rental investing.