Getting Money for a Company Is Mostly Paperwork and Patience
The people who actually get funded usually aren't the ones with the flashiest pitch decks. They're the ones whose financials don't make a loan officer put their glasses down and stare at the ceiling. I spent eight years running a small manufacturing operation before pivoting into consulting, and during that time I navigated every major funding route there is—SBA loans, venture debt, revenue-based financing, angel money, you name it. The difference between getting approved and getting ignored often comes down to things nobody tells you about until after the rejection letter arrives. Let's talk about SBA 7(a) loans first since they're the most common entry point. The SBA guarantees a portion of the loan, which makes banks more willing to lend to businesses that wouldn't qualify for conventional financing. You're looking at up to $5 million for working capital or equipment. The application goes through individual lenders—most community banks and credit unions handle them regularly. Processing time runs anywhere from 30 to 90 days depending on how complete your package is. Lenders want to see two years of tax returns, year-to-date profit and loss statements, a detailed business plan with projections, and personal financial statements from every owner with 20% or more stake. That last point catches people off guard. If you and a co-founder each own 30%, both of you are submitting personal financials. The lender is evaluating your net worth and liquidity, not just the business. I had a client once who was denied because his personal debt-to-income ratio was 41%, even though his business was profitable and cash-flowing. He ended up restructuring a car loan and a credit card balance down to 31%, reapplying three months later, and got approved for $750,000. The SBA guideline is typically 40% or below, but some lenders are stricter. It's not a single standard.
How To Get Capital For A Business: Starting With the Right Path
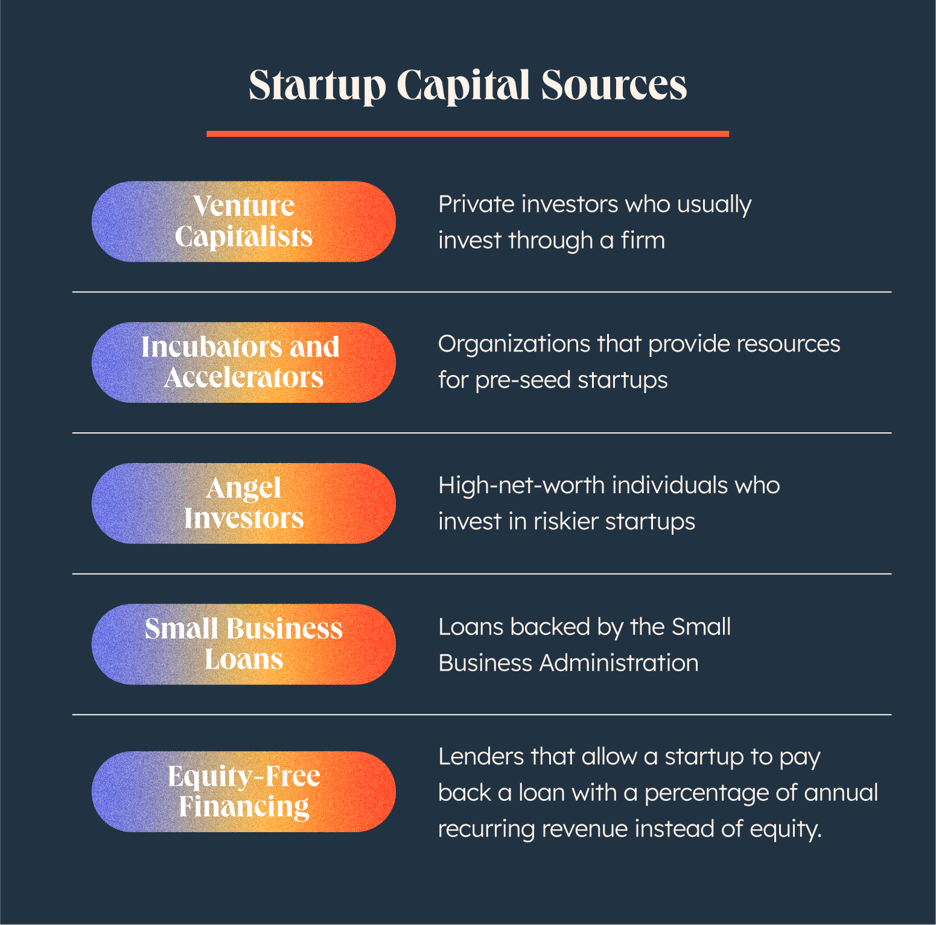
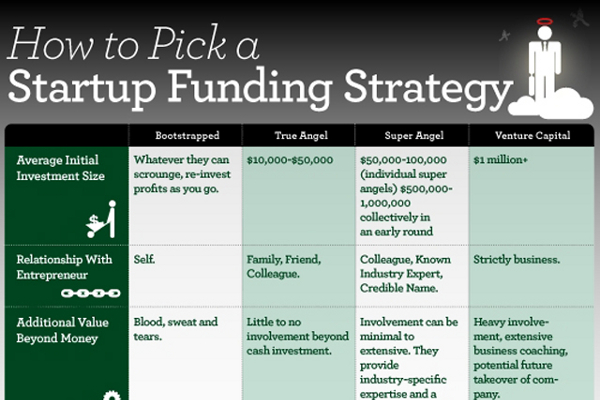
Before you apply for anything, figure out what kind of business you have and what stage it's at. A pre-revenue tech startup and a five-year-old restaurant have completely different funding landscapes. Pre-revenue companies almost never qualify for traditional bank loans. You're looking at angel investors, seed funds, or grants. Established businesses with steady revenue can access term loans, lines of credit, invoice factoring, merchant cash advances, and equipment financing. The mistake I see constantly is founders applying for bank loans when their business model doesn't fit what banks underwrite. Banks want predictable cash flow, tangible assets as collateral, and low risk. If you're selling subscription software with negative churn but no hard assets, a bank isn't your lane. Revenue-based financing has become a serious option over the last five years. Companies like Clearco, Fundbox, and Capchase give you capital in exchange for a percentage of your daily or weekly revenue until a agreed-upon cap is reached, usually 1.1 to 1.4x the original amount. The qualification threshold is lower than a bank loan—you typically need $50,000 to $100,000 in annual revenue and at least six months of operating history. The tradeoff is that it's expensive if you calculate the effective annual percentage rate. A 1.3x factor on $100,000 paid back over six months works out to roughly 26% APR, which is steep but reasonable compared to the 40% to 60% you'd see on some merchant cash advances. I learned this the hard way early on. My first company in 2014 took a merchant cash advance for $50,000 during a cash crunch. The holdback was 20% of daily credit card receipts. In slow months, we were paying back almost half our revenue to the funder. It stretched operations thin for eight months. When I refinance-related questions come up now, I always steer people toward RBF over MCA when the numbers are even close. Angel investors and venture capital are a different beast entirely. Angels invest their own money, usually between $25,000 and $250,000 per deal, and they want equity—typically 10% to 20% at the seed stage. VCs manage other people's money and write larger checks, but they demand much higher growth trajectories. Most seed-stage VCs want 3x to 5x returns within seven years. They're not interested in a profitable consulting firm making $500,000 a year. They want the next platform play that could scale to $100 million in revenue. If you're building something that can't scale massively, angel investors or self-funding are more realistic than VC.
Here's something that frustrates me every time I explain it: most people don't understand the difference between equity and debt when it comes to valuation impact. Taking $200,000 from an angel investor at a $1 million pre-money valuation means giving up 16.7% of your company. That 16.7% compounds through every future round. By the time you do a Series A, that original angel stake might represent 8% of a much larger pool, but you've already lost a significant ownership chunk. Debt, on the other hand, doesn't dilute ownership at all. A $200,000 SBA loan at 7% over ten years costs you about $2,900 a month in payments and nothing else ownership-wise. For businesses that are already profitable and don't need to grow at hyper speed, debt is almost always the better financial decision. I told a restaurant owner this once and she laughed because she'd just given away 25% of her business to an angel who then wanted a seat on the board and veto power over vendor contracts. She was paying 7% interest to a bank and also answering to someone who'd never worked a shift in her kitchen.
Get the Full Details
Grants and Alternative Sources That Don't Require Repayment
Grants are genuinely underutilized. The SBA doesn't offer direct grants for starting a business, but the Small Business Innovation Research program and state-level economic development grants do exist. SBIR grants go to tech-focused small businesses doing R&D, and they're competitive but the money doesn't need to be paid back. Phase I awards run $50,000 to $275,000, Phase II goes up to $1.8 million. If your business involves any research component—biotech, clean energy, advanced materials—you should be applying. The rejection rate is high, around 70% for Phase I, but the application process itself forces you to clarify your value proposition in a way that helps every other funding application you submit. Local economic development corporations and state grant programs are another angle. Cities and states routinely have funds allocated for job creation, especially in underserved areas. I helped a client in Ohio qualify for a state workforce development grant that covered 50% of new hire wages for two years. That's effectively $40,000 to $60,000 in reduced labor cost depending on headcount. The application required documentation of hiring plans, wage levels, and a business impact statement. Took about three weeks to compile and another six weeks to hear back. Got the approval. These programs fly under the radar because nobody markets them aggressively to business owners.
Credit Building and the Foundation Nobody Talks About
Before you can secure any meaningful capital, you need business credit separate from your personal credit. This is where most founders stumble. A DUNS number from Dun & Bradstreet is free and takes about 30 minutes to set up. From there, you open accounts with vendors that report to business credit bureaus—Uline, Quill,Grainger, certain fuel cards. These are trade lines, not loans, and they build your Paydex score. A Paydex of 75 or above is generally the floor for loan eligibility. I watched a friend spend two years trying to get a business line of credit while his Paydex sat at 58 because he'd been paying everything personally and never established trade credit. Once he opened five vendor accounts and kept balances under 30% utilization, his score jumped to 82 in four months and he qualified for a $150,000 line the following month. The interest rate was 9.5% variable, which was acceptable for the purpose. Personal credit still matters enormously for small business financing. Most lenders pull personal credit scores for owners with 20% or more ownership. A score below 640 significantly limits your options and increases your cost of capital. A score above 720 opens up the best rates. If your personal credit is damaged, you have two paths: fix it before applying, or find lenders who specialize in non-prime business lending. The second option exists but the rates will be higher. Some online lenders like OnDeck and Funding Circle evaluate applications using a combination of personal credit, bank statement analysis, and business revenue trends rather than relying solely on FICO scores. They're more accessible but the cost of capital is meaningfully higher—an OnDeck term loan for $50,000 might carry a factor rate of 1.3, which translates to roughly $65,000 repaid over 12 months.
A Reality Check on What Funding Actually Feels Like
The process of securing capital is exhausting and repetitive. Every application asks the same questions in slightly different formats. You'll submit the same tax returns, bank statements, and business plan to five different lenders. Each one will ask for additional documentation that wasn't requested by the previous lender. I once spent four hours gathering documents for an SBA application, submitted it, and then the lender asked for three more items that were technically included in the original packet but organized differently. It's bureaucratic by design. The lenders are managing risk and the paperwork is their evidence trail. Your job is to make it as easy as possible for them to say yes. One specific edge case I encountered: a client was turning down an SBA loan because the property he needed to lease for his business wasn't in his name and the landlord wouldn't sign a triple-net lease assignment. The SBA requires either ownership of the collateral property or a lease that meets specific terms. His solution was to negotiate a 10-year lease with an option to renew and a clause allowing lease assignments to lenders. He presented this to the SBA-approved lender, who accepted it after a 48-hour review. The loan closed 90 days after initial application. Without that lease amendment, he would have been stuck. This is the kind of detail that separates people who get funded from people who get stuck in limbo. Another thing worth noting: the timing of your funding request matters more than most people realize. Applying in October or November puts you in front of lenders who have unfcommitted SBA guarantee pool capacity from the prior fiscal year. Lenders are motivated to deploy those guarantees before they expire. Applications submitted in January through March face tighter scrutiny because lenders are conserving capacity for the new fiscal year. This isn't a hard rule but it's a pattern I've observed consistently across multiple years and multiple clients.

If your business generates consistent monthly revenue above $15,000, invoice factoring or revenue-based financing might be the fastest route to capital. Invoice factoring advances up to 90% of outstanding invoices within 24 to 48 hours. The factor charges between 1% and 5% of the invoice value depending on terms and your customers' creditworthiness. It's expensive but it solves a specific problem—cash flow gaps caused by net-60 or net-90 payment terms from larger clients. I've seen businesses use factoring to bridge the gap between delivering work and getting paid, then use the improved cash flow to take on more contracts and eventually qualify for a traditional loan with stronger financials. The bottom line is that capital acquisition is a function of preparation, not persuasion. A well-organized financial package with clear documentation will move faster and get better terms than a compelling story with messy books. Track your revenue, maintain clean records, build business credit early, and understand which funding vehicle matches your business model before you need the money. Waiting until you're desperate to explore options guarantees you'll accept worse terms or get rejected outright.