The Mechanics of Getting Out of Credit Card Debt
Most people never get out of credit card debt because they focus on the wrong metric. They obsess over minimum payments or try to pay down the highest balance first without understanding how interest actually compounds. The math doesn't care about your feelings. It cares about the order in which dollars leave your account and which balances accrue interest in the meantime. I've watched friends throw themselves at this problem for years using methods they found on YouTube without understanding the underlying mechanics. One of them, Mike, had about $23,000 in credit card debt across four cards. He was paying the minimum on each one religiously. At his average APR of 22%, he was paying roughly $400 a month in interest alone and barely touching principal. That's not an unusual situation. It's the default setting most people are born into.
How To Get Out Of Credit Card Debt: The Balance Transfer Play
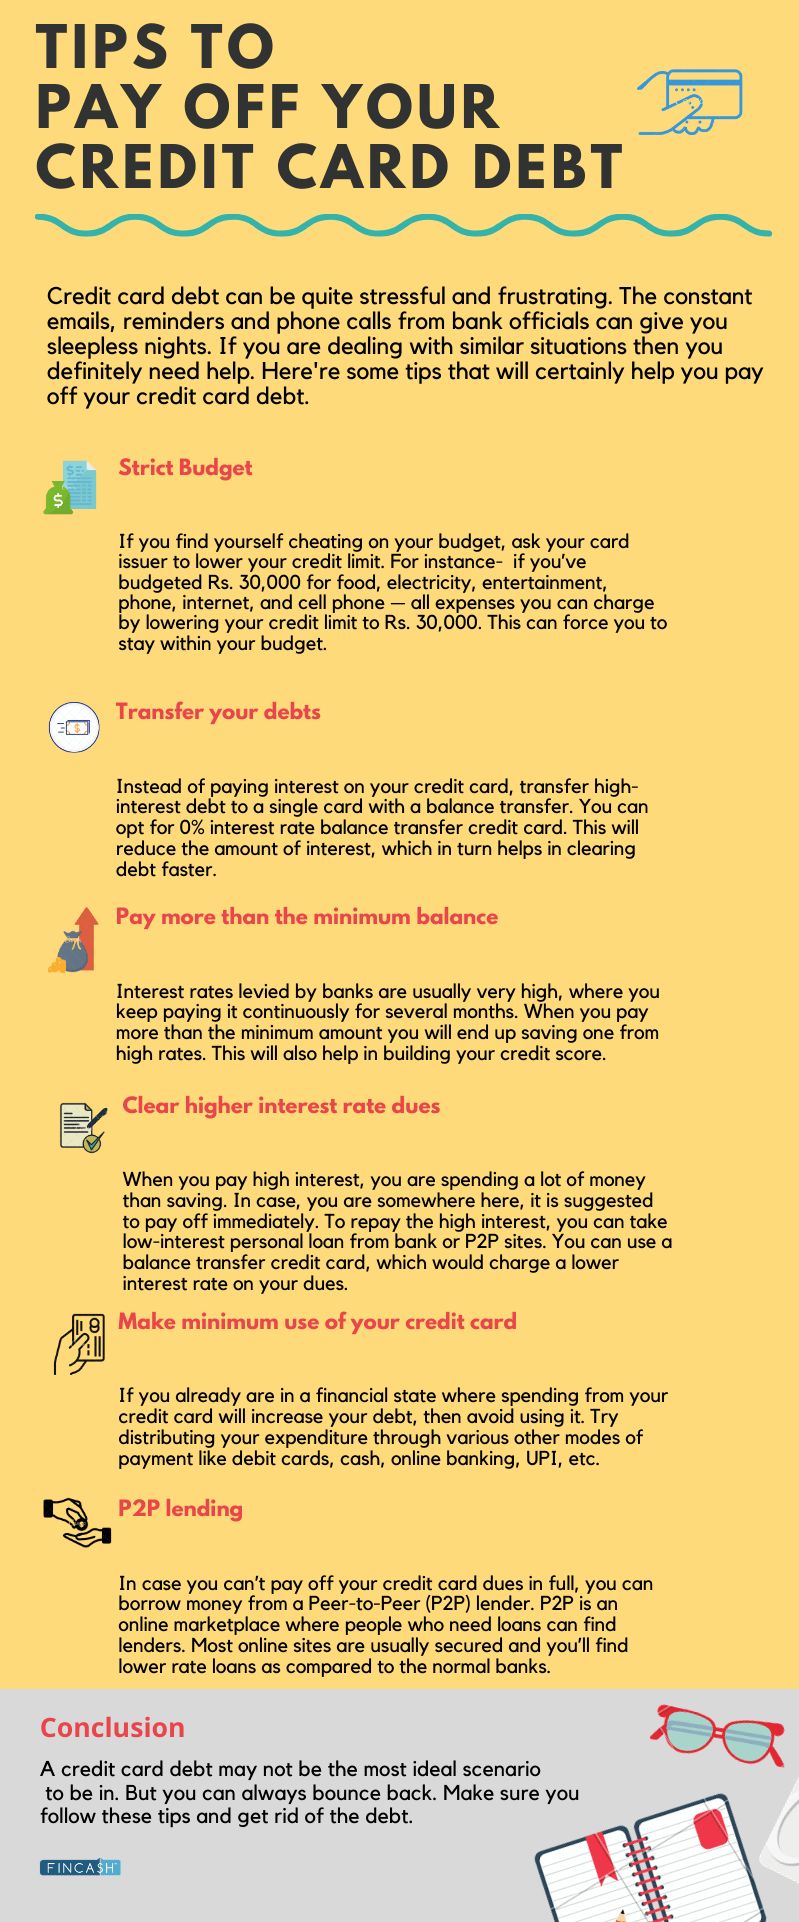
The single most effective tool for someone in the $5,000 to $30,000 range is a balance transfer to a 0% APR card. This stops the compounding machine dead in its tracks. Instead of paying 20% a year, you're paying zero. The money that would have gone to interest now goes to principal. On a $15,000 balance, that's potentially $2,500 to $3,500 saved per year depending on your rate and timeline. The catch is the balance transfer fee. Most cards charge 3% to 5%. So transferring $15,000 costs you $450 to $750 upfront. Even with that fee, you're usually ahead if you can pay it off within the promotional window, which is typically 15 to 21 months. Do the quick math yourself: total interest you'd pay normally versus the transfer fee plus whatever interest you'd pay after the promo period ends if there's a remaining balance. Here's something most people don't know: balance transfer apps aren't the only path. Many credit unions now offer balance transfer CDs or personal loans specifically for this purpose at rates around 8% to 12%. It's not free interest like a 0% transfer, but it's dramatically cheaper than carrying a 22% APR. The advantage of the loan route is there's no hard deadline. You pay it off on your own schedule over two to five years instead of racing against a promotional clock.
The Avalanche Method vs The Snowball Method: What Actually Works
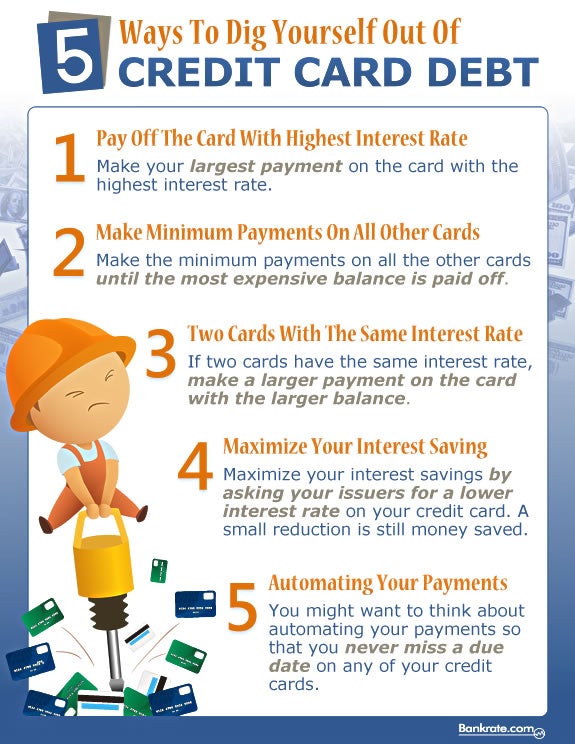
The avalanche method targets highest-APR debt first while making minimum payments on everything else. The snowball method targets smallest balance first. Both work mathematically and psychologically. The avalanche saves more money. The snowball builds momentum. I recommend the avalanche unless you're the type who needs visible wins to keep going. I learned this the hard way when I tried to combine both strategies at once. I was paying down my smallest card first for the psychological boost while also trying to maximize savings by targeting high-rate debt. The result was I was making fragmented payments that didn't move the needle on either front meaningfully. I consolidated into a single priority order and got unstuck within six months. The key insight nobody talks about is that the order of payment doesn't matter nearly as much as the total amount you throw at debt each month. Paying an extra $200 a month toward any debt matters more than which specific debt you target. $200 extra per month on $15,000 in debt at 20% APR cuts the payoff time from roughly seven years to about three years. That difference is more impactful than choosing between avalanche and snowball.
Get the Full Details
The Hard Parts Nobody Warns You About
The biggest obstacle to getting out of credit card debt isn't the math. It's the behavioral side. Once you clear one card, the temptation to use it again is real. I've seen people pay off $8,000 in two years only to rack up another $6,000 on the now-open card within six months. The debt didn't go away. It just restarted with a higher limit. Another problem that catches people off guard is the grace period trap. If you carry a balance on any card, you lose your grace period on all cards linked to the same issuer under certain conditions. This means new purchases start accruing interest immediately. I learned this when I was paying down a card from one bank while still using another card from the same bank for everyday purchases. The interest calculation got messy and I lost track of what was actually accruing versus what was interest-free. Debt settlement sounds like a shortcut but it's usually a trap. You stop paying, the account goes to collections, and a company offers to settle for less than you owe. They'll take 15% to 25% of the settled amount as their fee. Your credit score takes a massive hit that lasts seven years. The settled amount may also be counted as taxable income by the IRS. For $10,000 in debt, you might end up owing $7,000 to the creditor plus $1,500 to the settlement company plus taxes on the forgiven $3,000. That's $10,500 to resolve a $10,000 problem.
When You're Deep Under and Need Options
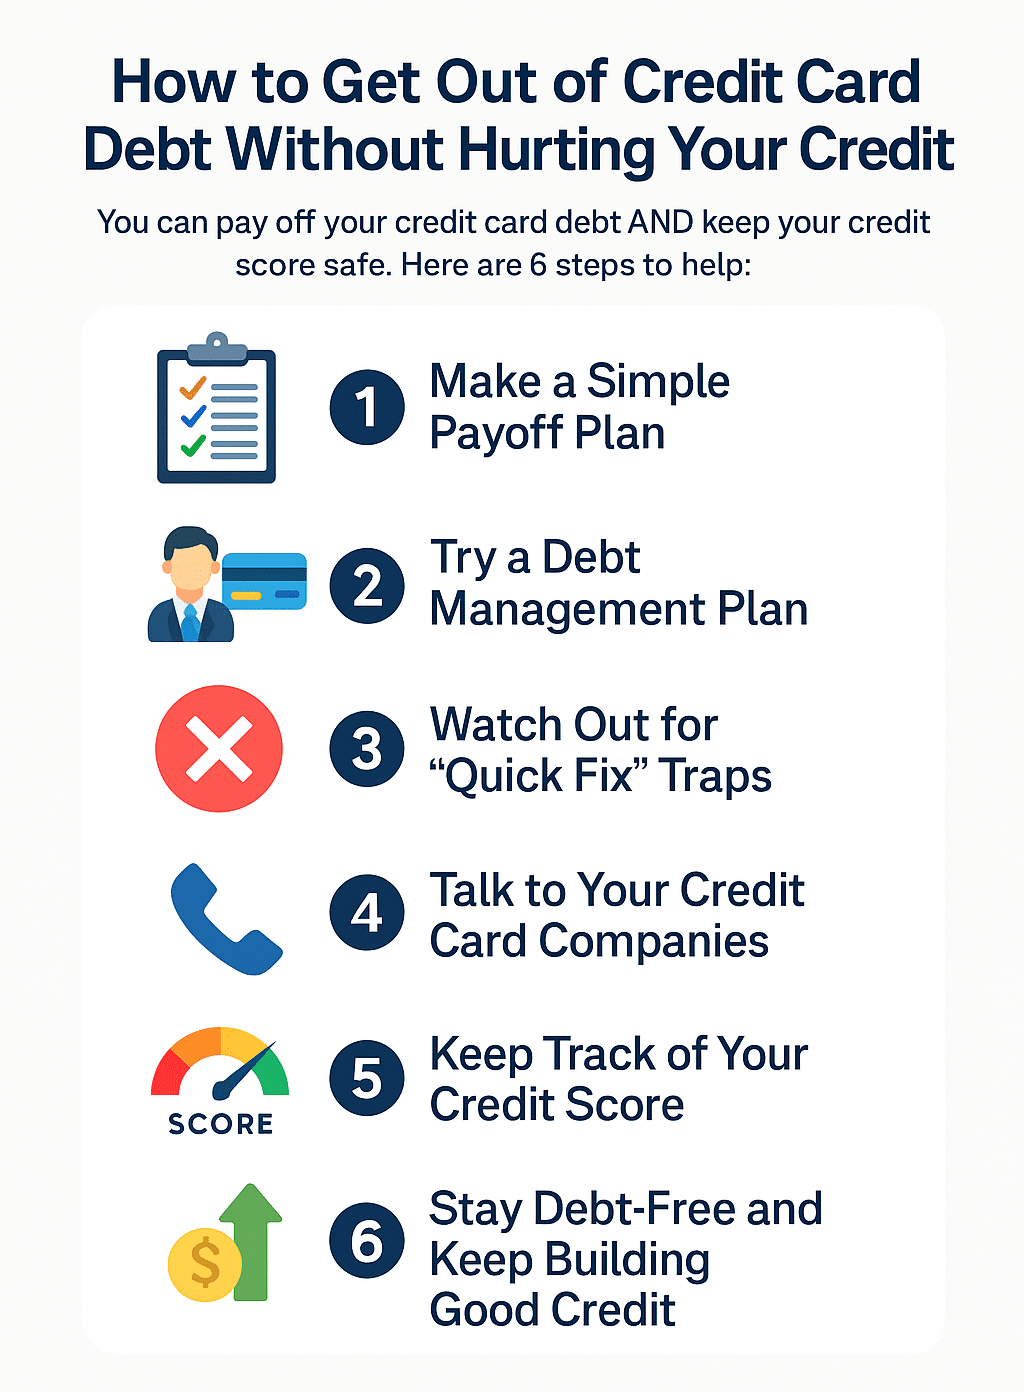
If you're looking into How To Get Out Of Credit Card Debt and the numbers are overwhelming, there are structured paths that don't involve bankruptcy. Debt management plans through nonprofit credit counseling agencies can reduce your APRs by negotiating with creditors. They typically lower rates from 20% down to 8% to 12%. The tradeoff is you can't open new credit and you must make monthly payments through the agency for three to five years. A debt consolidation loan from a bank or online lender can simplify multiple payments into one. The best rates available right now hover around 7% to 10% for good credit. If your credit score is below 620, you're unlikely to qualify for rates that make sense compared to your current cards. In that scenario, a balance transfer card or debt management plan is usually the better starting point. The worst case is bankruptcy. Chapter 7 wipes out unsecured debt including credit cards but stays on your credit report for ten years. Chapter 13 restructures debt into a three to five year payment plan. Most people who file don't need to. The combinations of balance transfers, consolidation loans, and negotiated rate reductions solve the problem for the vast majority of people carrying credit card debt.
What Actually Moves the Needle
Increase your monthly payment amount. This is the single most impactful action. If you're paying $300 a month and can bump it to $500, you'll be debt-free significantly sooner with far less total interest paid. Find the extra $200 from somewhere: a side job, selling things you don't need, cutting subscriptions, cooking at home instead of ordering out. The specific source doesn't matter. The extra amount matters. Stop adding new debt. This sounds obvious but it's where most plans fall apart. Every new charge on a card you're trying to pay off is like pouring water into a bucket while simultaneously bailing it out. Close the accounts after you pay them off or freeze them in a block of ice in your freezer if you have to. The physical barrier helps more than you'd expect. Track your progress monthly. Set up a simple spreadsheet or use a free app like EveryDollar or Mint. Seeing the balance drop quarter by quarter provides the feedback loop your brain needs to stay committed. Without visibility, it's easy to lose motivation because the numbers feel abstract.
The process is straightforward in theory and genuinely difficult in practice. The difficulty isn't in the strategy. It's in the daily discipline of not adding charges and consistently directing every spare dollar toward the balance. If you can maintain that for eighteen to twenty-four months, you will have changed your financial trajectory permanently.