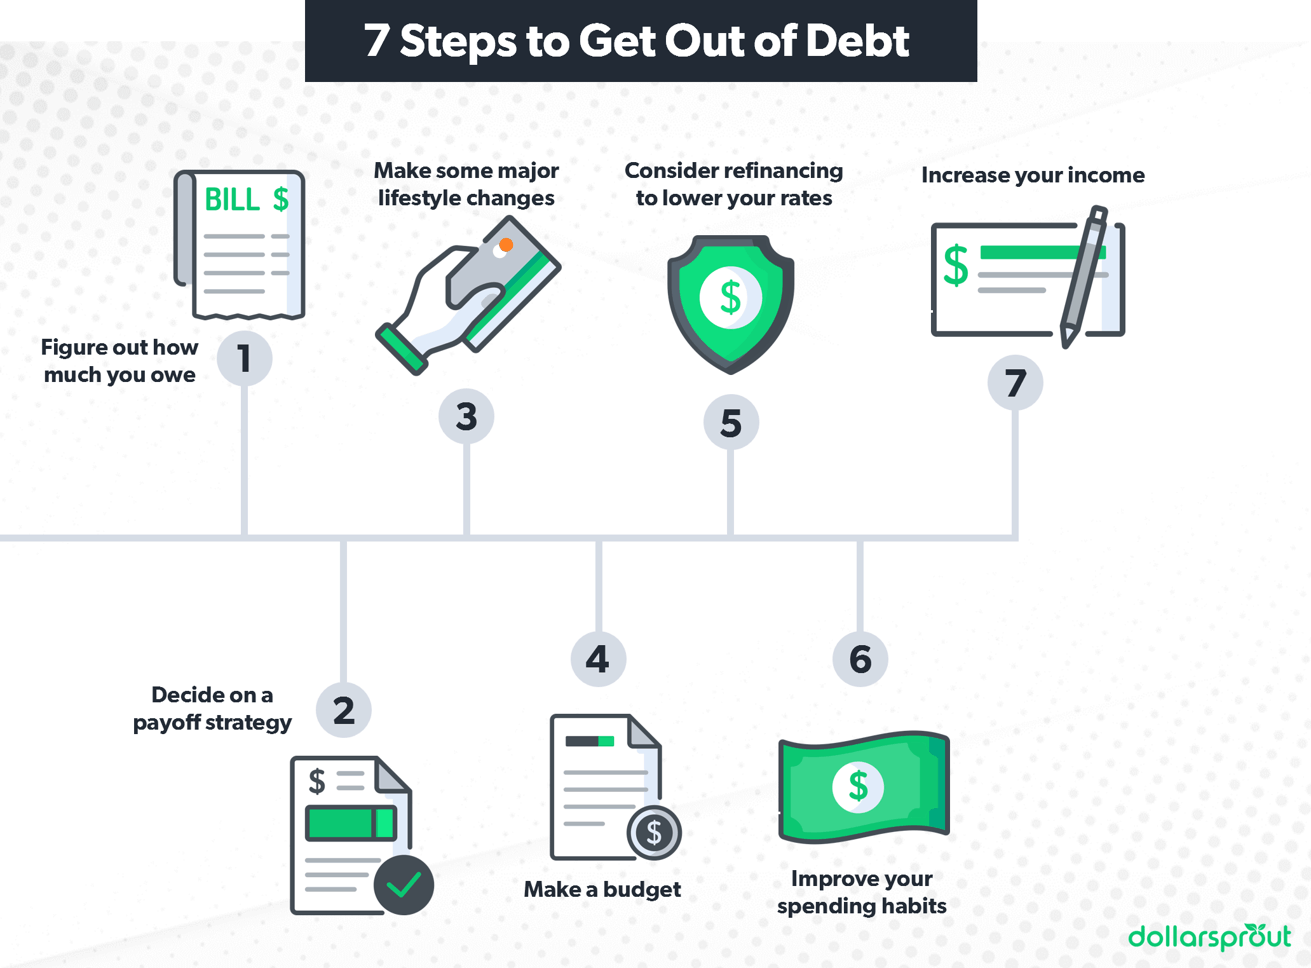
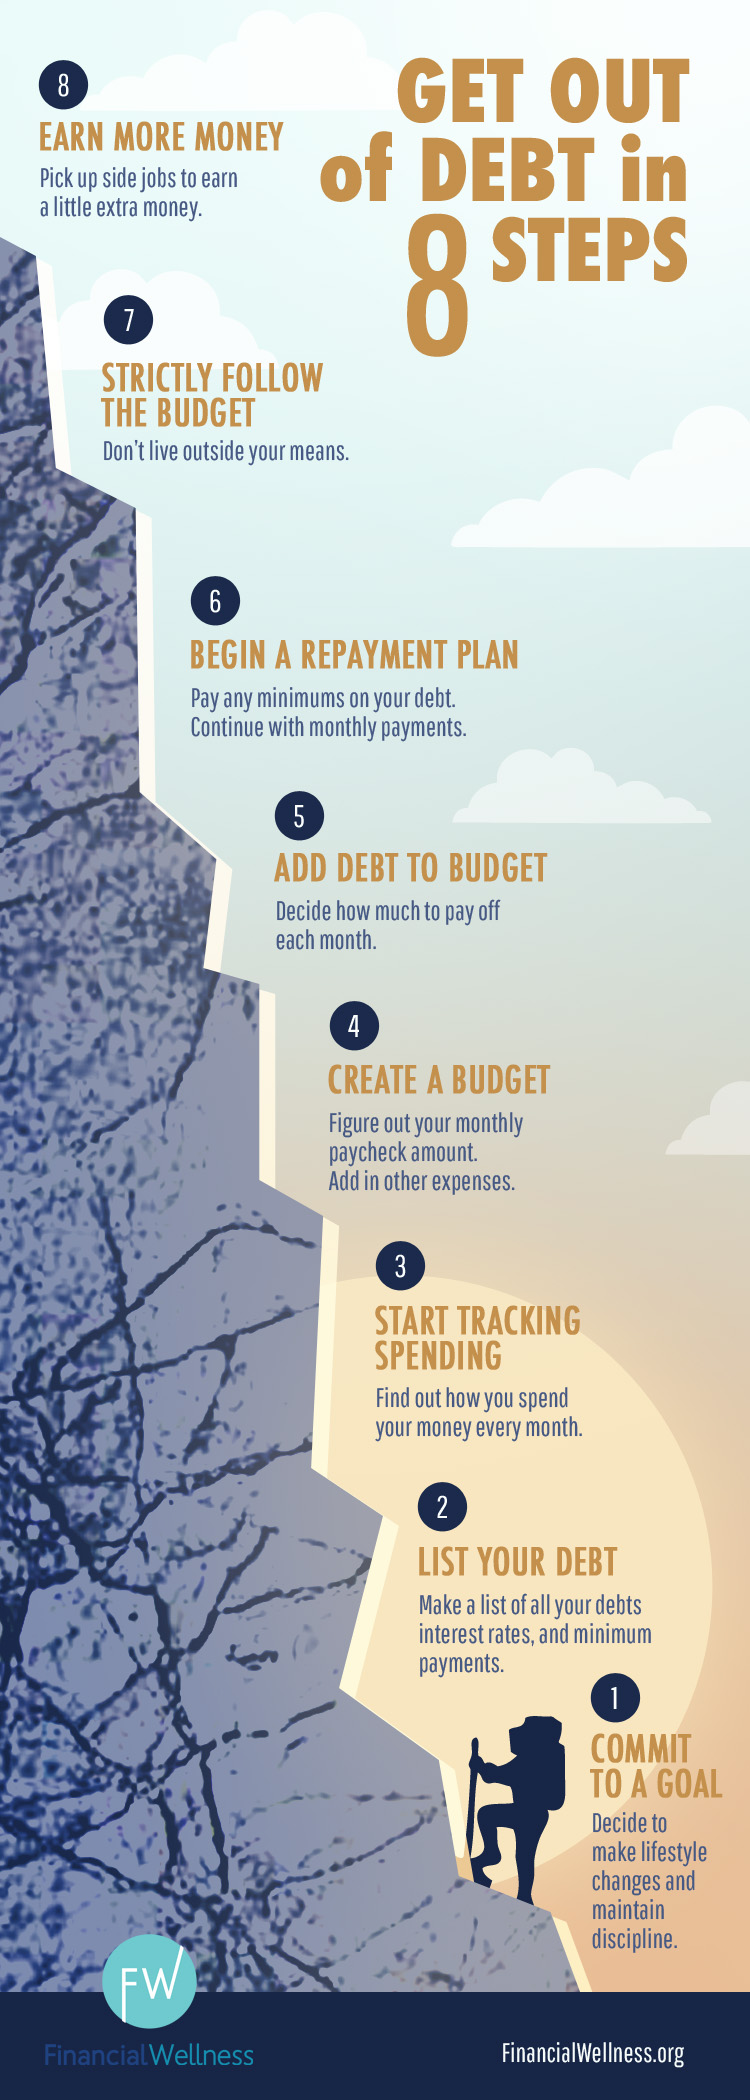
Getting out of debt isn't about willpower, it's about math and friction
I spent six years carrying about forty-two thousand dollars in consumer debt before I figured out how to kill it in eighteen months. The problem wasn't that I didn't have income. I made decent money. The problem was that I had structured my debts in the most expensive configuration possible and I didn't understand the mechanics well enough to rearrange them. Most people don't. Here's what actually moves the needle.
How To Get Out Of Debt Quickly requires understanding your debt geometry first
Before you pick a strategy, you need a complete picture of every obligation. Not the minimum payments. The full numbers: principal balance, interest rate, monthly minimum, and remaining term. Put it in a spreadsheet. If you can't locate a statement for one of them, call the lender and get it. I had a student loan servicer that hadn't reported my balance correctly since 2018, and I only found out because I was cross-referencing my own records against the official numbers. They owed me nearly two thousand dollars in adjusted principal that I hadn't been credited for. Fixing that alone shaved fourteen months off my payoff timeline.
There are two legitimate strategies and one hybrid that works for most people.
The avalanche method targets the highest interest rate first while maintaining minimum payments on everything else. It is mathematically optimal. Every dollar you throw at debt faster than the rate it's compounding costs you. If you have a credit card at twenty-four percent and a personal loan at eight percent, throwing extra money at the personal loan is financially stupid. It sounds counterintuitive if you've been culturally conditioned to believe that paying off small balances first builds momentum, but momentum is not a financial concept. Interest is.
The snowball method targets the smallest balance first. It has psychological value. Closing an account gives you a tangible win, and that win can sustain behavior change for people who struggle with motivation. The cost is real. You'll pay more in total interest over the life of the debt. For most people I work with, the avalanche is the better choice because the psychological boost of a snowball usually fades after the first two or three accounts close, and then you're back to where you started, just with higher balances and the same habits.
The hybrid I use with clients who are genuinely struggling to stay on track is called the "ladder snowball." You identify your smallest balance that carries the highest interest rate and attack that first. It gives you the psychological hit of closing an account while still prioritizing cost. It's not as mathematically pure as the avalanche, but it's close enough that you won't regret the deviation, and you get the behavioral benefit.
The friction point most people miss is payment timing and automation
I learned this the hard way. I was making extra payments manually on three different credit cards through their online portals. One of them was Chase. I'd log in, navigate to the payment screen, enter the amount, confirm, and move on. It took about four minutes each time. I was doing this three times a week. That's twenty minutes of administrative drag that adds up to an hour a week, forty-eight hours a year. Fourty-eight hours of your life you could have spent earning extra income or actually paying down debt faster if I hadn't been burning it on busywork.
Here's what changed: I set up automatic payments for the minimum on every single account, then I scheduled manual extra payments only on the ones that allowed direct ACH contributions. The rest got a single lump-sum transfer once a month. I stopped treating debt repayment like a daily chore and started treating it like a monthly project. The time savings were immediate and the consistency improved because I removed the decision fatigue of "should I pay extra today?" I just did it on the scheduled date.
This is also where most people fail without realizing it. They set up a system, stick with it for six weeks, then drop it because they got busy or the novelty wore off. The system needs to be low-friction or it will die. Automation isn't cheating. It's infrastructure.
The balance transfer trap
Balance transfer cards with zero percent introductory rates sound like a great idea. They are, if you follow the rules. They are a disaster if you don't.
The standard offer is fifteen to twenty-one months at zero percent, then the rate jumps to something in the twenty-two to twenty-eight percent range. The transfer fee is usually three to five percent of the amount moved. So transferring five thousand dollars costs you one hundred fifty to two hundred fifty dollars upfront. That's real money. You need to actually eliminate the balance before the promotional period ends, or you've just delayed the problem and added a fee to it.
I transferred four thousand dollars from a card at twenty-three percent to a new card at zero percent. The transfer fee was one hundred seventy-five dollars. I paid it off in fourteen months. The savings were approximately nine hundred thirty dollars in interest compared to staying on the original card. Net gain after the fee: seven hundred fifty-five dollars. Not life-changing, but real.
The edge case I ran into: I had a friend who transferred six thousand dollars and then ran up another two thousand on the old card because he felt like he'd "solved" the problem. The promotional rate only applied to the transferred balance. The new charges started accruing interest immediately at twenty-six percent. He ended up paying more than he would have if he'd never touched the balance transfer. The lesson is simple. Close the old card or freeze it in the freezer. I know it sounds dramatic but it works. Literally put it in the freezer so you can't use it on impulse. The visual cue of pulling it out and seeing it frosted over is enough to break the habit loop for most people.
The income side matters more than the expense side for most people
Cutting expenses has a floor. You can only cut so much before you're living in a cardboard box. Earning more does not have a floor unless you impose one on yourself. I doubled my debt repayment speed not by finding extra cuts in my budget but by taking on a second income stream that generated an additional twelve hundred dollars a month after tax. That extra cash went entirely to debt. Every. Single. Month.
The spreadsheet math is straightforward. If you have five thousand dollars in high-interest debt at twenty-four percent, the minimum payment is probably around one hundred twenty-five dollars. Paying only the minimum would take you about six years and cost you nearly four thousand dollars in interest. If you pay three hundred dollars a month instead, you're done in twenty-two months and you save roughly two thousand six hundred dollars in interest. The difference between paying minimum and paying aggressively is the entire structure of your financial future.
I wrote down the exact payoff dates for every account so I could see the calendar shrinking. There's something deeply satisfying about watching a date move from "April 2026" to "January 2026" to "October 2025" on your own spreadsheet. It's not glamorous. It's just data. But data is what changes behavior.
When the avalanche method breaks down
The avalanche method assumes your debts are independent. They usually are. But there are exceptions. Joint debts with a partner who isn't contributing to repayment create a structural problem that no mathematical optimization can solve. I knew someone whose wife had three credit cards in her name totaling eighteen thousand dollars. He was paying his own debts aggressively and asking her to do the same. She wasn't. The relationship strain from arguing about money was causing more financial damage than the interest rates ever would. In that scenario, the best strategy isn't mathematical. It's communicative. Sit down with a neutral third party if you need to. A financial counselor or a therapist who specializes in money conflicts. The debt will still be there when you figure out how to talk about it.
Another edge case: medical debt. Medical debt doesn't always report to credit bureaus the same way other debt does, and it often has different negotiation windows. I had a client with about eleven thousand dollars in medical bills from a hospital stay. The hospital had already written it off to bad debt and sold it to a collection agency for pennies on the dollar. The collection agency was willing to settle for twenty-eight hundred dollars. That's a seventy-five percent reduction. Most people don't know this exists. They pay the full amount or they ignore it and hope it goes away. It doesn't go away. It gets sold again and again. But the agencies are desperate to collect because they bought it cheap. Negotiate hard.
The timeline question everyone asks
There is no universal answer. It depends on your total debt, your interest rates, your income, and your willingness to make temporary sacrifices. I've seen people clear ten thousand dollars in eighteen months with a moderate income and a second job. I've also seen people carry thirty thousand dollars for a decade because they kept refinancing instead of reducing principal. The difference is almost always behavioral, not mathematical.
If you have less than five thousand dollars in high-interest debt, you can probably clear it in six to twelve months with focused effort. Five to fifteen thousand typically takes one to three years. More than fifteen thousand and you're looking at a multi-year project unless your income is substantially above your expenses.
The single most effective action you can take right now is not a strategy. It's a number. Calculate your debt-to-income ratio. If it's above forty percent, you're in danger zone territory. Above sixty percent, you need immediate structural changes, not incremental tweaks. Below twenty percent, you're manageable but probably not optimized.
Stop reading and open a spreadsheet. Write down every balance, every rate, every minimum payment. Do it today. The people who actually get out of debt are the ones who start with honest numbers instead of hopeful guesses.
Gallery How To Get Out Of Debt Quickly
How to Get Out of Debt: A Step-by-Step Guide for 2024
How To Get Out Of Debt With These 5 Tips | How to get rid of debt, How ...
How to Get Out of Debt | Advance America
8 Ways To Get Out Of Debt
30 Best Tips To Get Out Of Debt Now | Debt checklist, Get rid of debt ...