Understanding Retained Earnings in Practice
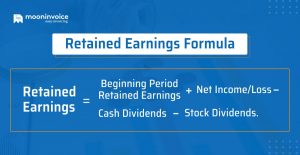
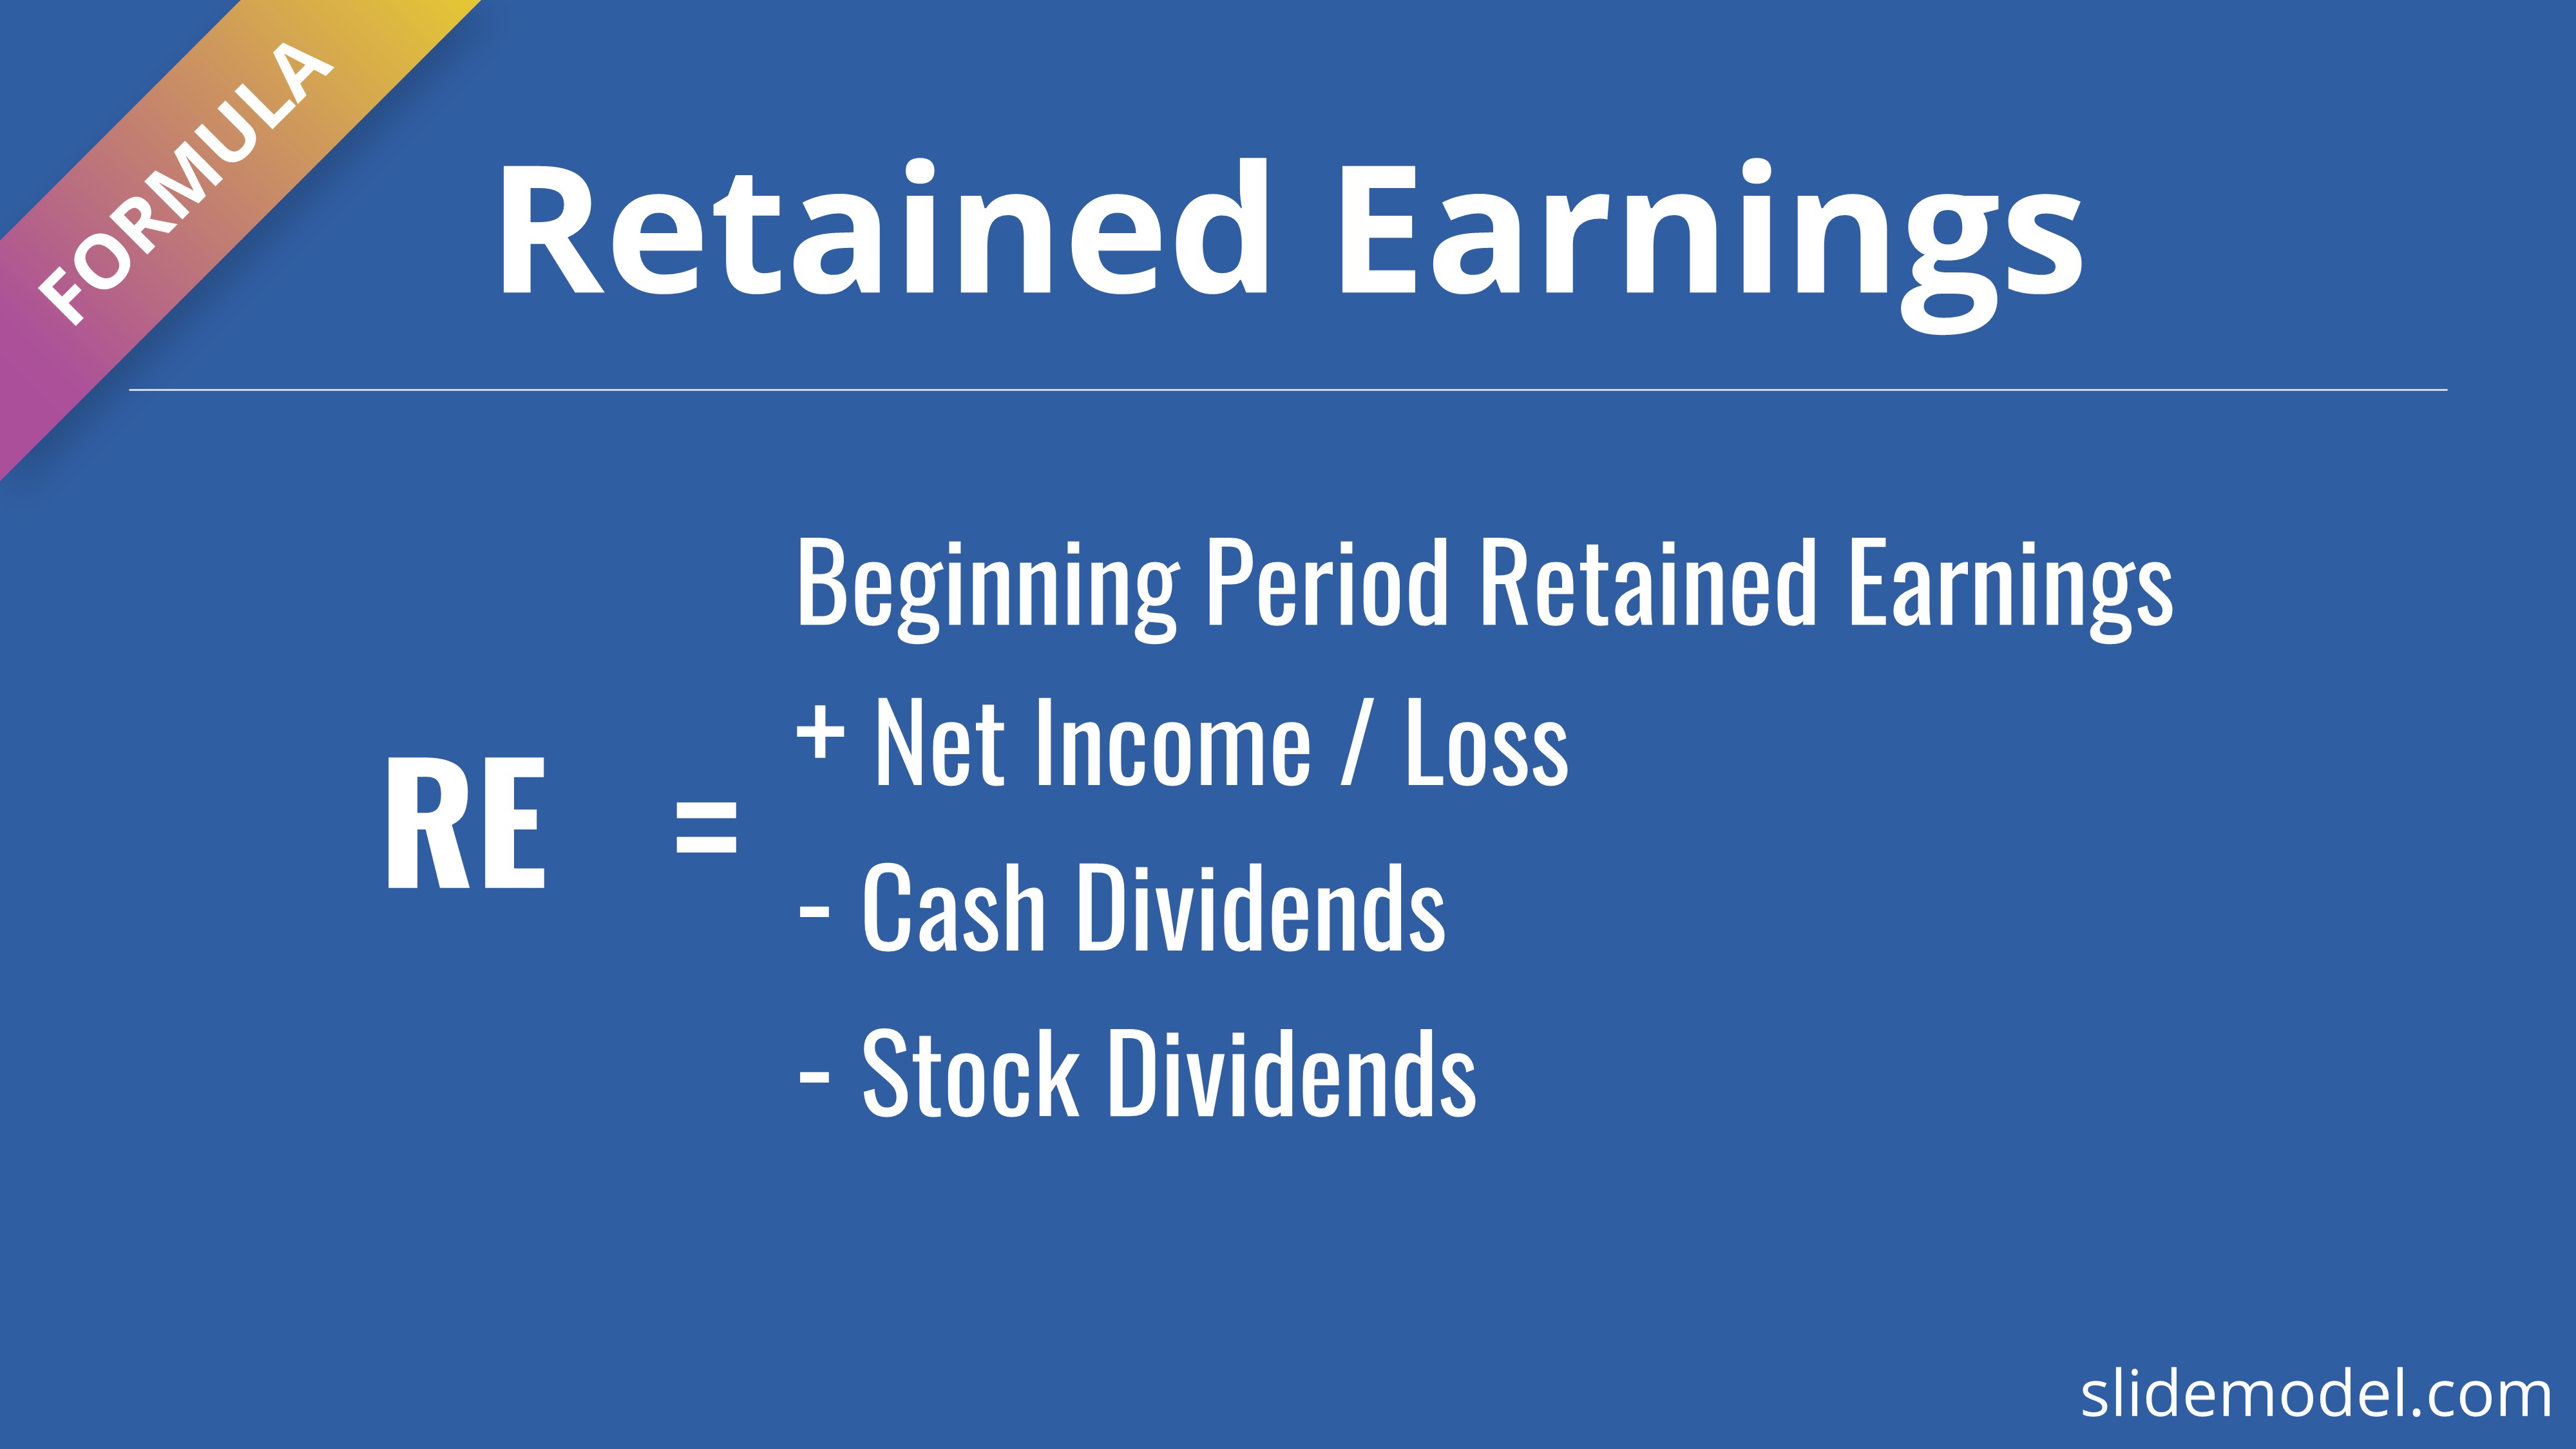
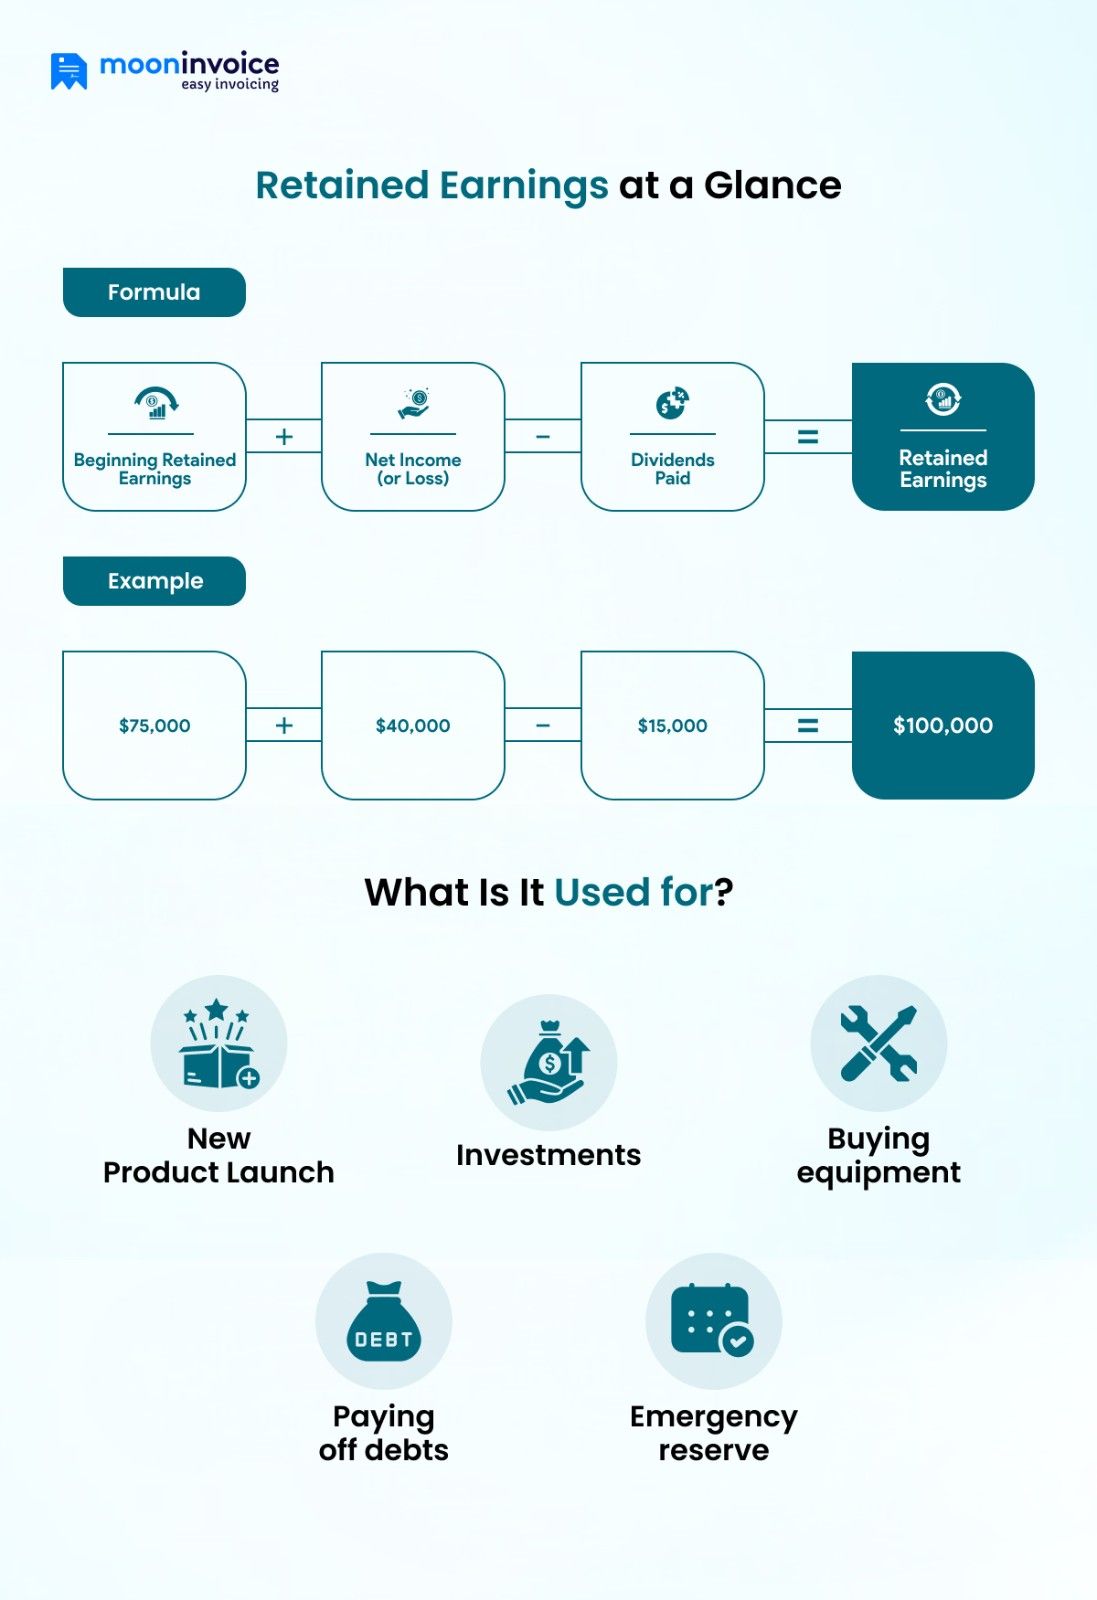
Retained earnings show what a company has kept from its cumulative net income after paying out dividends to shareholders. This figure lives on the balance sheet under shareholders' equity and it matters more than most people give it credit for. When you understand it properly, it tells you whether a business is actually building financial cushion or quietly eating away at its own foundation over time. The calculation itself is simpler than the confusion around it. You start with the retained earnings balance from the previous accounting period, add the current period net income, and subtract any dividends distributed during that same period. The formula is straightforward, but getting it right in practice takes attention to detail. Retained Earnings (Ending) = Retained Earnings (Beginning) + Net Income - Dividends
Here's a concrete example using real numbers. Let's say a small manufacturing company had retained earnings of $240,000 at the start of the fiscal year. During that year, the business earned $68,500 in net income after all expenses and taxes. The owners decided to distribute $15,000 in dividends to shareholders. The ending retained earnings would be $293,500. $240,000 + $68,500 - $15,000 = $293,500 This number then flows into the shareholders' equity section of the balance sheet. It sits between total paid-in capital and total shareholders' equity, and auditors will verify it against the statement of retained earnings or the statement of shareholders' equity, depending on your reporting format.
One thing beginners consistently mess up is the opening balance. If you're pulling retained earnings from last year's balance sheet, make sure that figure already includes the prior year's net income and dividends. Some accounting software handles this automatically. Manual spreadsheets often don't, and you end up double-counting income or skipping a dividend distribution entirely. I've seen this cause mismatches that took an entire afternoon to track down.
Get the Full Details
Where the Process Actually Gets Complicated
The basic formula works fine for most small businesses. Things get messy when you have accumulated deficit situations, foreign currency translation adjustments, or prior period restatements. A company with several years of losses might show a negative retained earnings balance, sometimes called an accumulated deficit. That's perfectly valid on paper, but it creates real constraints on what the business can do going forward. I dealt with a mid-size tech company last year where the retained earnings figure looked fine on the surface, but the actual problem was buried in accumulated other comprehensive income. They had $180,000 in unrealized foreign exchange losses that hadn't been properly separated from retained earnings in their chart of accounts. Their retained earnings showed $340,000 when it should have been closer to $520,000. The discrepancy didn't matter until they applied for a business line of credit, and the lender asked for a detailed reconciliation. The workaround was straightforward but tedious. I pulled the balance sheet from four quarters back, traced everyOCI entry through the general ledger, and rebuilt the retained earnings schedule from scratch. Took about three hours, and the lender accepted the corrected numbers without further questions. Going forward, we set up monthly cross-checks between the balance sheet equity section and the comprehensive income statements to catch these kinds of drifts earlier.
Advanced Considerations That Most People Miss
Retained earnings can be manipulated, though not easily if you're doing proper audit-level work. One common tactic I've seen involves capitalizing expenses that should have been deducted from net income in the period they occurred. If a company spends $50,000 on a marketing campaign but records it as a prepaid asset instead of an expense, net income inflates by $50,000 and retained earnings follows suit. The balance sheet looks healthier than it actually is. Another subtle issue is dividend timing. Some companies declare dividends at the end of a period but don't pay them until the next period. The declaration reduces retained earnings immediately, but the cash doesn't leave the business until later. This creates a temporary increase in current liabilities that can confuse anyone reading only the equity section without checking the full balance sheet. There's also the matter of legal restrictions. Many jurisdictions prevent companies from paying dividends when retained earnings fall below a certain threshold, or when distributions would push the balance into negative territory. Delaware, for instance, ties dividend legality to surplus, which is closely related to but not identical to retained earnings. If you're working across multiple jurisdictions, you need to verify the specific rules for each location your entity operates in.
Practical Steps for Getting It Right
If you're working with a properly set up accounting system like QuickBooks, Xero, or NetSuite, the retained earnings figure should update automatically at period close. The key is running the reconciliation before you consider the period final. Pull the balance sheet, open the statement of retained earnings, and verify that the numbers tie. Any gap larger than a rounding difference means something hasn't posted correctly. For businesses using manual spreadsheets or legacy systems, I recommend building a dedicated retained earnings schedule as a separate worksheet. Include columns for the beginning balance, net income, dividends, any prior period adjustments, and the ending balance. This makes it trivially easy to spot errors and gives auditors exactly what they need without digging through multiple reports. Here's a simple template you can use right now. Download the file here: Retained Earnings Calculator Template. It's an Excel workbook with pre-built formulas, sample data, and guidance notes. Just fill in your actual numbers and the sheet handles the rest.
The template covers standard cases cleanly. It won't handle complex multi-entity consolidations or extensive OCI adjustments. If your situation involves those, you need dedicated accounting software or a professional who understands consolidated financial statements. The template is a starting point, not a complete solution for complex organizational structures.
What Retained Earnings Can and Cannot Tell You
A growing retained earnings balance generally signals that a company is profitable and choosing to reinvest rather than distribute cash. That's usually a positive indicator, though it depends heavily on what the company is doing with that reinvested capital. Throwing money at unprofitable operations just makes the problem bigger and more expensive. A declining balance isn't automatically bad. Companies in early growth stages often run negative retained earnings for years while pouring everything into expansion. Amazon did this for over two decades. The question is whether the growth path eventually leads to profitability or if the losses are structural. What retained earnings absolutely cannot tell you is whether your cash position is healthy. A company can have massive retained earnings and still struggle to pay its bills if most of that earnings has been converted into inventory, receivables, or fixed assets. Cash flow and retained earnings are related but fundamentally different measures. Don't confuse one for the other.
The same principle applies to debt. Companies with strong retained earnings often qualify for better loan terms because lenders see a thicker equity cushion. But if that equity is mostly intangible assets or overly optimistic receivables, the cushion is thinner than the number suggests. Smart lenders look past retained earnings to assess true asset quality and repayment capacity.

Common Mistakes to Avoid
The most frequent error is treating retained earnings as a cash account. It isn't. When you see $500,000 in retained earnings, that doesn't mean $500,000 is sitting in the bank. It means the company has generated $500,000 more in cumulative profits than it has distributed. Where that money went is a separate question entirely. Another mistake is ignoring tax implications. Retained earnings exist on a book basis, but the tax basis might differ significantly if you're dealing with temporary differences between financial reporting and tax filings. This creates deferred tax assets or liabilities that affect the true economic value of retained earnings. For most small businesses, the difference is negligible. For anything with significant depreciation timing differences or stock-based compensation, it's material. Some people try to force retained earnings to balance by plugging numbers. This is the fastest way to produce financial statements that look reasonable but are fundamentally wrong. If your numbers don't tie, find the error. Don't fabricate a solution. The fix is usually a missed journal entry, a misclassified transaction, or a cut-off error from transactions recorded in the wrong period. The error exists somewhere. Trace it properly.
I once spent an entire weekend tracking down a $2,300 discrepancy that turned out to be a single transaction recorded on the 31st of the month instead of the 1st, pushing it into the wrong fiscal period. That transaction affected both net income and retained earnings. The financial statements for both periods were technically incorrect. It's a painful lesson in why cutoff testing matters.
When Professional Help Makes Sense
Most businesses can manage retained earnings calculations internally without issue. The template I linked above covers the vast majority of cases. However, if you're dealing with international operations, multiple legal entities, employee stock option plans, or convertible debt instruments, the calculation complexity increases substantially. In those situations, engaging a CPA or financial accountant for a one-time setup review usually pays for itself within the first quarter. The cost of fixing a mistaken retained earnings figure after it's been filed with external parties is significantly higher than the cost of getting it right the first time. Lenders, investors, and regulators don't appreciate corrections. A single restatement can trigger scrutiny that wouldn't have existed otherwise. Bottom line, retained earnings is a straightforward concept that becomes complicated through edge cases and improper handling. Master the basic calculation, use a clean schedule or template, and verify the numbers regularly. The rest is dealing with whatever specific complications your situation presents.


