The actual process of getting into real estate investing
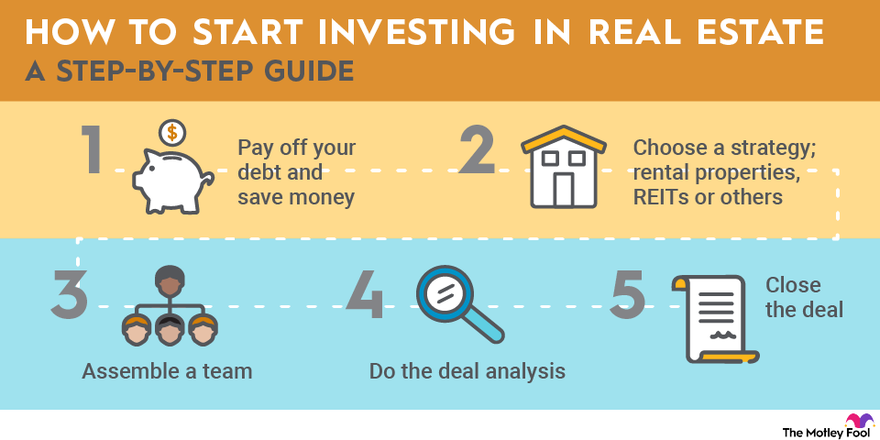
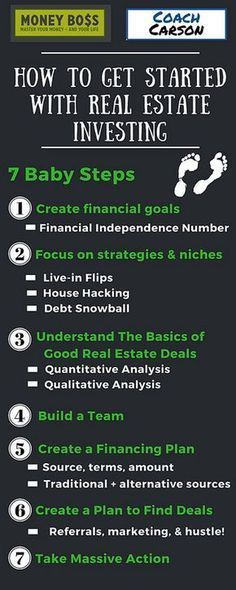
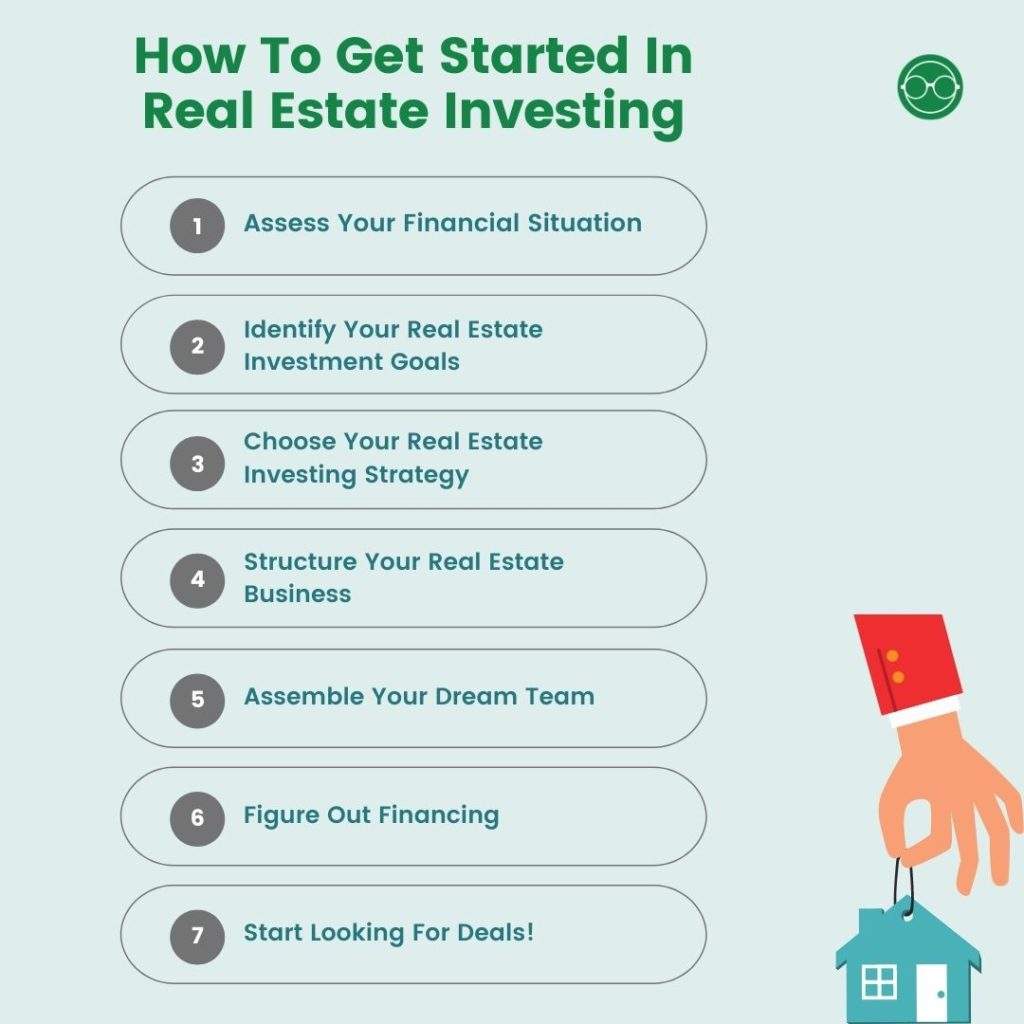
Most people overcomplicate this because they're reading advice from blog posts written by people who haven't personally managed a property in fifteen years. The basics are boring but they matter more than anything fancy you'll read later. You start by picking one market and one strategy. Not both at once. I watched a guy in 2019 try to buy a duplex in Nashville and a triplex in Raleigh simultaneously with the same line of credit. He maxed out both loans within eight months. The properties sat half-empty while he was drowning in servicing debt on units that were never performing. Pick one market. One strategy. Master that before you expand anything. Capital comes first. Not as much as you think. A conventional investment property loan typically requires 20 to 25 percent down. Hard money lenders will run 60 to 70 percent loan-to-value, but the rates are twelve to fifteen percent and the terms are measured in months, not decades. I learned this the hard way on a fix-and-flip in 2016. The deal looked like a fourteen-point return on paper. The hard money carry ate six percent before we even closed the sale. The net came in around six point two percent after repairs, which is barely above what a money market account was paying at the time.
Financing isn't the only hurdle. Property management is where most beginners bleed out. You can self-manage one to three units and keep the math simple. Beyond that, you're trading your time for a manager who will cost you eight to ten percent of gross rent. The question isn't whether you should hire someone. It's whether you can afford to do it yourself until the portfolio justifies the expense.
Where beginners actually go wrong
Number one, they buy based on appreciation instead of cash flow. A property in a up-and-coming neighborhood might appreciate five percent annually, but if it negatives every month, you're paying to own something. Cash flow covers the mortgage, taxes, insurance, and reserves. Appreciation is a bonus. Always lead with cash flow. Number two, they skip the reserves calculation. Every investor needs six months of expenses set aside minimum. Vacancies, roof leaks, tenant turnover, plumbing failures. I had a unit in 2020 where the HVAC went out three weeks after closing. Replacement cost was four thousand dollars. I had twelve hundred in reserves at that point. Had to put it on a credit card at twenty-two percent. That card took fourteen months to pay off and ate into every dollar of profit from that unit for over a year. Number three, they treat every property the same. It doesn't work that way. A single-family rental has different vacancy patterns than a multi-family. A commercial lease has different default risk than a residential one. Analyze each asset class on its own metrics before comparing them side by side.
Get the Full Details
The numbers you need to run before any offer
Cap rate tells you the return on a property if you bought it cash. Take the net operating income and divide by the purchase price. A ten percent cap rate on a hundred thousand dollar property means ten thousand in annual NOI. Simple. But cap rate alone is meaningless without context. Compare it to every similar property in the market. If the neighborhood cap rates sit at seven percent and you're looking at something at ten percent, something is wrong with the property or the neighborhood. Find out what it is before you write the check. Cash on cash return measures your actual dollar return against the cash you put in. Take the annual pre-tax cash flow and divide by your total cash invested. This includes your down payment, closing costs, immediate repairs, and any rehab budget. If you put fifty thousand in and the property generates six thousand a year in cash flow after all expenses, your cash on cash return is twelve percent. That number is what matters for comparing different deals against alternative investments. Debt service coverage ratio checks whether the property actually covers the loan. Net operating income divided by annual debt payment. A ratio below one means the property doesn't generate enough income to pay its own mortgage. Lenders usually want a minimum of one point two five. You should want the same. Anything lower is a problem waiting for a vacancy or a repair to push you into negative cash flow.
Market selection basics that actually work
Population growth matters but it's not everything. Jobs matter more. Look for markets with diversified employment bases. A town a single employer is a risk you don't need. Check job growth over the past five years, not just the last quarter. Quarterly data is noisy. Five years smooths out the noise. Price-to-rent ratio helps you decide whether buying or renting makes more sense in a given market. If the ratio is below fifteen, buying generally makes more sense. Above twenty, renting is usually cheaper. This isn't a hard rule, but it's a useful filter before you spend months analyzing specific properties in a market you might abandon. Rental vacancy rates tell you how hard it will be to keep the unit occupied. National average sits around five to seven percent. Markets above ten percent vacancy are tougher. Not impossible. Just harder. Margins compress when you can't fill units quickly.
Property evaluation in practice
Run a physical inspection yourself if you can. Professional inspectors miss things or rush through them. I once bought a property where the inspector flagged a minor foundation crack. What he didn't catch was the settling pattern around the south wall that indicated drainage was routing water directly toward the slab. I fixed the grading and French drain myself for about two thousand dollars. A structural engineer would have charged four thousand to confirm what I already knew. Knowing how to look at basic site drainage saves more money than any inspection shortcut. Review the rent rolls and expense history for at least twelve months. Tax returns lie sometimes. Booked expenses don't. Look for consistent patterns. If expenses spiked in one year, find out why. A one-time roof replacement is normal. A year where maintenance costs tripled is a red flag. Talk to the tenants if possible. Current tenants know things you won't find in any document. The water heater that has been making noise since last spring. The landlord who ignores repair requests. The neighborhood issue that shows up after dark. Tenants will tell you if you ask the right questions. Don't ask yes or no questions. Ask open ones that force detail.
Tax considerations you can't ignore
Depreciation is the biggest advantage real estate has over other investments. Residential rental property depreciates over twenty-seven point five years. You deduct a portion of the building value every year against your rental income. The land itself does not depreciate. Split the purchase price correctly between land and building. An appraiser can help with this, or you can do a cost segregation study if the numbers get large enough to justify the expense. Pass-through deductions under Section 199A can reduce your effective tax rate on rental income by up to twenty percent depending on your total income level. This isn't a permanent advantage. It expires after 2025 unless Congress extends it. Don't build your entire thesis around it, but factor it into your pro forma. Like-kind exchanges under Section 1031 let you defer capital gains taxes when you sell one investment property and buy another like-kind property. The rules are strict. There are timing deadlines. Fourty-five days to identify replacement properties. One hundred eighty days to close. The replacement property must be of equal or greater value. You must use a qualified intermediary. If you mess up any part of this, the deferral fails and you owe the full tax bill plus penalties. I've seen investors lose six figures to a botched 1031 exchange because they used the wrong intermediary. Verify credentials. Get references. Don't cut corners here.
Scaling beyond your first property
Once you have one successful rental, the next one is easier. You understand the cash flow math. You know what a good property looks like. You have a relationship with a lender. The learning curve flattens. But scaling too fast is the fastest way to fail. Every new property adds management complexity, debt service, and risk exposure. Grow at a pace that keeps your debt service coverage ratio above one point five and your reserves above six months of total expenses across all properties. I saw a investor in my network buy five properties in eighteen months using every tool available. HELOCs, home equity lines, cash-out refinances, private money. By month twenty-two he had three vacancies, one major repair he couldn't afford, and debt payments consuming eighty percent of his income. He sold two properties at a loss to stay afloat. The lesson isn't that leverage is bad. The lesson is that leverage multiplies both gains and losses, and the losses show up faster than you expect. The market changes. Interest rates move. Tenant demand shifts. Your numbers will be wrong sometimes. That's normal. The difference between investors who last and those who don't is usually just whether they kept enough dry powder to survive when their assumptions turned out to be off.