Small Capital Strategies That Actually Work
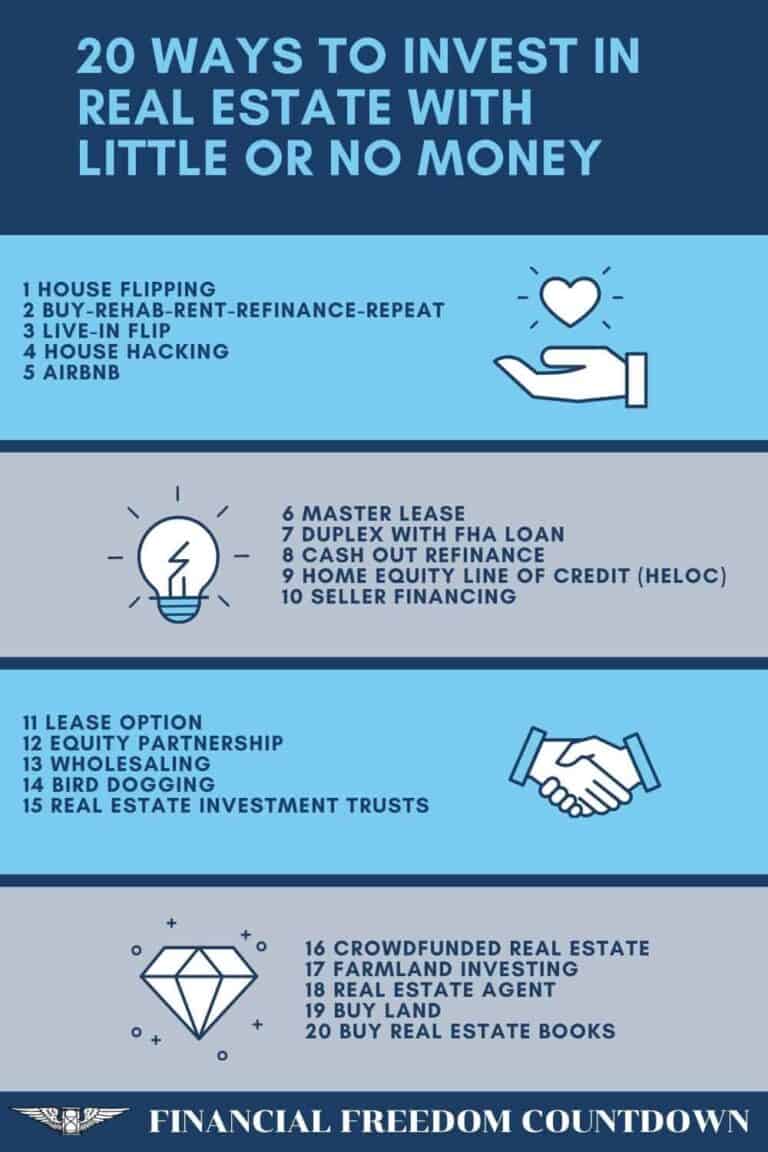
Most people can't put 20 percent down on a rental property and are stuck watching from the sidelines. That assumption is wrong. There are paths into real estate that require a few thousand dollars and a lot more patience than a traditional cash purchase, but they exist and they're well documented if you ignore the Instagram gurus selling templates. The core concept is simple enough: you control the asset without buying it outright. Owner financing, lease options, house hacking, and BRRRR (buy, rehab, rent, refinance, repeat) all work on the same principle. You use other people's money or the seller's equity to get through the door, then you let the property pay you while you rebuild your capital for the next deal. The mathematics behind this aren't hidden, but they require discipline and basic underwriting skills that most beginners skip over because they want to skip straight to the closing. I need to be blunt about something nobody tells you clearly upfront. The biggest obstacle with small capital isn't finding a deal. It's the lender, the investor, or the seller who refuses to engage with a buyer who doesn't have a substantial down payment. You will hear no more than you will hear yes, and the ratio of rejection to acceptance is often worse than you expect. In my experience, you need to prepare a clean one-page summary of your plan before you make a single call. Lenders and motivated sellers don't care about your dream. They care about risk mitigation, and a well formatted one pager does that work for you faster than any conversation.
The BRRRR method gets a lot of attention, and for good reason. You find a distressed property below market value, bring it up to code, rent it out, and then refinance at appraised value. The refinance pulls your original cash back out so you can repeat the process. It sounds elegant. It is elegant in theory and messy in practice. Appraisers don't always see the value you expect after rehab, and lenders won't loan on a property that hasn't been rented for at least six months in most markets. I learned this the hard way on a two unit in a midwestern city where I estimated a $14,000 appraisal bump after updates. The appraiser came in $8,000 lower because comparable sales in the neighborhood hadn't moved as fast as I assumed. I covered the gap with a hard money bridge, paid the higher rate for four months, and moved on. The lesson was straightforward: underwrite the refinance based on conservative comps, not optimistic ones.
The Mechanics of Owner Financing
Owner financing, sometimes called seller carry-back, is one of the most practical ways to enter real estate with minimal cash. The seller acts as the lender instead of a bank. You negotiate terms directly, which means you can structure payments around your actual cash flow rather than a lender's rigid criteria. A typical arrangement might involve five percent down, a fixed interest rate between six and nine percent, and a amortization schedule that spans ten to fifteen years with a balloon payment at the end. This is common in secondary and tertiary markets where banks are reluctant to finance older investment properties. The catch is that sellers rarely offer this without a reason. Usually the property has sat on the market for a while, or the seller needs to defer capital gains for tax purposes, or they simply want to avoid the hassle of a traditional sale. Knowing why the seller is open to creative terms helps you negotiate from a position of strength. If the seller is motivated by speed, you can trade a slightly higher rate or a shorter term for faster closing. If the motivation is tax deferral, you can stretch the terms further because that's what they want. I had a situation a few years ago where the seller agreed to ten percent down and monthly payments that exactly matched the rental income, leaving me cash flow neutral for the first eighteen months. The downside was a relatively high interest rate and a personal guarantee that tied my name to the note. I accepted those terms because the property appreciated enough during that period to cover the cost of capital and give me equity to move forward.
Get the Full Details

Lease Options and Wraps
A lease option gives you the right to purchase a property at a predetermined price within a set timeframe, usually in exchange for an upfront option fee and above market rent. The option fee is often one to three percent of the purchase price, and the extra rent builds toward your future down payment. This structure is useful when you need time to secure financing, improve your credit, or accumulate additional savings. It also lets you control the property without taking on mortgage payments immediately. A wraparound mortgage, or wrap, is different but related. You take over the seller's existing mortgage and add your own financing on top. The seller keeps their original loan in place, you make a single payment each month that covers both the underlying debt and your portion, and you collect the difference as profit. Wraps work best when the seller's existing rate is significantly lower than current market rates. They also carry a title risk because the underlying loan stays in the seller's name. Many investors avoid wraps specifically because of that title issue and the possibility of a due-on-sale clause being triggered if the lender discovers the transfer. I encountered a lease option deal where the tenant failed to maintain the property and the roof leaked badly during the option period. The contract had a maintenance clause, but the tenant considered minor patching sufficient and ignored the structural damage. I ended up paying for a full roof replacement out of pocket even though the option hadn't been exercised yet. The workaround was straightforward in hindsight: I started requiring professional property inspections every ninety days and made the option fee non-refundable only if the property passed inspection at the time of exercise. That single change prevented similar surprises on later deals.
House Hacking Basics
House hacking is the simplest small capital strategy because it reduces your living expense while you build equity. You buy a multi unit property, live in one unit, and rent the others. FHA loans allow you to put down as little as three and a half percent if you occupy one of the units, and conventional loans can go as low as five percent with private mortgage insurance. The rental income from the other units typically covers most or all of your mortgage payment, which means you save money on housing while owning an asset. The practical reality is that being your own landlord while living on site is not comfortable for everyone. Tenants will call you at seven in the morning when the dishwasher breaks. You will hear arguments through shared walls. You need to separate your personal life from your business life before you sign the purchase agreement, or you will regret it quickly. I treated house hacking like a regular rental from day one. I kept a separate bank account, tracked expenses meticulously, and set aside a maintenance reserve equal to five percent of the monthly rent per unit. That reserve covered unexpected repairs without touching my personal savings. Without that system in place, a single major repair can wipe out months of positive cash flow and force you into debt.
The BRRRR Refinance Challenge
The refinance step in BRRRR is where most people stall. Lenders require the property to be stabilized with tenants in place, and they will appraise based on comparable rentals in the area. If you overestimate rental income, the refinance will come in lower than expected. If you underestimate rehab costs, you will run out of cash before the project is complete. Both mistakes are common and both are preventable with proper due diligence. I worked with a lender who required six months of documented rental history before approving a refinance on a rehabsbed duplex. The property was fully renovated and occupied, but the local market was slow to stabilize. I negotiated with the tenant to sign a longer lease and provided proof of on time payments to the lender. This satisfied the requirement without waiting an additional six months. The alternative would have been a bridge loan at eleven percent interest, which would have erased the profit margin on the deal entirely. Negotiation and documentation matter more than speed in these situations.
Hard Money and Private Lenders
When traditional financing is unavailable, hard money lenders and private money lenders fill the gap. Hard money loans are short term, high interest loans secured by the property itself. Expect rates between eight and twelve percent, plus points that can range from two to five percent of the loan amount. These loans are designed for quick turnaround projects, typically six to eighteen months, not long term holds. They are useful for bridge situations where you need to close fast and refinance later at a better rate. Private lenders are individuals who lend their own money, often friends, family, or acquaintances of real estate investors. Terms are more flexible and costs are lower, but the pool of available capital is smaller and the relationships can become complicated if a deal goes south. I once borrowed from a relative at six percent interest with a two year term. The deal went poorly, the property didn't appraise at refinance, and I had to extend the loan with additional interest. The financial cost was manageable, but the relationship suffered for over a year. If you use private money, get everything in writing and have a clear exit strategy before you sign anything.
Where Small Capital Strategies Fail
These approaches do not work in every market. Strong appreciation markets with tight cap rates leave little room for error, and weak markets often lack the demand needed to stabilize a rental quickly. The best outcomes come from markets with stable job growth, reasonable price points, and solid rental demand. I've seen deals fail in coastal cities because the entry price was too high relative to rental income, leaving no margin for vacancy or unexpected repairs. The same strategies work better in Sun Belt cities and Midwest markets where property prices remain moderate and population growth supports demand. You also need to account for the time investment. Owner financing negotiations, lease option setups, and BRRRR projects all take more time than a standard purchase. If you have a full time job and limited hours, you may not be able to manage multiple creative deals simultaneously without outsourcing. Property management companies charge eight to twelve percent of collected rent, which reduces your cash flow but frees up your time. The math usually works if the property is sufficiently cash flowing before management fees, but it eliminates thin margins that might otherwise look attractive on paper. There is also the issue of personal liability. Creative strategies often require personal guarantees, which means your personal assets are on the line if the deal fails. This is different from a corporate purchase where liability is limited to the entity. I maintain an umbrella insurance policy specifically for this reason. It costs roughly a thousand dollars per year for a million dollars in coverage and protects personal assets in case of a lawsuit. That expense is non negotiable if you're using owner financing or lease options regularly.
Getting Started Practically
Start by analyzing your own numbers. Calculate how much cash you can realistically allocate without endangering your emergency fund. Most experienced investors recommend keeping at least six months of personal expenses in liquid savings before pursuing any real estate strategy. Once that buffer exists, identify one market where you can run the numbers with confidence. Build a spreadsheet that includes purchase price, closing costs, rehab estimates, carrying costs, vacancy reserves, property management fees, insurance, property taxes, and a realistic refinance scenario. If the deal doesn't cash flow positively under conservative assumptions, walk away. The temptation to push through a bad number is real, and it is the most common reason beginners lose money on their first few deals. Networking matters more than you might expect. Join local real estate investor meetups, attend property auctions, and connect with wholesalers who specialize in your target market. Wholesalers can provide off market deals that haven't hit the MLS yet, which reduces competition. I found most of my early opportunities through a single wholesaler who understood my criteria and prioritized sending me listings before anyone else saw them. Building that relationship took several months of consistent communication and paying fair assignment fees reliably. The bottom line is that investing with little money is entirely feasible, but it requires a different skill set than traditional investing. You need negotiation ability, basic legal knowledge, patience with longer timelines, and the willingness to accept higher personal risk in exchange for lower capital requirements. It's not a shortcut. It's a different path with its own set of obstacles and rewards.


