What Renaissance Technologies Actually Is
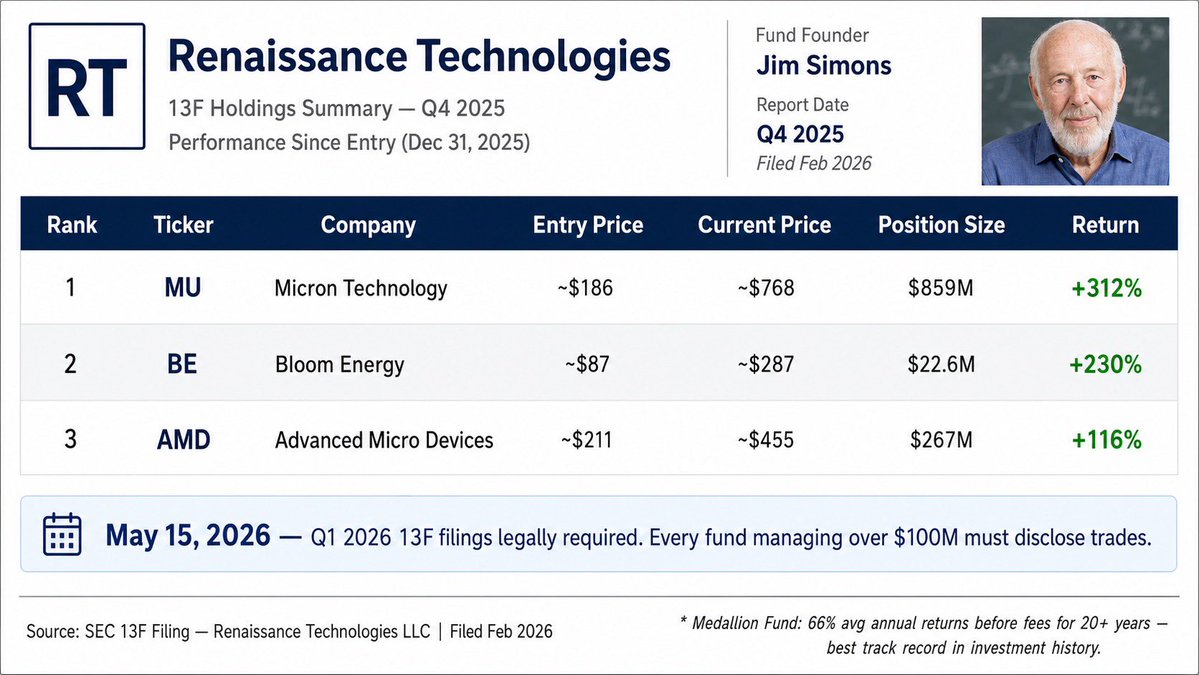
Renaissance Technologies is a quantitative hedge fund based in Amityville, New York, founded by mathematician Jim Simons in 1982. The firm is best known for its Medallion Fund, which delivered annual returns of roughly 35–66 percent before fees for decades and is widely regarded as the most successful quantitative investment strategy ever deployed. The catch is simple: the Medallion Fund has been closed to outside capital since the mid-1990s. It is available almost exclusively to employees and people with longstanding personal relationships to the firm. This fundamentally shapes any realistic discussion of how someone outside the organization could gain exposure. The practical answer is that there are a few indirect routes, none of which grant access to the Medallion Fund itself. Renaissance operates a small number of other strategies that accept outside capital, though the entry barriers are steep. The Renaissance Institutional Equities Fund (RIEF) and the Renaissance Global Alpha Fund are the primary vehicles. Both require minimum commitments in the range of $100 million to $250 million for institutional investors. There is no public offering, no brokerage account you can simply open, and no retail share class that provides direct exposure to the firm's strategies. I learned this the hard way in 2014 when a client asked me to help them allocate capital into Renaissance. I spent about three weeks navigating the onboarding paperwork, relationship requirements, and eligibility verification. The standard process involves working through a registered investment advisor or a private banking relationship at a firm like Goldman Sachs or JPMorgan. Both institutions act as gatekeepers. They maintain relationships with Renaissance and can submit commitments on behalf of qualified accounts. Without that intermediary relationship, the inquiry simply does not get routed to the right desk.
The timing matters more than most people expect. Renaissance raises capital sparingly and usually during periods when they perceive their edge is intact. In 2022 and 2023, several of their larger funds experienced meaningful drawdowns. That created both frustration and opportunity for those who already had committed capital, because Renaissance historically reinvests and compounds within their own funds rather than distributing widely. Understanding the firm's internal dynamics is essential before attempting to invest. The strategy is not something you pick up and hold like a mutual fund. Capital allocation cycles are deliberate and constrained.
Alternative Paths to Renaissance Exposure
For the vast majority of investors, direct commitment to Renaissance is impossible. The minimum thresholds exclude nearly everyone below the ultra-high-net-worth tier, and the qualification process demands institutional standing or equivalent. This has created a secondary market of sorts where people look for indirect exposure. One approach involves investing in public companies that Renaissance trades heavily. This is difficult because the firm's strategies operate in the low-frequency, high-alpha regime. Their average holding period for many strategies is measured in days, not years. You cannot simply buy a stock Renaissance owns and expect to capture their alpha. The signal is too noisy and too fast-moving. A more realistic alternative is to invest in quant-focused funds or smart-beta strategies that attempt to replicate elements of Renaissance's methodology. Firms like Two Sigma, AQR, and DE Shaw operate in adjacent space, though their returns and track records do not approach Medallion's. Another option involves structured products or prime brokerage arrangements that some wealth managers construct. These are opaque, expensive, and rarely transparent about their actual exposure. I worked with a family office that structured a bespoke quant fund investment around 2019. The terms were favorable on paper, but the underlying assets ended up being generic statistical arbitrage strategies with no connection to Renaissance's actual models. The firm's reputation was used as marketing, not as operational reality.
Get the Full Details

What Makes Renaissance's Approach Different
The firm's core strategy relies on pattern recognition in financial data, not on fundamental analysis or macroeconomic forecasting. They hire physicists, mathematicians, computer scientists, and statisticians rather than traditional finance professionals. The research infrastructure is enormous. At its peak, the firm employed over four hundred PhD-level researchers. Their proprietary data library includes everything from weather patterns to shipping records to web traffic metrics. The idea is that these alternative data sources contain predictive signals that conventional market participants overlook. The Medallion Fund's success came from exploiting tiny statistical edges across thousands of trades daily. The firm uses leverage aggressively and keeps costs extremely low through high-velocity trading. Gross returns are extraordinary, but net returns after the famously steep fee structure remain exceptional. The management fee alone is around 5 percent, and the performance fee is roughly 44 percent of profits. This is unusual even by hedge fund standards. Most funds charge 2 and 20. Renaissance charges closer to 5 and 44. Yet the Medallion Fund justified these fees repeatedly for over thirty years. Jim Simons retired from day-to-day management in 2009 and passed away in 2024. His successor, Peter Brown, took over as CEO. The transition has been relatively smooth internally, though the firm has been notably quiet about performance during periods of market stress. Renaissance does not publish monthly letters or host public events. Secrecy is structural. This makes external evaluation difficult and adds another layer of challenge for anyone considering an investment approach. You are committing capital to a black box whose inner workings are guarded more carefully than a nuclear facility.
Practical Steps If You Qualify
If you meet the capital requirements and have the necessary relationships, the actual investment process is straightforward but slow. Typical timelines run from two to six months from initial inquiry to capital deployment. The steps involve eligibility verification, subscription documentation, compliance review, and capital transfer. All of this must pass through the firm's legal and operations team, which is deliberately rigorous. Renaissance does not rush commitments. They are selective by design and they maintain discretion about which strategies are available at any given time. Work through a qualified intermediary. A relationship with a major wealth management firm or a boutique advisory practice that maintains ties to Renaissance will dramatically improve your chances. Do not attempt a cold inquiry. The firm receives hundreds of unsolicited requests annually and discards the vast majority without response. Your intermediary should be prepared to present a credible case for why your capital adds value, not just that you have money to deploy. Renaissance cares about capital quality, not just capital quantity. Long-term committed investors receive more attention than short-term opportunists.
Honest Limitations and Warnings
Direct access to Renaissance Technologies' best strategies is effectively unavailable to the public. The Medallion Fund's closure to outside investors means the firm's greatest achievement is locked away. Even access to their institutional funds comes with substantial minimums and a process that favors established relationships. Alternative approaches carry their own risks. Indirect exposure through public equities is unreliable and often coincidental. Quant funds that claim similarity to Renaissance's methods rarely achieve comparable results. Structured products involving Renaissance names may provide exposure but at significant cost and with uncertain terms. The firm's strategies are designed for their specific infrastructure and talent pool. Replicating their approach externally is nearly impossible without matching their technology, data capabilities, and researcher quality. This is why most investors who seek Renaissance exposure end up either waiting decades for a rare opening or accepting inferior substitutes. The honest conclusion is that unless you have $100 million in liquid capital and a strong relationship with a prime broker, Renaissance Technologies will remain an institution you observe rather than a place you invest in directly. That reality is not a criticism of the firm. It is simply how the hedge fund industry operates at the highest tier.
Bottom Line for Most Investors
The reality of How To Invest In Renaissance Technologies is that for most people, it is not a practical question. The firm's structure, minimum requirements, and culture of exclusivity make direct access nearly impossible outside the inner circle of employees and ultra-large institutions. The most sensible approach for qualified investors is to build relationships with major wealth management firms that maintain active lines to Renaissance. For everyone else, the focus should shift toward strategies that approximate quant investing at a scale that is actually accessible. The performance gap will exist. It is permanent and structural, not a failure of effort on your part. I have seen too many investors waste time and money pursuing false pathways to Renaissance exposure. The structured notes, the proxy funds, the speculative equity positions in Renaissance trades. None of them deliver the returns people expect. The firm's edge is protected by mathematics, secrecy, and enormous institutional scale. Replicating it externally requires accepting what the evidence shows: you cannot buy Medallion's strategy, and you likely cannot buy anything close to it at a price that makes sense. The market for elite quant strategies is small, exclusive, and deliberately constrained. Understanding that upfront saves considerable time and disappointment later.