Getting Started With a Small Amount
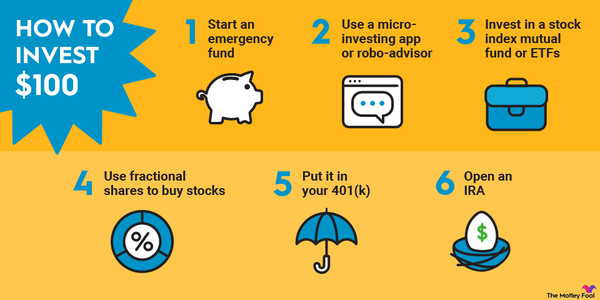
You can absolutely start investing with a hundred dollars. The old idea that you need thousands to enter the market is outdated. A lot of brokerages now offer fractional shares, which means you can buy a slice of an expensive stock like Amazon or Microsoft with whatever amount you have. The mechanics are straightforward, but there are a few traps that catch beginners if they aren't paying attention. The first thing you need is a brokerage account. Most people go with Fidelity, Charles Schwab, or Robinhood for small accounts. Fidelity's FDUSF ticker is one of their fractional share programs, Schwab has fractional trading built in on most equities, and Robinhood's whole selling point is fractional ownership. Open the account, link your bank, deposit the hundred bucks, and place a buy order. That's the mechanical part. The harder part is what you actually buy and how you hold it. When I was helping my brother get started back in 2019 with about the same amount, he tried buying individual tech stocks because that's what everyone was talking about. He put fifty dollars into one company and fifty into another. Within six months, he'd lost more than twelve percent on the first one alone after a earnings miss he hadn't even read the report for. He was watching the ticker on his phone like it was a slot machine. That's not investing. That's gambling with a brokerage interface. We switched him to fractional S&P 500 ETFs and he stopped checking his portfolio every day. Different outcome entirely.
With a small account, transaction costs and behavioral mistakes matter more than most people expect. Even zero-commission platforms will sometimes charge a small fee for certain orders or have payment for order flow arrangements that create a subtle bid-ask spread cost. On a hundred dollars, a twenty-five cent spread on each side of a trade eats more percentage-wise than it would on a ten-thousand-dollar position. It's tiny in absolute terms but it compounds. The practical approach most people should take with a small amount is to buy a single broad market ETF and add to it regularly. VOO or SCHV or VTI depending on which broker you use. Fractional shares make this possible even with irregular contribution amounts. Set up automatic deposits if you can. The behavior of consistently adding money matters far more than picking the right entry price on any given day. There's a limitation worth being honest about. A hundred dollars won't move the needle on its own. If your goal is to generate meaningful income or wealth, this is a starting point, not a strategy. The math is simple: a hundred dollars at a seven percent annual return gives you about seven dollars in a year. The real value comes from the habit of investing and the additional contributions you make over time. People who treat a small initial amount as "set it and forget it" rarely benefit much from it. The ones who benefit are the ones who treat it as the first step in a system.
Another thing nobody tells you about small accounts is tax inefficiency if you try to play the individual stock route. Buying and selling frequently inside a taxable account generates short-term capital gains, which are taxed at your ordinary income rate. That can easily erase any returns you made before taxes. A taxable brokerage account with a hundred dollars makes sense if you're mostly buying and holding ETFs, but it makes less sense if you're trading in and out of individual positions trying to time the market. If you have access to an employer retirement account with matching, use that before a regular brokerage account. Even contributing a hundred dollars through a 401k where your employer matches a portion is essentially a guaranteed return that no stock pick can reliably beat. Most people with small account balances are sitting on the table somewhere else without realizing it. The other common mistake is holding too many positions with too little money. Splitting a hundred dollars across five or six stocks sounds like diversification but it isn't really. You end up with positions so small that even a twenty percent gain only gives you twenty dollars. It's better to have one or two broad positions with a small amount than six thin ones that feel diversified but aren't. Diversification requires either a broad ETF or enough capital to meaningfully spread risk across individual holdings. You don't have enough capital for the second option yet.
Get the Full Details
There's also the behavioral side that's harder to prepare for. When you have a small amount, you're more likely to chase performance. You see a stock up thirty percent in a month and you want in. You sell a position that's down ten percent because you think it's going to zero. These reactions cost more in percentage terms with small accounts because you're more impatient for results. The money isn't enough to make you comfortable, so you either panic-sell or overtrade trying to make it grow faster. Set up a system. Pick your ETF or your single stock position. Set a date to add money each month. Don't look at the balance daily. Treat it like dirt you're planting, not a lottery ticket you're scratching. The people who actually build wealth from small amounts are the ones who stop treating it like a puzzle to solve and start treating it like a routine to maintain.