Testing Functions for Injectivity in Practice
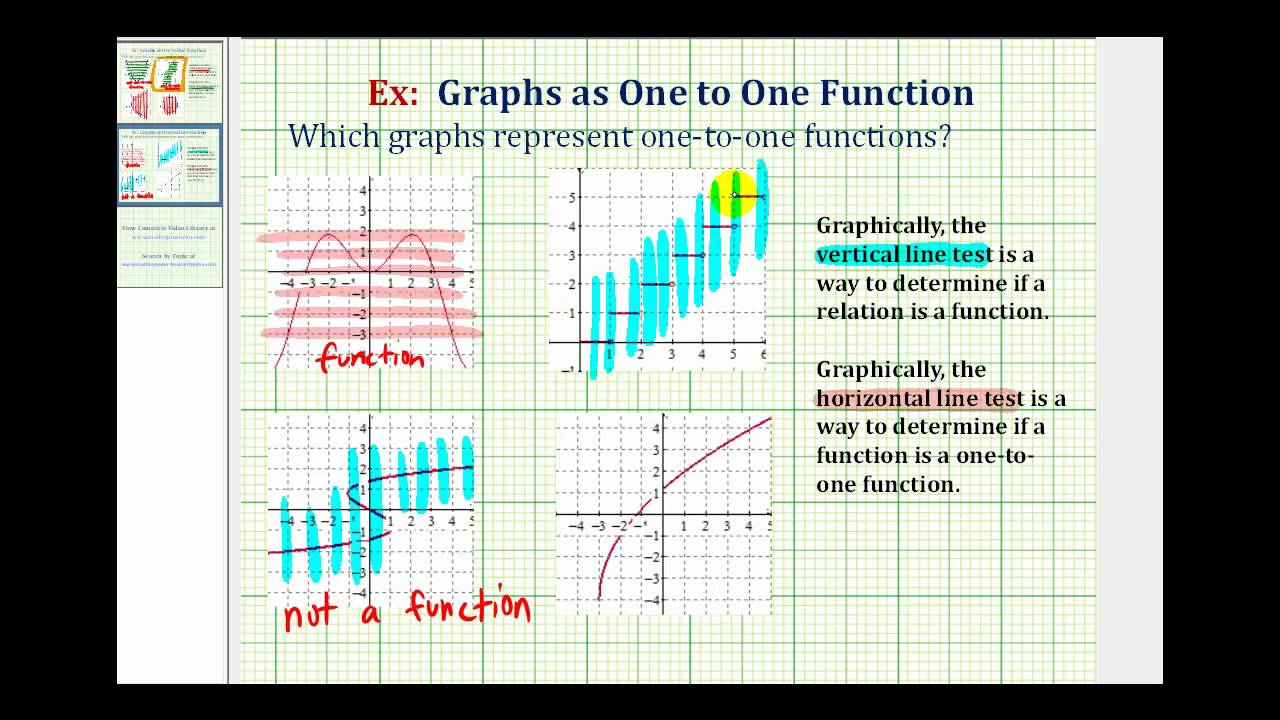
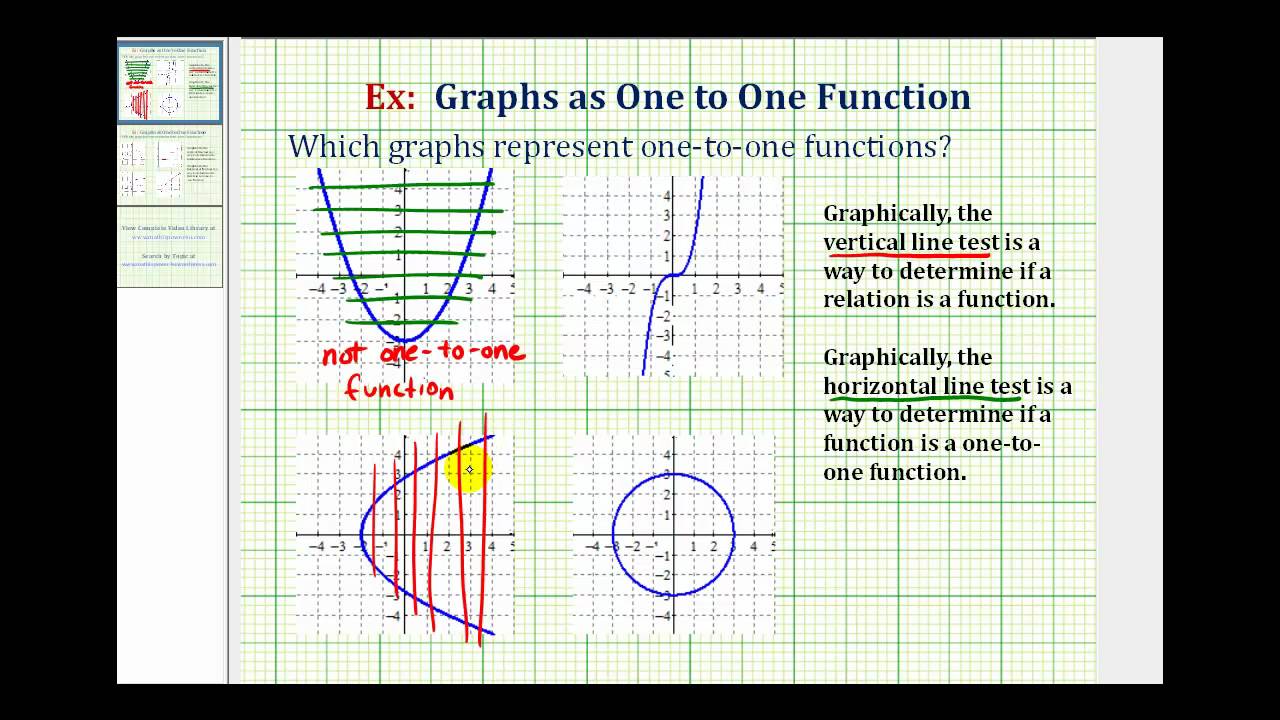
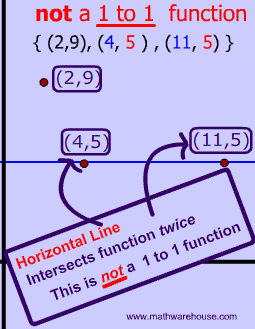
A one-to-one function is one where every input maps to a unique output, and no two different inputs ever share the same output. You'll also see this called an injective function in more formal settings. The concept itself is simple enough, but telling whether an arbitrary function actually satisfies that condition is where things get messy, especially when you move past textbook examples. The most direct approach is the horizontal line test, which works cleanly for functions you can graph easily. If any horizontal line intersects the curve more than once, the function fails. But relying on a sketch is unreliable when you're dealing with something like a piecewise function with three segments, or a rational expression with asymptotes you haven't carefully traced. I spent about forty minutes once trying to determine injectivity for a composite function involving a logarithm nested inside a quadratic, and the graph just looked flat enough near the vertex that I couldn't tell whether it dipped below or stayed tangent. I stopped drawing and solved f(a) = f(b) algebraically instead, which cut the problem down to checking whether a = b was the only solution. That algebraic method is the standard tool. You assume f(a) = f(b), then manipulate the equation until you either prove a must equal b, or you find a valid counterexample where a and b are different but the outputs match. If you reach a = b, the function is one-to-one on that domain. If you find distinct inputs with equal outputs, it isn't. This works for polynomials, exponentials, logarithms, trigonometric functions with restricted domains, and most combinations of those.
For polynomial functions specifically, there's a shortcut that doesn't get enough attention. A polynomial is one-to-one on an interval only if it is strictly monotonic there, meaning it never flattens out and reverses direction. You can check this by looking at the derivative. If f'(x) is positive everywhere on the domain, or negative everywhere, the function is injective. But if the derivative crosses zero, you need to be careful about what happens at that point. A derivative of zero doesn't automatically disqualify the function. Take f(x) = x³ as the classic case. The derivative at x = 0 is zero, but the function is still strictly increasing through that point, so it remains one-to-one. The real failure condition is when the derivative is zero and changes sign, creating a local maximum or minimum. That's what breaks injectivity. I ran into this distinction repeatedly when working with cubic functions in a signal processing context. Someone on my team had a transfer function that included a cubic term and assumed it was invertible because the derivative never went negative. It did go to zero at one point, and we caught it only because I expanded f(a) = f(b) explicitly and found a pair of distinct roots. The derivative test alone would have misled us there. So the derivative approach is useful, but it should complement the algebraic verification, not replace it. Trigonometric functions are another area where people routinely make mistakes. The sine and cosine functions are not one-to-one over their natural domains. They repeat forever. Restricting the domain fixes this, but the restrictions aren't arbitrary. For sine, you need to pick an interval where the function is monotonic, like [-/2, /2]. For cosine, [0, ] works. These are the standard principal branches for a reason, and mixing them up leads to incorrect inverse functions. I've seen students try to invert cosine over [0, 2] and wonder why their results don't match the calculator's arccos output. The function simply isn't injective on that larger interval, so the inverse doesn't exist there in any meaningful sense.
Exponential and logarithmic functions are usually straightforward. e^x is one-to-one across all real numbers. log_b(x) is one-to-one for x > 0 when b > 1. The tricky edge case shows up when you compose them with other functions. f(x) = e^(x²) looks exponential at first glance, but the x² inside flips the behavior entirely. This function is not one-to-one because f(a) = f(b) whenever a = -b, and those are distinct inputs for any nonzero value. You have to look at the full structure, not just recognize the e^x form and assume injectivity carries over. There's also the inverse function test, which is logically equivalent but worth stating separately. A function has an inverse that is also a function if and only if it is one-to-one. This matters because sometimes you're not trying to prove injectivity for its own sake. You're trying to determine whether you can solve for x in terms of y, or whether a system of equations you're building will have a unique solution. In numerical work, checking one-to-oneness before attempting to invert a function can save you from chasing nonexistent solutions or accepting spurious ones. One concrete limitation I want to flag: the algebraic method f(a) = f(b) doesn't always yield a clean proof. There are functions where proving injectivity requires tools beyond basic algebra. Consider f(x) = x + sin(x). Setting f(a) = f(b) gives you a + sin(a) = b + sin(b), which rearranges to a - b = sin(b) - sin(a). Proving a = b from this requires knowing that sin(b) - sin(a) |b - a| with equality only when a = b, which pulls in mean value theorem territory. For most practical purposes the function is clearly one-to-one since the derivative 1 + cos(x) is nonnegative everywhere and only zero at isolated points, but if your domain includes points where the derivative vanishes, you need the monotonicity argument, not just the derivative sign check.
Get the Full Details

Another thing that trips people up is domain dependency. A function might be one-to-one on one domain and not on another. f(x) = x² is not one-to-one over all real numbers, but it is one-to-one if you restrict to x 0. When you're working with a function that comes from a physical system or a dataset, the domain is often implicit rather than stated. You need to figure out what the realistic input range is before you can properly test injectivity. Testing over the wrong domain gives you the wrong answer, and that mistake propagates into whatever inversion or analysis you do next. For computational work, if you have the function as code rather than a formula, you can approximate injectivity by sampling. Generate a large set of input pairs, compute the outputs, and check for collisions. This won't prove injectivity, but it can quickly rule it out if you find duplicate outputs. I use this as a first pass before doing any analytical work. If a random sample of ten thousand points shows two outputs within machine epsilon of each other at different inputs, the function is almost certainly not one-to-one, and you can stop there. If you find no collisions in a dense sample, you still need the analytical proof, but at least you've eliminated the obvious failures without doing much work. The key takeaway is that there's no single method that covers everything. The horizontal line test is fast but imprecise. The derivative test is efficient for differentiable functions but has edge cases. The algebraic f(a) = f(b) approach is the most general and reliable, but it demands that you can actually solve the resulting equation. Knowing which tool to reach for, and when to combine them, is what separates people who can handle this on a test from people who can handle it in real work.