The Mechanics of Building Business Credit Without Losing Your Mind
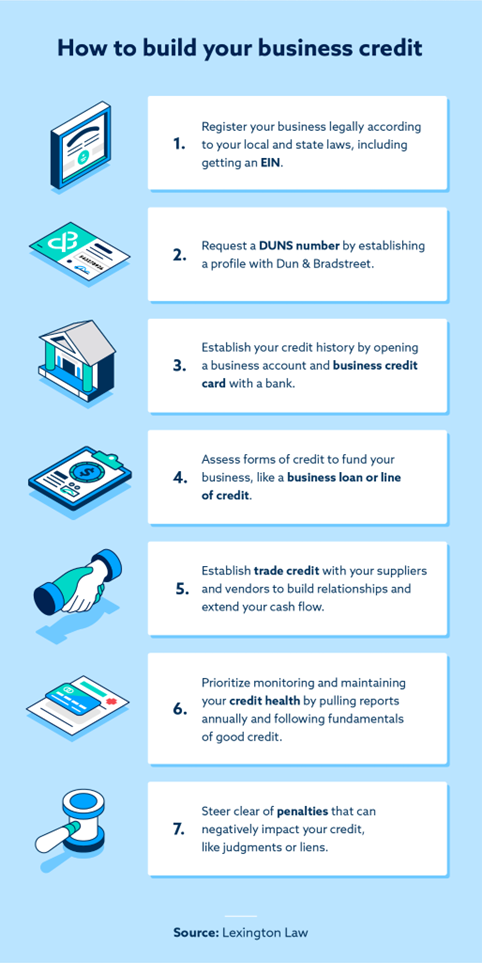
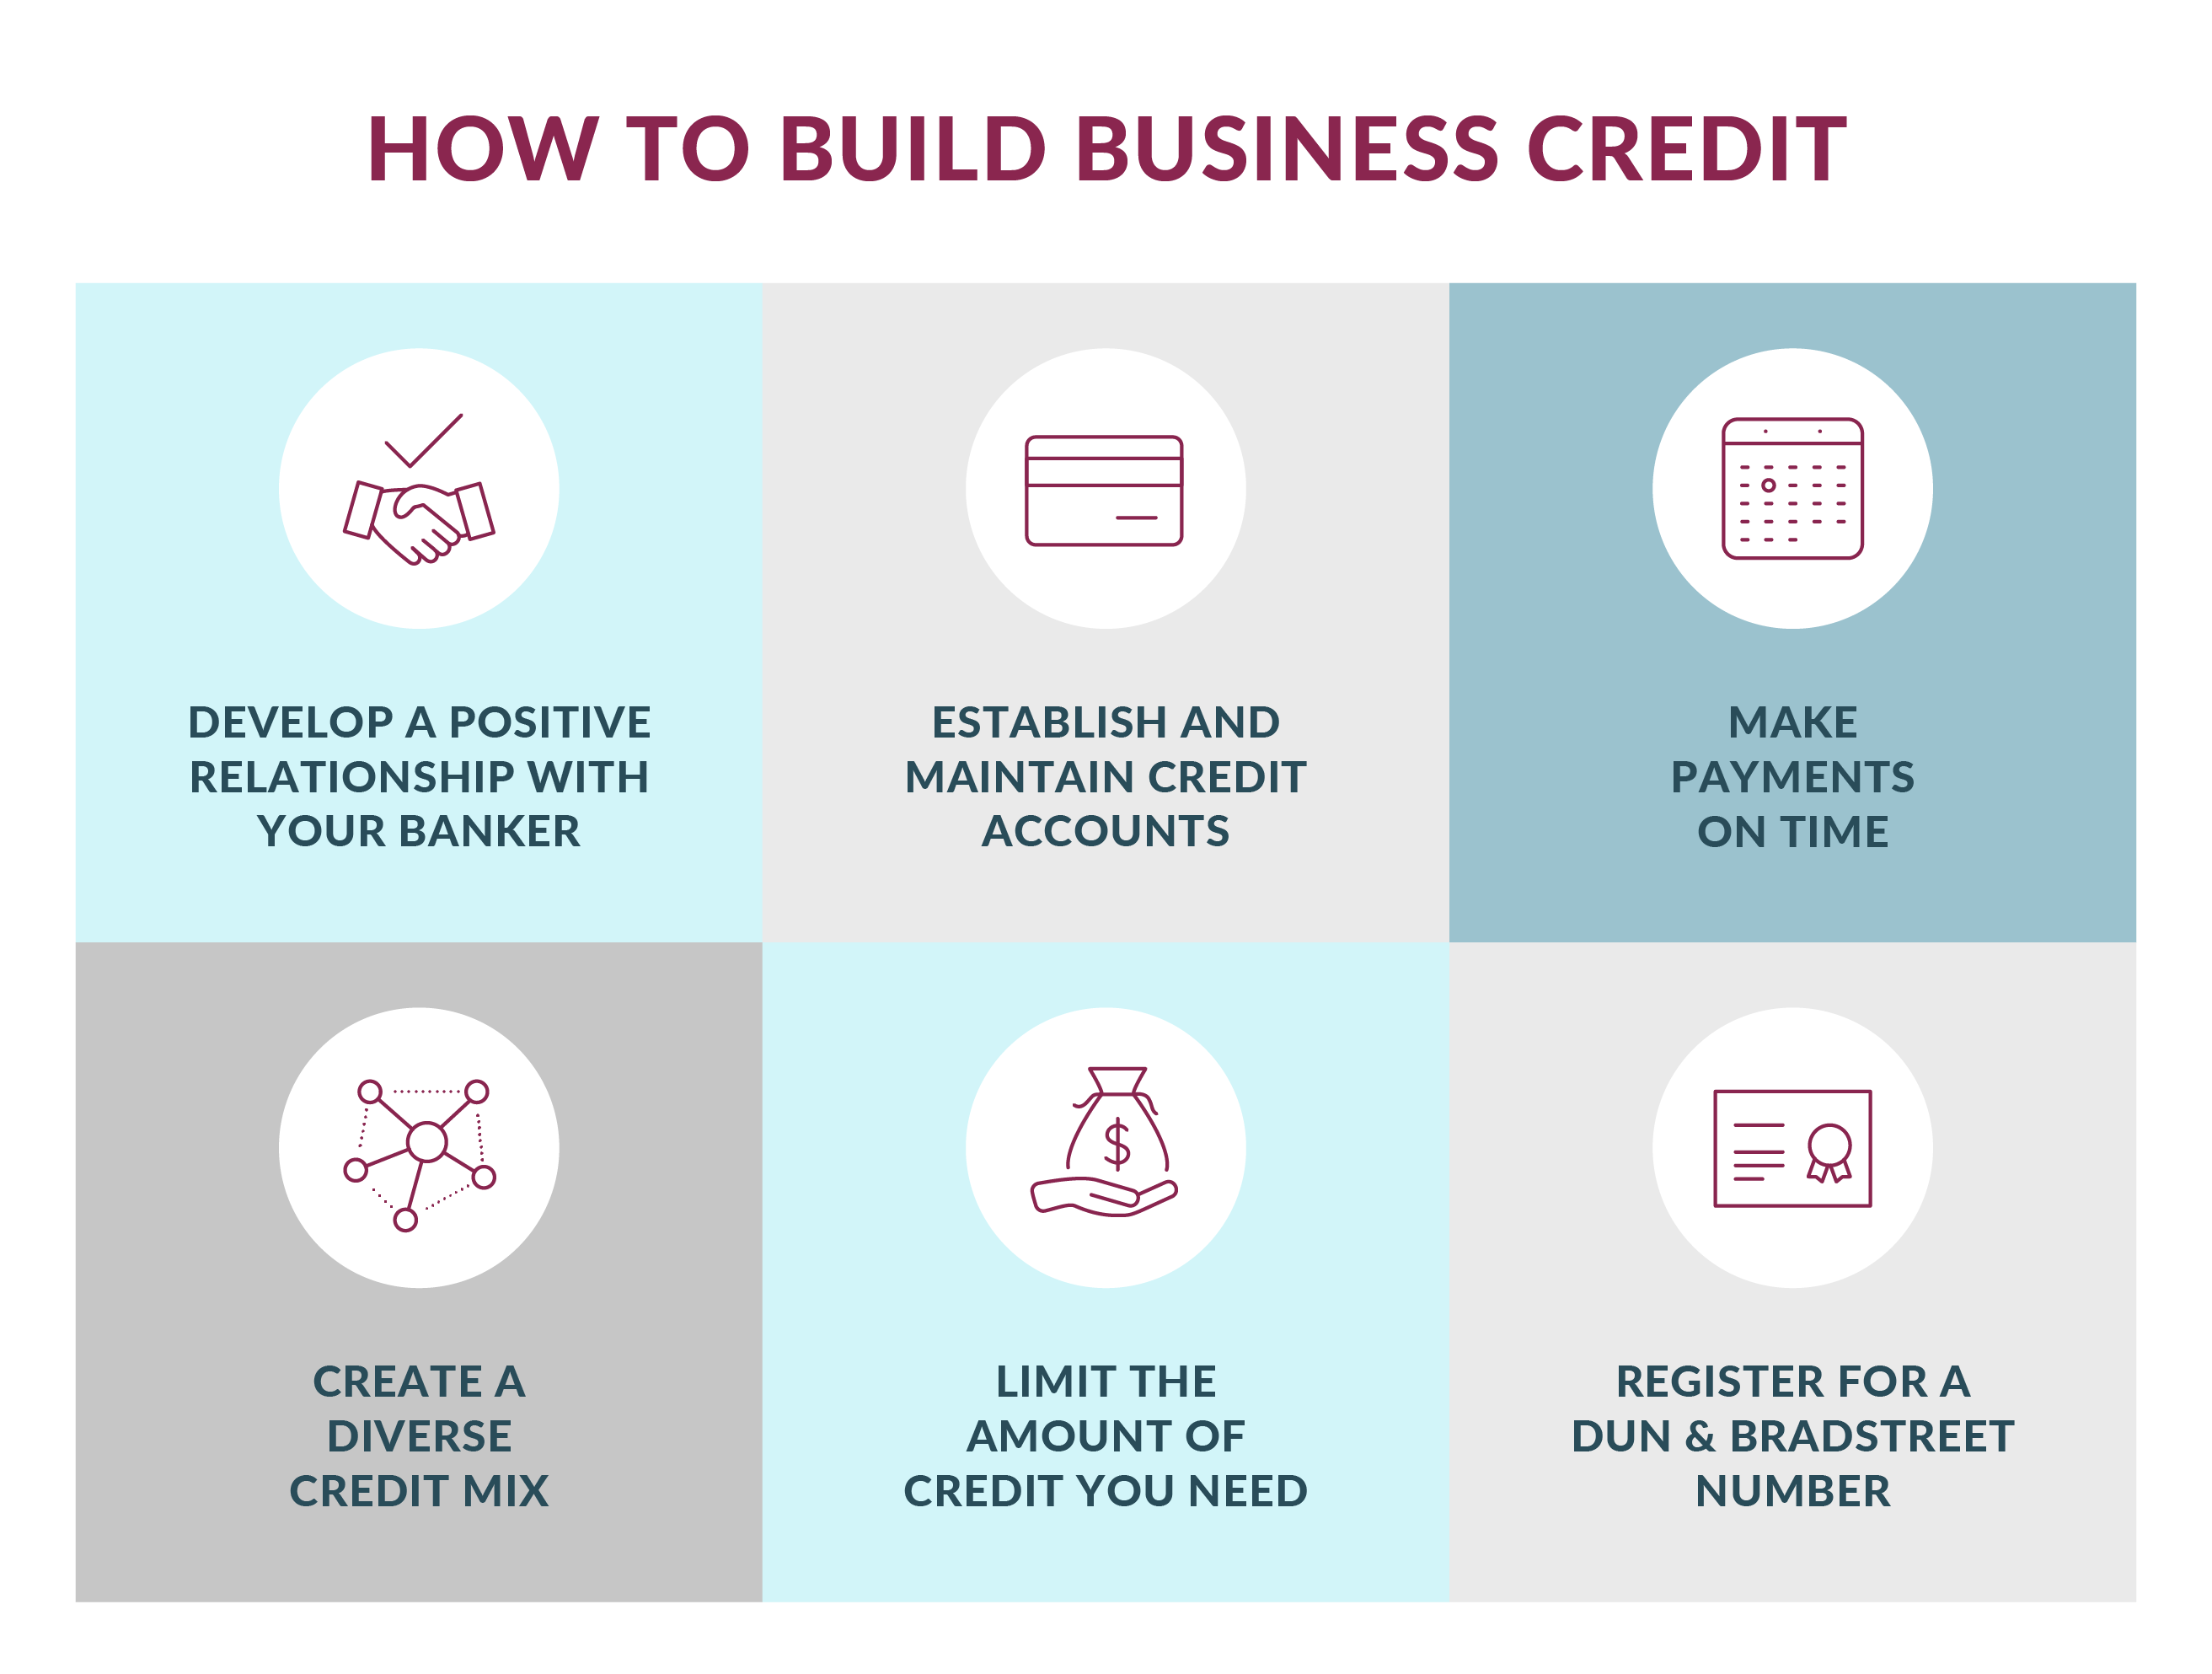
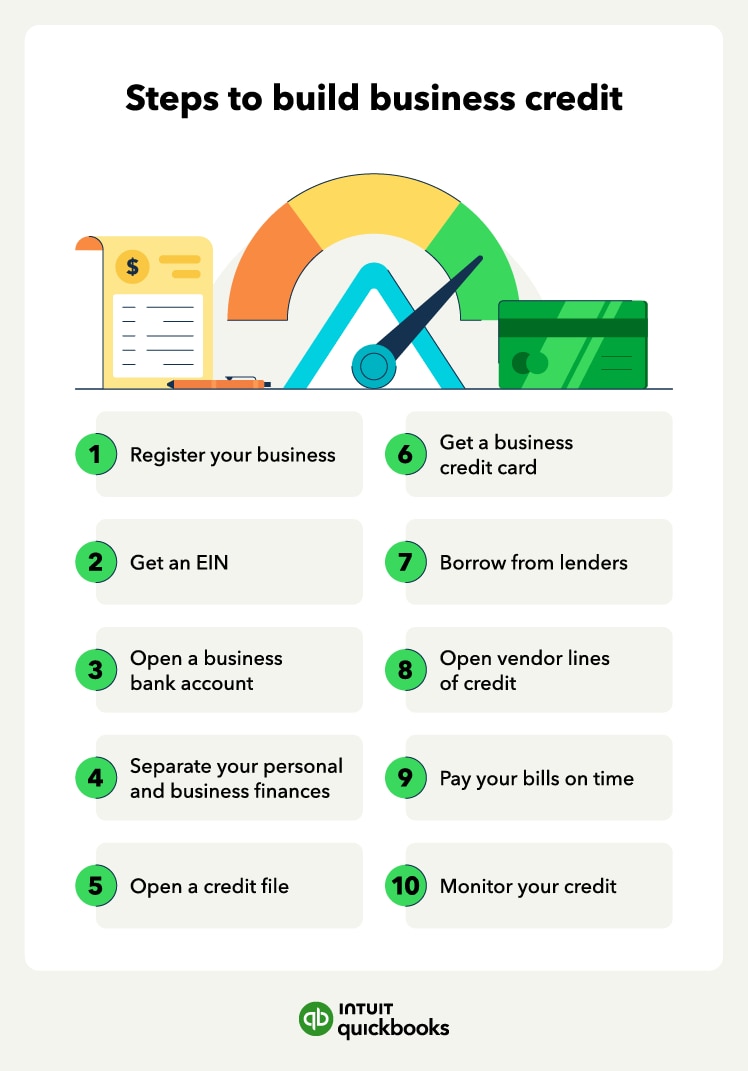
Most small business owners treat business credit like it is a magic wand. It is not. It is a system of reporting relationships between your company, your vendors, and three major bureaus. Get that straight first, then figure out the actual steps. The foundation is separate entity status. Your business needs an EIN from the IRS, a dedicated business bank account, and a DUNS number from Dun & Bradstreet. That last part is non-negotiable if you want Paydex scores, which is the primary metric lenders look at. Without a DUNS, you are invisible to a lot of the reporting ecosystem.
How To Leverage Business Credit for Real Growth
Here is the practical path. Start with net-30 accounts from vendors who report to the credit bureaus. These are the easiest to get. Companies like Uline, Grainger, Quill, and various office supply and equipment vendors offer them. You put down a small deposit, sometimes nothing at all, and make purchases that you pay off within the billing cycle. This builds your payment history across multiple reporting agencies simultaneously. After six to eight months of consistent payment on those accounts, you qualify for store credit cards and smaller lines of credit under your business name. This is where the leverage starts. A $5,000 to $10,000 credit line on your business card used for routine operating expenses, paid in full every month, creates a much stronger profile than a dozen net-30 accounts with tiny balances. Then you move to vendor lines that report to all three bureaus. These are different from net-30 accounts. Vendor lines usually come with actual credit limits and revolve like credit cards. Fleet cards from Shell, Pilot, and Love's are a common entry point for service-based businesses. Equipment leasing companies also extend credit that reports. Each approved line adds depth to your profile.
The key insight nobody tells you is that utilization matters less on business credit than personal credit, but only up to a point. A business credit card at 90 percent utilization will not tank your score the way it would a personal card, but hitting 100 percent utilization triggers automatic limit reviews that can freeze your account. I learned this the hard way during a cash flow crunch in 2022 when I maxed out three vendor lines in the same month to cover payroll. Within two weeks all three accounts were flagged for review and my limits were cut by half across the board. The workaround was to pay down two of the three accounts to below 30 percent utilization and leave one carrying the balance. The lowered utilization on the majority of accounts stabilized the profile enough that the reviews closed without further damage within sixty days. Below is a realistic timeline based on what actually happens, not what the gurus promise. Month one through three: open three to five net-30 accounts, make small purchases, pay early. You will see your Paydex score start moving from nothing to around 78 within ninety days if the vendors report promptly, which they usually do.
Get the Full Details

Month four through six: apply for a business credit card. Capital One and Chase are the most likely to approve with thin files. Use it for normal expenses. Pay it off before the statement closes to keep utilization low on the reported balance. Month seven through twelve: apply for a vendor line of credit or a small SBA loan. By now you should have a Paydex in the 80s. A score above 80 opens doors to better terms. Scores below 70 and most lenders treat you the same as a personal credit applicant. Year two and beyond: you can approach banks for larger lines of credit. Commercial real estate lenders will look at your business credit profile alongside your personal guarantee requirements. Some will offer non-recourse financing at strong credit levels, which means the debt stays on the business and does not touch your personal credit if things go wrong. This is the actual leverage point.
There are several pitfalls that people walk into repeatedly. The first is commingling personal and business expenses on the same accounts. When you do this, the credit bureaus cannot distinguish business payment behavior from personal payment behavior. Your excellent personal payments get buried and your occasional late personal payment drags down your business profile. Keep everything separate from day one. The second pitfall is applying for too many credits in a short window. Each hard inquiry registers on your file. Ten inquiries in thirty days looks desperate to any underwriting algorithm. Space your applications out by at least forty-five days between major credit products. The third and most overlooked pitfall is ignoring your Ficcus file. Ficcus is a business credit reporting service that some smaller lenders use. It pulls data from different sources than the major bureaus. If you build a strong profile on Experian Business and Dun & Bradstreet but your Ficcus file is empty or shows outdated information, you will get surprising rejections from lenders who rely on that bureau.
A counter-intuitive detail about business credit is that having too much credit too quickly can actually hurt you. I saw this with a client in 2023 who opened twelve vendor lines in forty days. The automated underwriting systems interpreted the rapid accumulation as a sign of financial distress. Her subsequent application for a $50,000 line of credit was declined on the basis that her available credit was nine times her annual revenue, which triggered a debt-to-credit ratio red flag even though she had zero balances. She ended up closing four of the older accounts and waiting six months before reapplying. The application went through the second time. Another thing that surprises people is that business credit building takes longer for LLCs than for corporations. The legal structure matters to underwriters. C-corps and S-corps have longer established track records in commercial lending. An LLC is seen as newer and riskier by many traditional lenders, even when the underlying credit data is identical. If you are building credit for an LLC, expect to give yourself an extra three to six months before qualifying for anything above a basic vendor line. The main limitation of business credit is that it does not replace personal credit for early stage businesses. Almost every lender above a certain dollar amount will require a personal guarantee. Business credit is valuable because it separates your personal liability exposure over time and gives you access to larger credit pools, but it does not eliminate the personal guarantee requirement until you have years of strong financials and a significant revenue track record. Do not assume that building business credit means you can stop maintaining your personal credit. Both matter simultaneously.
If your goal is purely operational flexibility and you do not need large capital, focusing on vendor lines and store credit is sufficient and faster. If you need six figures or more for equipment or expansion, you will need both strong business credit and strong personal credit, plus solid revenue documentation. There is no shortcut around that.