What an Accounting Worksheet Actually Is
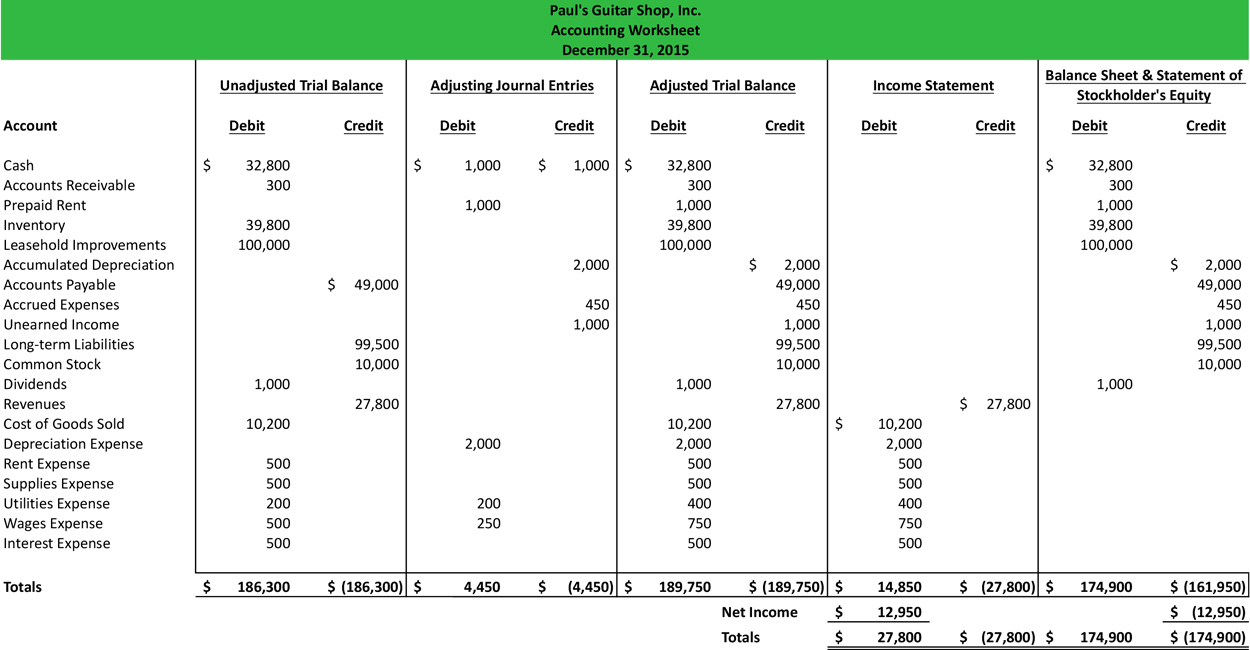
It's a draft document that sits between your trial balance and your formal financial statements. You don't send this to anyone. It's your scratch paper for working through adjustments before they hit the official books. Most small businesses and even some mid-market firms build these in spreadsheets because it's faster than doing it by hand, and honestly, audit trails from paper worksheets are a nightmare to track down six months later. The standard worksheet has eight column sections: unadjusted trial balance, adjusting entries, adjusted trial balance, income statement columns, and balance sheet columns. That's it. The columns aren't decorative. Each one serves a specific purpose in catching errors before they propagate into your actual ledger. If you skip a section, you're just hoping you did the math right.
How To Make Accounting Worksheet
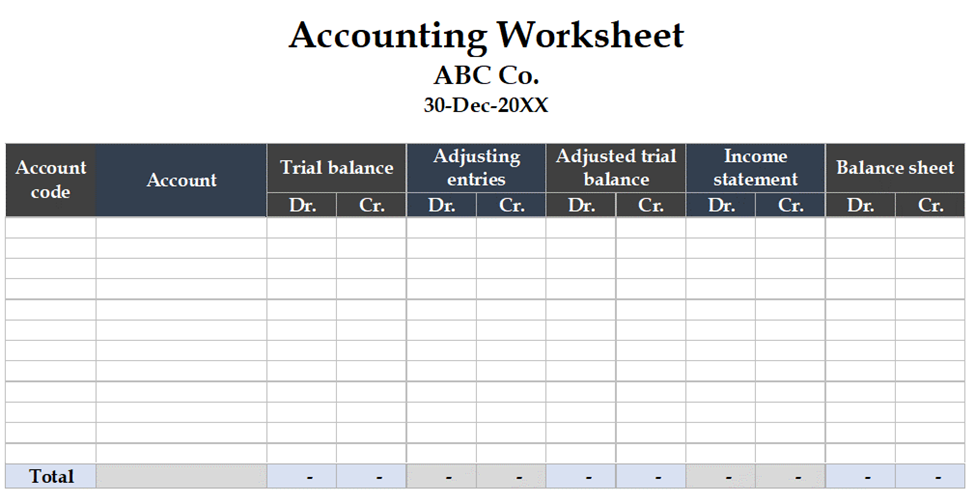
Here's the actual process. Open a blank spreadsheet. Set up your column headers in row 1, starting with account names on the left, then UNADJUSTED DR, UNADJUSTED CR, ADJUSTMENTS DR, ADJUSTMENTS CR, ADJUSTED DR, ADJUSTED CR, INCOME STATEMENT DR, INCOME STATEMENT CR, BALANCE SHEET DR, and BALANCE SHEET CR. That's ten data columns plus the account label column. Eleven total. Transfer your trial balance into the first two columns. Every account with a debit balance goes in the debit column, credit balances go in the credit column. Total both columns. They must match. If they don't, you have an error somewhere in your trial balance and nothing downstream will work. I spent three hours once tracking down a $47.32 discrepancy that turned out to be a single cell where I'd typed 1,247.32 instead of 1,200.00 for prepaid insurance. The worksheet would have balanced fine if I hadn't misposted it upstream. This happens more often than people admit. Next, list your adjusting entries. These are the accruals, deferrals, depreciation, bad debt estimates, and any other entries that need to hit before you close the period. Put them in the adjustments columns. Each adjusting entry should have equal debits and credits across those two columns. After you list everything, total the adjustments columns and verify they match each other.
Now do the math. For each account, if it's a debit balance account and you have a debit adjustment, add them together for the adjusted debit. If the adjustment is a credit, subtract it from the debit balance. Flip that logic for credit balance accounts. The adjusted trial balance columns are simply your starting balance plus or minus the adjustments. This part is mechanical. The spreadsheet formulas should handle it automatically. Once the adjusted trial balance is correct, extend each account to either the income statement columns or the balance sheet columns based on whether it's a revenue/expense account or an asset/liability/equity account. Revenue and expense accounts go to the income statement. Everything else goes to the balance sheet. When you total those two sets of columns, the income statement columns should show you your net income or net loss. The balance sheet columns should balance to each other. Here's the thing most people miss. If your income statement debit total exceeds your credit total, you have a net loss. If credits exceed debits, you have net income. That net income or loss figure then gets plugged into the balance sheet columns to make them balance. The worksheet is self-validating. If the numbers don't tie out at this stage, you made an error somewhere in the adjusting entries or the extension process, and you need to go back and find it before touching your general ledger.
Get the Full Details

I worked with a company once where their worksheet appeared to balance perfectly, but their retained earnings were off by exactly one year's worth of depreciation. Turns out they had forgotten to adjust the accumulated depreciation account in the adjustments section entirely. The worksheet columns balanced because the error was symmetrical — they'd debited depreciation expense but never credited accumulated depreciation. It showed up as a mismatch between the balance sheet total and what their actual sub-ledger reported. We caught it because I ran a comparative schedule showing accumulated depreciation month over month and noticed the jump was zero for twelve consecutive periods. A properly built worksheet would have flagged this immediately if the adjusting entry had been recorded in it.
Where People Go Wrong
Using manually typed numbers instead of cell references. Every value in your adjusted trial balance and extended columns should be a formula referencing the trial balance and adjustments columns, not a number you typed in. I've seen worksheets where someone manually entered adjusted balances and then spent forty minutes trying to figure out why the columns wouldn't balance after they'd already moved on to the next task. A simple SUM formula costs nothing and prevents that entirely. Another common failure mode is not locking your column totals. When you're building the worksheet, every section subtotal should be a summed formula. If a total is hard-coded, any change you make upstream silently corrupts the downstream math. This is especially dangerous when you're doing monthly close work and revising prior month adjustments. I had a colleague who updated a prior period accrual and didn't realize the worksheet's adjusted balance column was pulling from a manually entered cell rather than a formula. The numbers looked fine at a glance. The balance sheet didn't reconcile until the external auditors asked for supporting documentation. You also need to be careful about account classification when extending to the income statement versus balance sheet columns. Dividends go to the balance sheet side even though they reduce equity. They're not expenses. Gains and losses from asset disposals go to the income statement. This isn't intuitive for everyone and getting it wrong skews both your net income calculation and your balance sheet total in ways that cancel each other out on the surface but are wrong underneath.
When to Use This and When to Skip It
The worksheet is most valuable during monthly or quarterly close for companies that have moderate transaction volume. If you're processing fewer than fifty accounts and your adjustments are straightforward, you might get by with adjusting entries directly in your accounting software and skip the worksheet entirely. Many modern systems like QuickBooks Online or Xero handle adjustments natively and generate trial balances automatically. In those cases, a separate worksheet is redundant overhead. But if you're using a system that doesn't auto-generate adjusted trial balances, or if you're dealing with complex adjustments like multi-element revenue recognition, lease modifications, or inventory write-downs that require detailed supporting calculations, the worksheet pays for itself quickly. I've seen firms cut their close timeline from four days to two after implementing a standardized worksheet template because the visibility into each step eliminated the back-and-forth troubleshooting that normally happens when numbers don't agree. The main downside is that worksheets become stale artifacts if you don't maintain them consistently. Every period, you need to start fresh or archive the previous one. I've seen firms accumulate dozens of outdated worksheets that confuse rather than clarify because someone can't tell which period's numbers are current. A simple naming convention and monthly archive folder solves this. Call it WS_2024-06_Adjusted, not final_worksheet_v3_reallyfinal.xlsx.
A Practical Template Structure
Row 1: column headers as described above. Row 2: totals row with SUM formulas for each column. Rows 3 through maybe 80 or however many accounts you have: individual account lines with formulas that pull from the trial balance, apply adjustments, and extend to the appropriate statement columns. Row 81 or so: another totals row. Then below that, the net income or loss line calculated as the difference between the income statement columns, with a formula that feeds into the balance sheet columns to force the balance. Use conditional formatting to highlight any row where an adjustment exists. It makes scanning for reviewed entries faster. Add a notes column adjacent to the adjustments section if your adjusting entries reference supporting documentation. That reference should point to a specific workpaper or file location, not just a vague description. I always require a cross-reference code like JE-2024-06-003 so that when an auditor asks why a certain adjustment was made, you can trace it back in thirty seconds instead of thirty minutes. If you want a downloadable template to start from, most professional accounting platforms offer worksheet templates in Excel format. AIA and AICPA both publish standard templates that follow the structure I described. You can also build one from scratch in about twenty minutes using the column layout above. The value isn't in the template itself, it's in making sure every cell uses formulas and that you actually run through the self-validation step at the end rather than assuming the numbers work because they look reasonable.