Getting Out of a Mortgage Early Isn't Hard, It's Just Math and Discipline
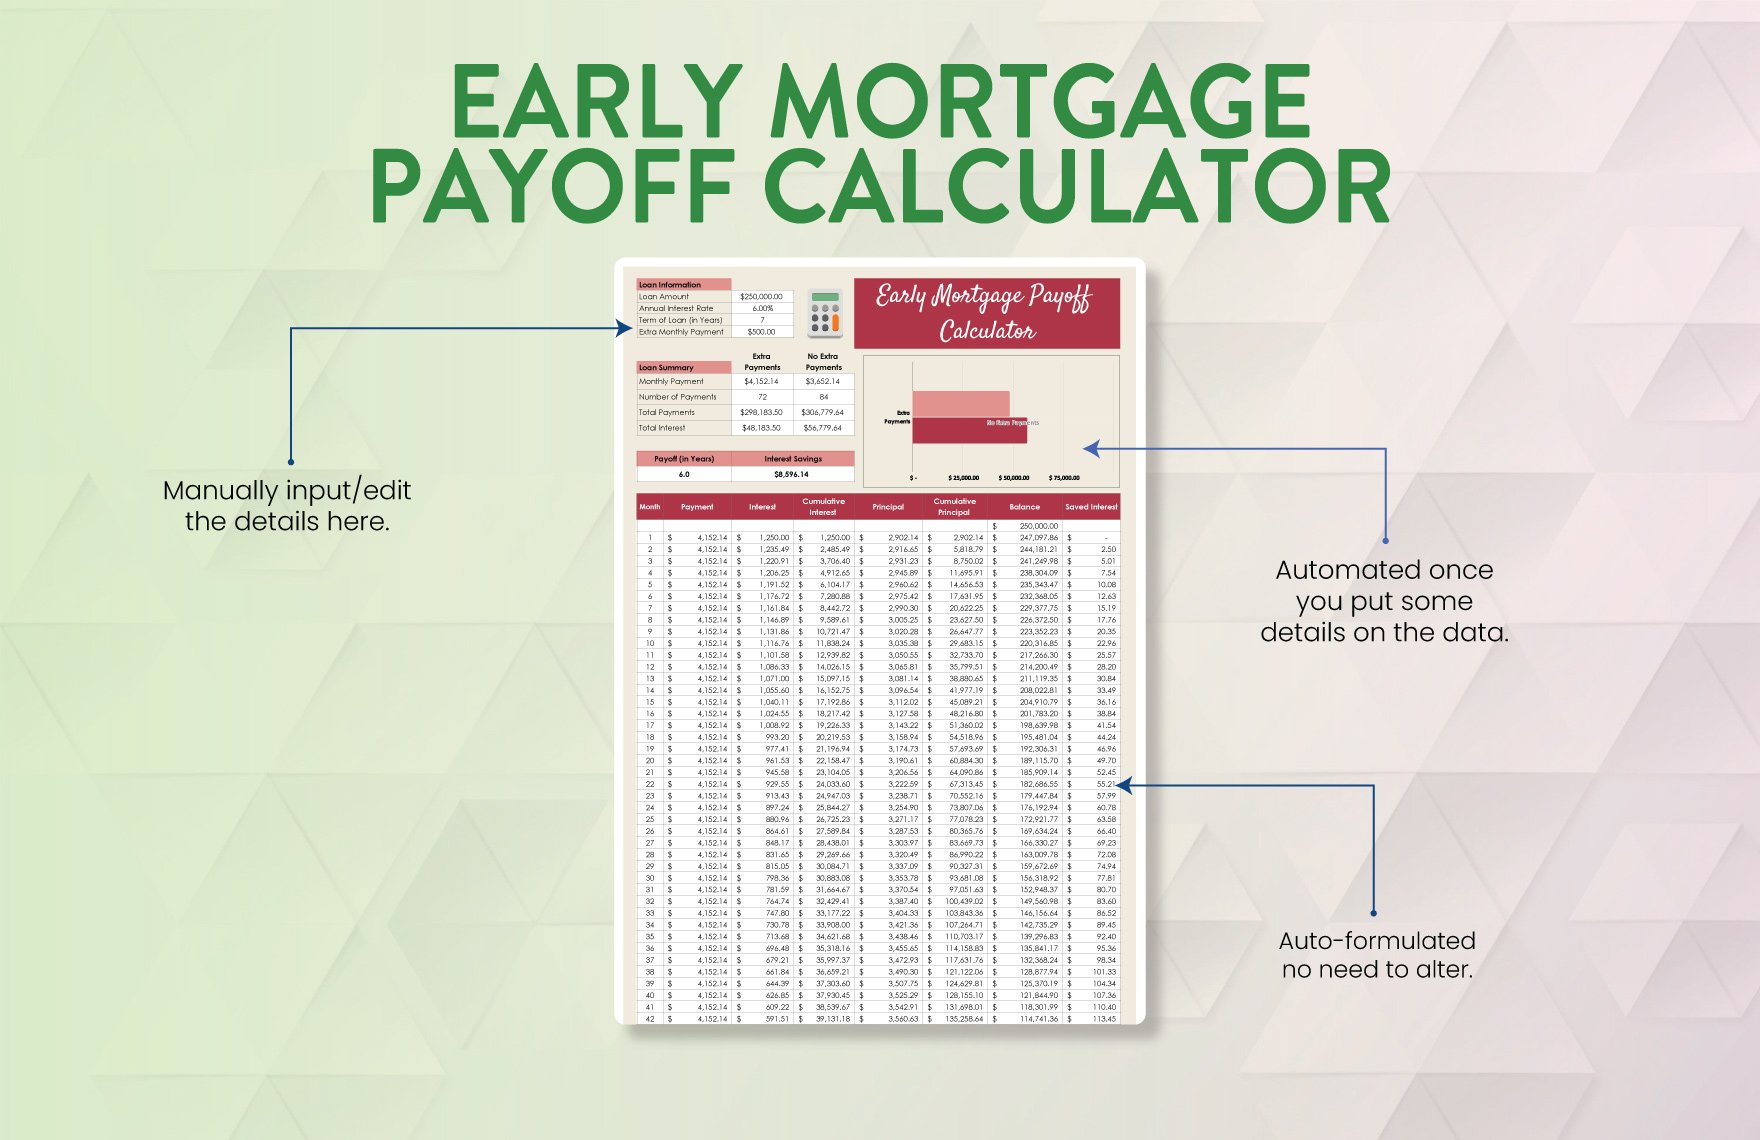
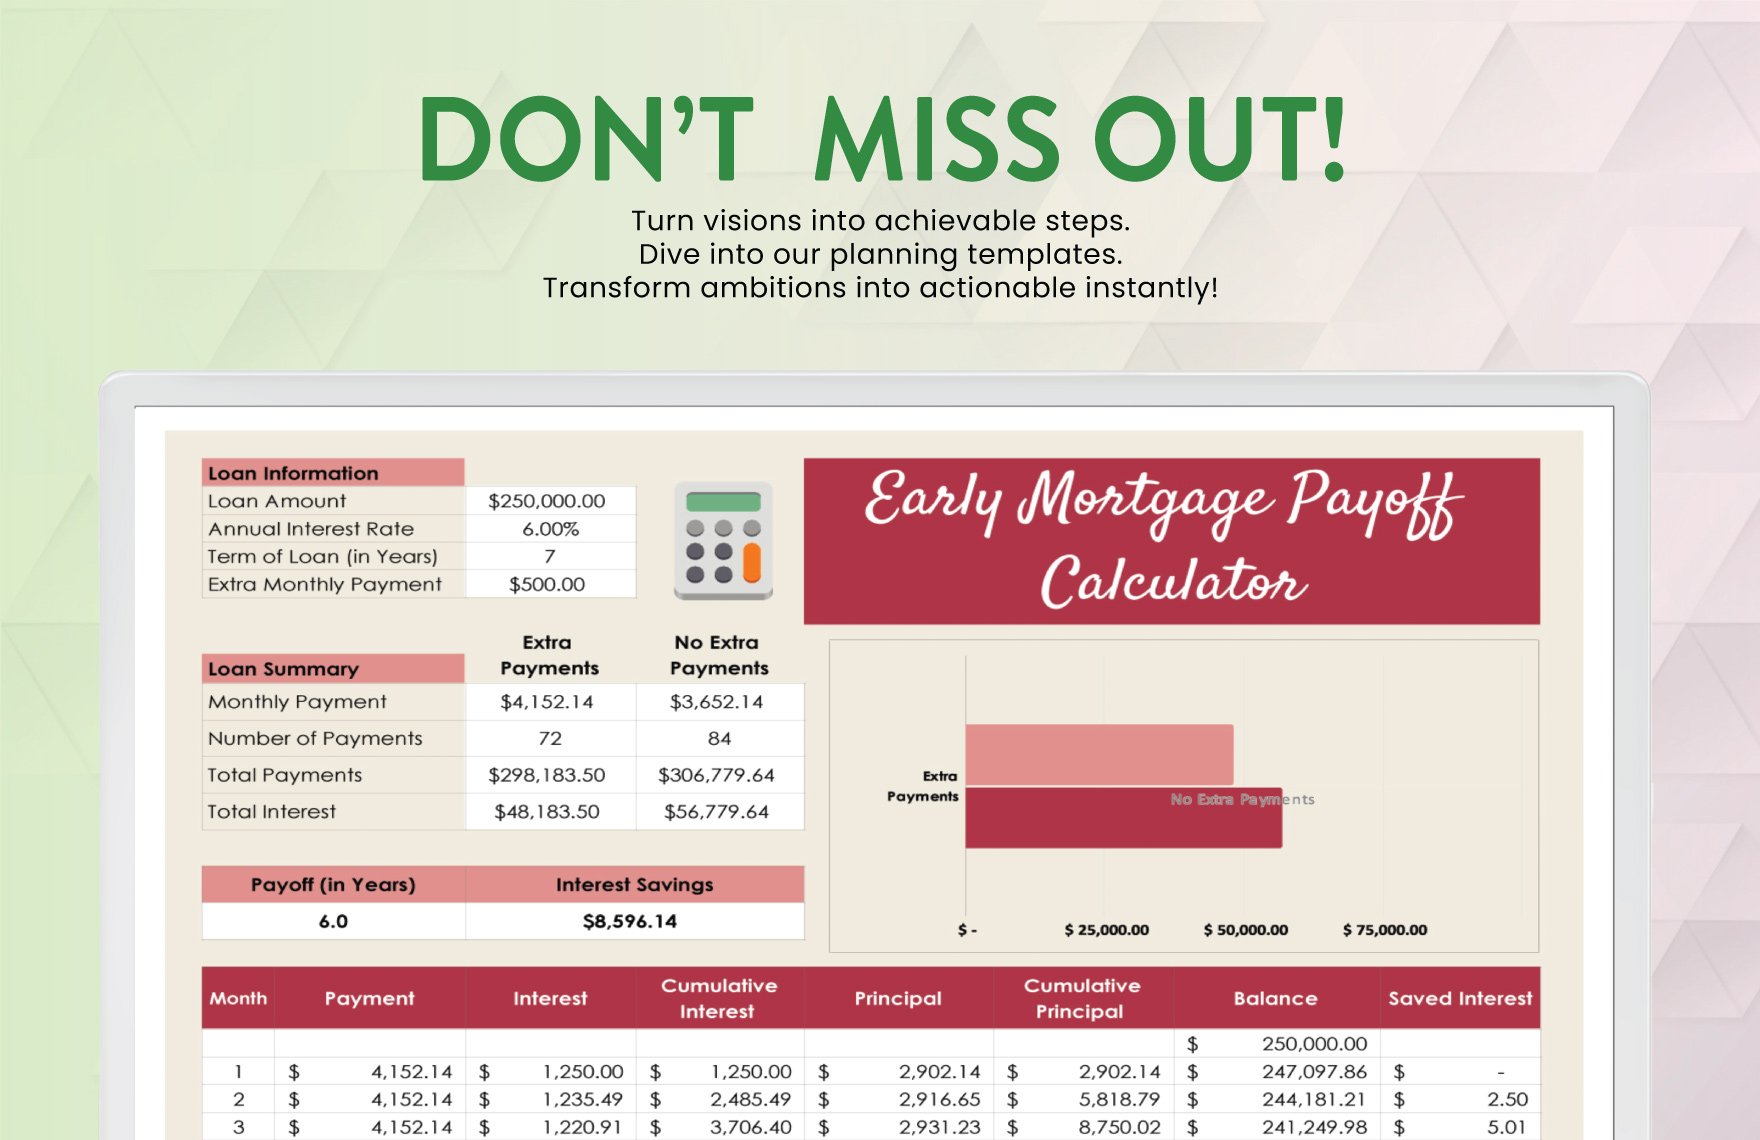
Most people take 30 years to pay off their house. If you can throw enough extra money at the principal every month, you can shave that down to five. The tool that makes this realistic instead of a guessing game is a payoff calculator, and the one I keep bookmarked is the How To Pay Off Mortgage In 5 Years Calculator. It does exactly what it says: it tells you what your payment needs to be, or how much extra you need to throw at each bill, to clear the balance in 60 months. I've seen borrowers get tripped up by this more times than I can count. The math looks straightforward until you factor in how the bank actually applies your payment, which brings me to the first thing nobody tells you.
How To Pay Off Mortgage In 5 Years Calculator
Here's how I use it. You plug in your remaining balance, your interest rate, and your target payoff date. The calculator spits out the monthly payment you need to hit that target. But here's where people screw it up: they don't check whether their lender allows partial principal prepayments without penalties, and they don't account for the difference between payment frequency and compounding frequency. For example, last year a guy came to me with a $320,000 balance at 6.25% and he wanted to be done in five years. The calculator said his payment needed to be about $3,912 per month. He was making the regular principal and interest payment of $1,960 plus an extra $2,000 in undesignated funds. His lender applied that extra $2,000 to his next scheduled payment instead of hitting the principal directly. He lost nearly four months of acceleration before he figured it out. The fix was simple: he wrote "apply to principal" on the memo line and started sending a separate check marked principal only. That detail alone changed the payoff timeline by almost half a year.
The Real Numbers Behind a Five-Year Payoff
Let me break down what actually happens when you try to do this. A standard 30-year fixed at 6.5% on $350,000 has a monthly payment of roughly $2,212. Over 30 years you'll pay about $446,000 in interest. To kill that same loan in five years, your payment jumps to approximately $6,880 a month. That's a 210% increase on the base payment, and it doesn't even include taxes and insurance if you're escrowing those. The calculator will give you these numbers instantly, but the hard part isn't the calculation. It's the cash flow. You're committing over six thousand dollars a month for five straight years with zero margin for error. If your income dips, the whole plan derails fast because you've already baked that payment into your budget as non-negotiable.
Get the Full Details
What the Calculator Won't Tell You
These tools assume a static scenario. Your rate stays the same. You make every payment on time. No life happens. In practice, that assumption breaks pretty quickly. I had a client who got halfway through a five-year payoff plan, then had a medical emergency that wiped out six months of extra payments. The calculator couldn't account for that. It just showed her a clean path to zero that wasn't actually available once reality hit. Another issue: property taxes and homeowners insurance. Most people finance their homes with an escrow account, and those costs go up every few years. When your PITI payment rises, the extra principal-only chunk you were counting on gets smaller unless you increase the total payment too. Run the recalculated numbers through the How To Pay Off Mortgage In 5 Years Calculator whenever your escrow changes, which is usually every spring when your tax bill comes in.
Bidirectional vs. Unidirectional Prepayments
This is the technical detail that separates people who actually succeed from people who try and quit. Most lenders process prepayments unidirectionally by default, meaning extra money goes toward future scheduled payments first. To get real acceleration, you need bidirectional prepayment application, where any amount over and above your minimum payment is immediately applied to the outstanding principal balance. This is the difference between shaving five years off your loan and shaving three years off it. Not every lender offers this, and some charge a prepayment penalty that eats into the savings. Check your loan documents for a clause called "prepayment penalty" or "yield maintenance." If that penalty exists, running the payoff through the calculator with and without it will show you whether the accelerated plan is even worth pursuing or if refinancing to a loan without that clause makes more sense.
When This Strategy Falls Apart
Paying off a mortgage in five years is not always the right move. If your loan carries a rate below 4%, you're likely better off investing the extra cash elsewhere. The returns from a diversified portfolio over five years will probably outpace what you save in interest by keeping a cheap loan alive. I've watched people aggressively pay down 3.25% loans while sitting on a brokerage account earning 7% after inflation, which is just leaving money on the table. The other hard limit is liquidity. Committing that kind of monthly payment means you're essentially pouring money into an illiquid asset. You can't easily pull equity back out without refinancing, which resets your clock and adds closing costs. If you lock yourself into a five-year payoff and then lose your job, you're stuck making those payments or facing default with no easy exit.

Practical Setup That Actually Works
Here's what I tell people who are serious about this. Set up an automatic biweekly payment schedule. Instead of twelve monthly payments, you make twenty-six half-payments per year. That equals twelve full payments plus one extra payment every year, and it shortens the term significantly without requiring you to come up with a massive monthly lump sum. The How To Pay Off Mortgage In 5 Years Calculator can model this by adjusting your payment frequency parameter. Next, set up a separate high-yield savings account and automate a transfer the day after each paycheck hits. Call it your mortgage attack fund. When the payment posts, that money moves directly to principal. This removes the temptation to spend it and keeps you honest about what you can actually afford. Finally, recalculate every time your rate changes or your tax bill shifts. Use the same calculator, update the inputs, and adjust your payment or your extra contribution accordingly. The plan that worked in month one won't necessarily work in month thirty-six if your expenses drifted. Staying ahead of that is what keeps the five-year target reachable.