The Paperwork Nobody Warns You About
Most people start by looking at prices and fleet discounts. That's fine, but the actual process of How To Purchase A Car For Your Business is where you'll either save money or accidentally buy yourself a tax headache. I've done this probably forty times across different companies, and the ones that go wrong always share the same pattern: they focused on the monthly payment and ignored the title and registration chain. Step one is deciding what kind of vehicle purchase this will be. New from a dealer, used from a dealer, or private party. Each one has a completely different tax treatment. When you buy new from a manufacturer-authorized dealer, they handle the title work and you just sign. When you buy used from a dealer, they sell you the car and then the DMV processes it. Private party is where things get messy. The seller has to properly transfer the title, you have to pay use tax at the county level, and half the time the seller has already paid off the loan but forgot to get the lien released on paper. I once bought a 2019 F-150 from a private seller who swore the bank had his title. It hadn't. The lien release took another eleven days. The car was sitting in my parking lot, unregistered, costing me a daily $18 impound-adjacent risk. I solved it by having the seller's bank fax the release directly to my county DMV, then I went to the DMV myself and stood in line for forty-three minutes with the bill of sale, the original title, and a copy of the seller's driver's license. Step two is understanding your depreciation schedule. If you're buying a car and putting it under your business name for Section 179 deductions, you need to know the weight class. Passenger vehicles over 6,000 pounds GVWR get a completely different depreciation path than anything under that threshold. A Ford Expedition Max ticks just over 6,000. A Chevrolet Suburban does too. Those two SUVs, when used exclusively for business, can be expensed up to around $25,000 in year one under bonus depreciation, depending on current tax law. A Toyota Camry? Max first-year deduction is closer to $12,000 with bonus depreciation, and that's assuming you didn't use it for personal driving at all. The moment you drive it to the grocery store, the deduction shrinks proportionally.
Registration And Insurance: Where The Hidden Costs Live
Dealer fees are one thing. Registration fees are another. California charges based on vehicle value with a percentage fee plus a county portion plus a highway maintenance surcharge. Texas is flat per-vehicle. New York adds local county taxes on top of state registration. When I set up a fleet of twelve vehicles for a consulting firm in 2022, I budgeted $420 per vehicle for registration and got hit with $680 per vehicle because I didn't account for the metropolitan district surcharge in our zip code. You can check your exact county fee at your state's DMV website before you sign anything. It takes about two minutes and saves you from surprise invoices. Insurance is where most small business owners lose money. Commercial auto policies for one or two vehicles often cost more than you'd expect because insurers read "business use" as higher risk. The workaround is called a non-owner policy combined with a garage policy, but that only works if you have a fixed location. If your employees drive the cars to client sites, you need a scheduled business auto policy. Rate differences between carriers on a five-vehicle policy for a low-risk business can be as much as $4,200 annually. I learned that by getting three quotes on the same fleet: one from a regional carrier, one from a national direct writer, and one from a broker who works with commercial accounts. The broker quote was $1,800 cheaper than the national carrier, and the coverage terms were identical except the broker included roadside assistance.
Title And Lien Management
If you're financing the vehicle, the lender becomes the lienholder on the title. That means every time you refinance or sell the car, you need that lien satisfied. Some lenders mail the title to you after payoff. Some keep it until you request it. Some send it to a processing center and it takes sixty days. I had a situation where a former fleet manager didn't request the title release until three weeks after the loan was paid off, and the lender ended up holding it for four months because they'd switched to an electronic title system mid-process. The car couldn't be sold. We had to call the lender's fleet services department directly and file a paper request with the payoff statement attached. That process took another twenty-eight days. Set a reminder for thirty days after payoff to request your title. Don't assume they're going to send it. Buying from a private seller can save you between eight and fourteen percent compared to dealer pricing on comparable vehicles. The trade-off is that you take on more administrative work and the vehicle has no dealer warranty. When I was running logistics for a landscaping company, we bought five used pickups from private sellers over eighteen months. One of them had aframe crack that the owner had welded. It failed inspection six weeks later. The welder we found who could do it properly charged $340 and took two hours. The seller would have told us about it if we'd asked. We didn't ask because we were confident and rushing. That's the main risk with private party purchases: the seller knows something and doesn't volunteer it. Always get a pre-purchase inspection from an independent shop. It costs between $120 and $180. It will tell you about frame damage, transmission issues, and pending service items that will hit you within the first six months. You need the following when buying a business vehicle: the signed title or lienholder authorization, a completed bill of sale showing purchase price and date, the seller's valid government ID, your business formation documents if registering under an LLC or corporation, a EIN letter from the IRS if the business doesn't have its own tax ID yet, and proof of commercial insurance if your state requires it at registration. Some counties ask for a smog certification. Some ask for a safety inspection. Check your local DMV requirements page. It varies by jurisdiction and the requirements change occasionally.
Get the Full Details
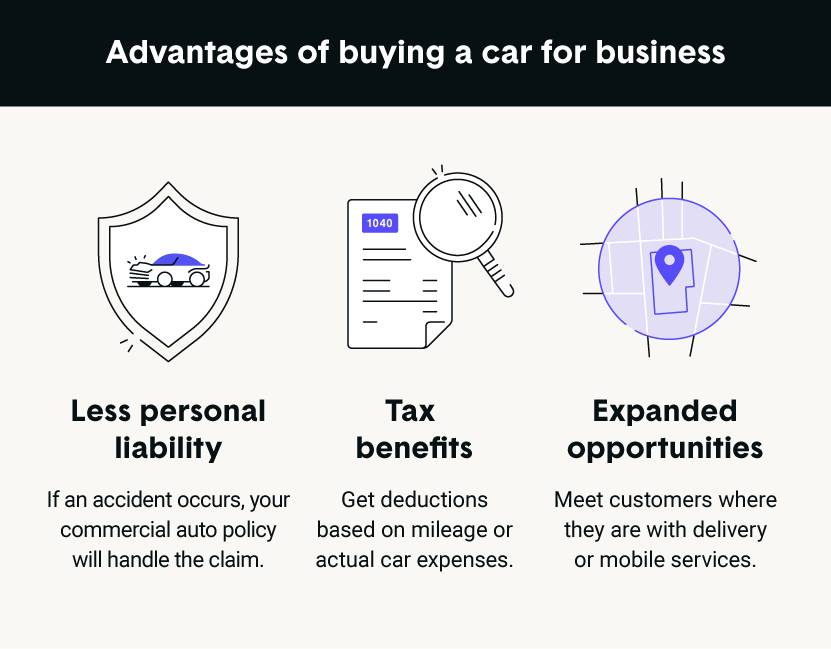
When you get the vehicle registered, make sure the registration is in the business name. If it's in an employee's name, the IRS may disallow the deduction entirely because the asset isn't technically owned by the business. I saw this happen with a delivery company that registered three vans under the driver's names to avoid higher commercial registration fees. The deduction was denied on audit. The owner owed back taxes, interest, and penalties totaling approximately $18,000 across three years. The registration savings were maybe $600 per year. Not worth it.
The Depreciation Window
If you're buying a vehicle to use as a business asset, the five-year recovery period is standard for passenger automobiles under MACRS depreciation. Heavy SUVs and trucks over 6,000 pounds GVWR fall into a different category and can be depreciated faster. The key detail most people miss is the luxury car limit. Even if you expense the full $25,000 in year one under Section 179, the IRS still caps your depreciation at a certain amount for passenger vehicles. The cap changes annually. For 2024, the first-year limit with bonus depreciation is $24,000 for qualifying heavy vehicles. For 2025 it's expected to shift slightly. If you buy the vehicle late in the year, your first deduction gets reduced proportionally based on the number of months in service. A vehicle placed in service in November gets half the year-one deduction compared to one placed in service in January. Another detail that catches people off guard: if you use the vehicle fifty-one percent or less for business, you cannot use Section 179 at all. You have to depreciate it over the full recovery period and even then, the deduction is limited to the business-use percentage. I once had a client who used his business truck for job sites and personal use on weekends. He tracked it with an app for six months and found he was at forty-two percent business use. His attempted Section 179 deduction on a $48,000 truck was rejected. He ended up depreciating the full amount over six years at forty-two percent each year. The annual deduction was roughly $3,300 instead of the twenty-five thousand he had planned. Track your miles from day one. Don't estimate retroactively.
Dealerships And Fleet Pricing
Dealers often have fleet pricing programs that are open to businesses of any size. You don't need ten vehicles. Some programs open at three. The discount ranges from two to six percent off MSRP depending on the brand and volume commitment. Ford, GM, and Chrysler all have fleet portals where you register your business and get access to pricing. Honda and Toyota have similar programs but they tend to be more exclusive. When I was setting up a small accounting firm's vehicle purchase, I registered the LLC on Ford's fleet portal, uploaded our business license and EIN letter, and got approved within forty-eight hours. The fleet price on a Transit Connect was $3,200 below what a regular retail customer would pay. The trade-off was that the vehicle had to be used for business purposes for a minimum period, usually one to two years, before you could convert it to personal use without penalty. Read the terms carefully. Some programs require the vehicle to remain registered to the business for the life of the loan. Keep every document related to the purchase. Title, bill of sale, financing statements, insurance declarations, registration papers, mileage logs, maintenance records, and depreciation schedules. The IRS can ask for any of this during an audit, and if you don't have it, you lose the deduction. I recommend a simple cloud folder labeled Vehicle Purchases, sorted by year. Upload scans within forty-eight hours of receiving each document. It takes about fifteen minutes per vehicle and eliminates the panic when tax season arrives and you can't find the bill of sale from 2021. One more thing that matters more than people realize: the purchase order. When you're working with a dealer or fleet account, get a written quote before you commit. The quote should show the vehicle price, any fleet discount, destination charges, documentation fees, tax estimates, and the total out-the-door price. I've seen dealers add $499 in undocumented fees after the buyer signs. A written quote locks them into those numbers. If they change the price later, you have the quote as leverage. Print it, sign it, keep a copy. It's five seconds of effort that prevents a lot of headaches later.