The Unromantic Truth About Starting a Medical Billing Company
Medical billing is one of those industries where people get excited too fast. They hear "work from home" and "healthcare is recession-proof" and they sign up for a $500 certification course without understanding what they're actually signing up for. I've watched dozens of people burn through their savings on this. The people who last are the ones who treat it like an insurance claims processing outfit, not a dream business. The core service you're selling is revenue cycle management. That means you take a provider's clinical data, convert it into standardized codes, submit it to payers, track denials, and collect payment. That's it. Everything else is infrastructure. A typical small practice sends between 80 and 200 claims per day. You're going to handle that volume or you won't stay in business. I learned this the hard way when a dermatology clinic signed on with me thinking I could personally review every claim before submission. I couldn't. They were submitting 40 claims a day and I was spending three hours on each one. We lost three weeks of billing cycles before I realized I needed batch processing software and a checklist system, not manual review on every single claim.
How To Start Medical Billing Business Without Wasting Two Years
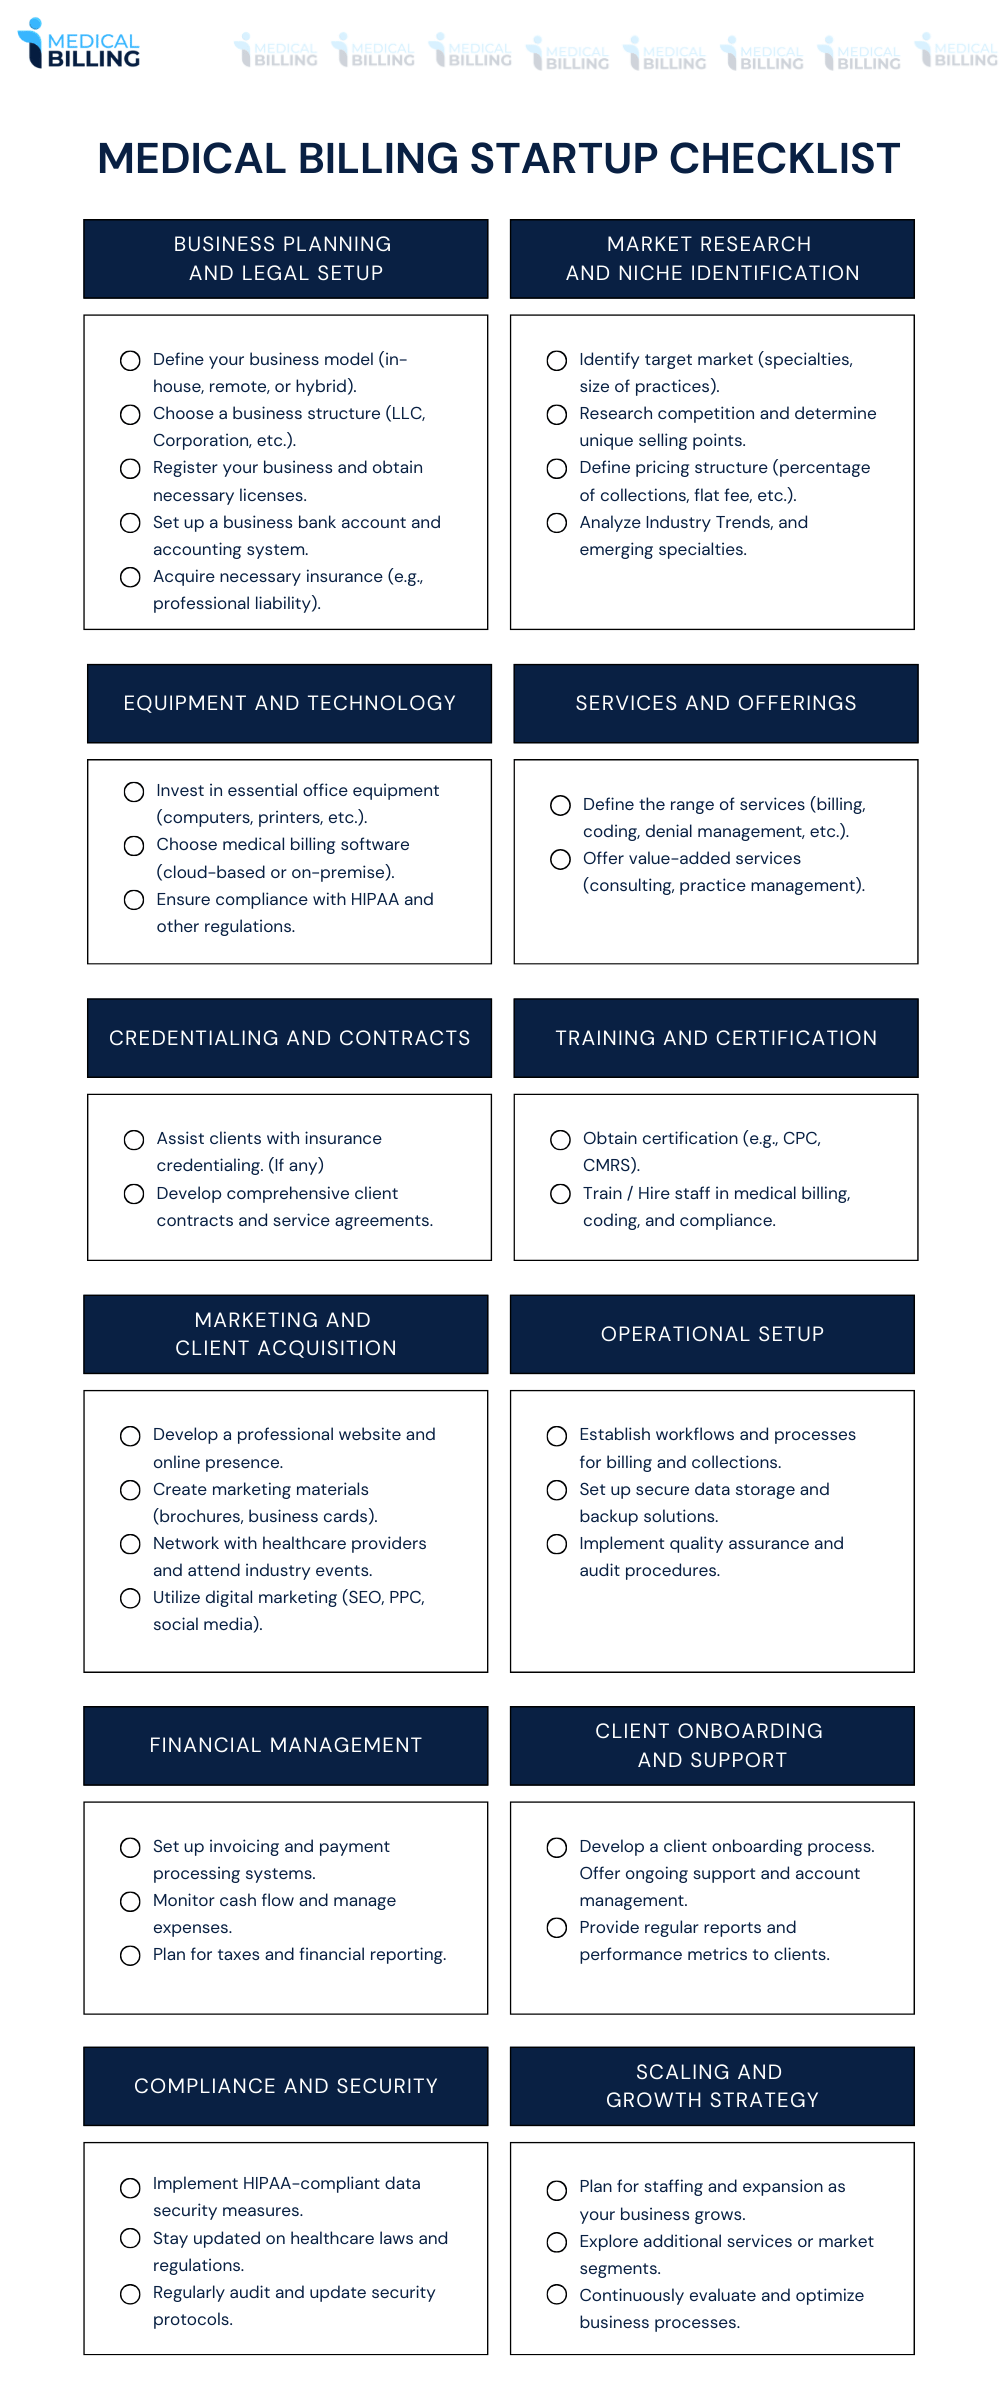
There are three real steps and they are not glamorous. Step one is getting compliant. You need HIPAA training, business liability insurance, and ideally a business entity set up properly. Don't skip the entity structure. I had a client who operated as a sole proprietor for eight months before a payer refused to contract with them because they didn't have an LLC on file. That cost him a $12,000 per month account. Step two is software. You need a clearinghouse connection and a practice management system. Clearinghouses like Availity, Waystar, or ClaimFast act as the middleman between your software and the insurance companies. The clearinghouse charges per claim, usually between $0.40 and $0.80 per claim. If you're processing 2,000 claims a month, that's roughly $800 to $1,600 a month in clearinghouse fees alone. Factor that into your pricing model from day one or you'll be subsidizing your clients out of your own pocket. Step three is learning the coding systems. CPT codes for procedures, ICD-10 codes for diagnoses, HCPCS codes for supplies and equipment. You don't need to memorize them. You need to know where to look them up and when to flag a potential issue for the provider. Here's something most beginners miss. The money isn't in the clean claims. The money is in the denied claims. A claim denial happens when a payer rejects the submission for some reason — wrong code, missing authorization, duplicate submission, patient eligibility issue. The average denial rate in the industry sits around 10 to 15 percent. Your job is to catch those, understand why they were denied, fix the root cause, and resubmit. I worked with a pediatric practice that had a 22 percent denial rate. Their top denial reason was prior authorization failures. We implemented a simple pre-submission checklist that required providers to confirm authorization numbers were entered before the claim went out. Within 60 days, the denial rate dropped to 7 percent. That practice added roughly $18,000 per month in collected revenue without seeing a single additional patient. Pricing models vary. Some billers charge a percentage of collections, typically between 4 and 9 percent. Others charge a flat monthly fee per provider or per claim. The percentage model aligns your incentives with the provider but it also means you only get paid when they get paid. If a practice has terrible charge capture to begin with, you're going to eat the risk. The flat fee model is more predictable for you but it can feel expensive to small practices that are already struggling. I recommend starting with a hybrid approach. Charge a smaller monthly base fee plus a percentage of collections above a baseline. That way you have some coverage for your overhead and you still have incentive to improve their revenue.
The biggest bottleneck in this business is getting your first client. Providers are skeptical because they've been burned before. They've had billers who disappeared, missed claims, or made coding errors that triggered audits. Your credibility matters more than your certifications. I started by offering a free claim audit. I'd take 20 of their most recent denied claims, identify the patterns, and write up a one-page report showing exactly what was wrong and what it was costing them. It took me about 90 minutes per audit. Most providers who received that report signed with me within two weeks because I was demonstrating value before asking for money. The trick is picking a niche. Don't try to bill everyone. Pick one specialty — dentistry, physical therapy, behavioral health, dermatology — and learn their specific payer rules inside and out. Each specialty has different common denials and different reimbursement rates. A generalist biller charges $50 an hour at best. A specialist who knows mental health billing backward and forward can charge $75 to $100 an hour easily. There are software tools that will help. AdvancedMD, Kareo, and Athenahealth are the big practice management platforms. They have medical billing modules built in. You can often get a reseller agreement and use their software under your own brand. This means you don't have to build your own technology stack from scratch. The trade-off is that you're dependent on their platform and their pricing changes. I've seen providers switch clearinghouses mid-contract because the new platform offered a better rate. Make sure your contracts with providers allow for technology transitions without penalty. You also need to think about what happens when things go wrong. A payer can audit you. They can claw back payments if they find billing errors. I had a situation where a Medicare audit caught a pattern of unbundled CPT codes on a surgical practice's claims. The unbundling wasn't intentional — the provider had been using separate codes for procedures that should have been grouped under a comprehensive code. The audit resulted in a $47,000 overpayment demand. Having errors and omissions insurance for medical billing specifically is essential. General business liability won't cover billing errors. Make sure your policy explicitly covers professional negligence in coding and billing services.
Get the Full Details

The industry is consolidating. Large RCM companies like Optum, R1 RCM, and Conifer are buying up smaller billing companies. This isn't necessarily bad for you. It means the market is growing. But it also means competition is intensifying. You can't compete on price alone. You need to offer something these giants can't — personalized attention, faster response times, and actual human oversight on difficult claims. A large RCM company will assign your account to a team that handles thousands of providers. You'll be a number. That's fine for big hospital systems. It's terrible for a solo practitioner who needs someone who knows their name and their specific payer relationships. If you want to get started today, the practical path is this. Get HIPAA compliant training completed — there are free courses through HHS.gov. Form an LLC. Get business liability insurance that includes professional coverage. Pick one specialty and one payer type to start. Learn their denial patterns by pulling public data from the Medicare Provider Utilization and Payment Data or from state Medicaid dashboards. Build a simple one-page audit template. Reach out to five providers in that specialty and offer the free audit. Do the work. Follow up. Close the first client. Then repeat.