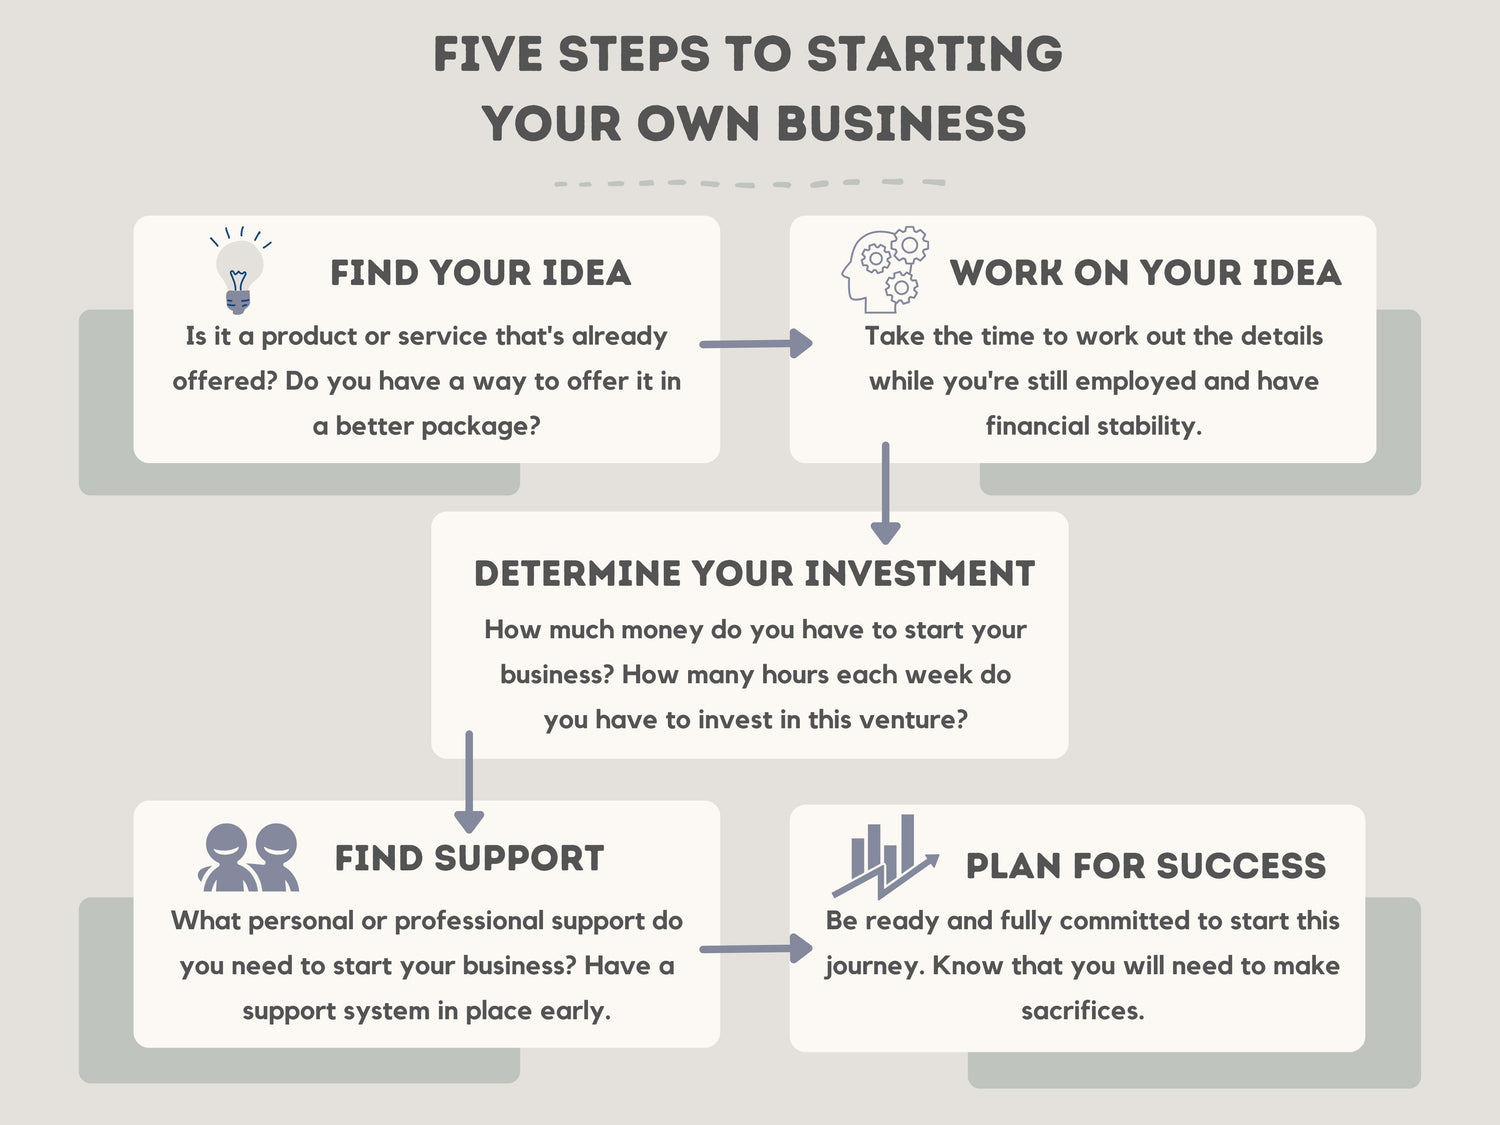
The boring truth about starting an organization
Most people treat the legal paperwork as the hard part. It isn't. The hard part is figuring out what structure actually fits before you file anything, because once you pick a vehicle — LLC, nonprofit, cooperative, association — you are locked into its tax treatment, liability shield, and governance rules for years. I spent three years running a small membership org that started as an LLC because it was faster to set up, then spent another six months untangling it when we realized we needed 501(c)(3) status to actually attract the funding we were chasing. The filing took two weeks. The undoing took a year and a half. Step one is not filing documents. Step one is writing down what the organization will actually do, how money moves in and out, who makes decisions, and what happens when things fall apart. Get that on paper before you talk to a lawyer or look at any state portal. I used to skip this with new founders and watch them pick an LLC for a project that needed a nonprofit, or pick a nonprofit for something that would eventually want outside investors. Both are fixable. Neither is cheap. If you want personal liability protection and flexible ownership, a limited liability company is usually the right call. You can have one member or many. Members own percentages. Profits and losses flow through to personal tax returns unless you elect corporate taxation. Formation documents are called articles of organization in most states. Operating agreements govern internal rules and they are where you should specify how decisions are made, how new members join, and what triggers a buyout.
If your goal is charitable work with no private benefit, a 501(c)(3) public charity is the standard choice. You file articles of incorporation with a purpose clause, adopt bylaws, get an employer identification number, and then apply for tax-exempt status with the IRS using Form 1023 or the shorter 1023-EZ if you qualify. Revenue below fifty thousand dollars in annual gross receipts and assets under two hundred fifty thousand dollars generally makes the 1023-EZ an option. The process usually takes three to eight months depending on IRS backlog and whether you get a determination letter on the first pass. Donors can deduct contributions. You must file Form 990 annually. Private foundation rules are stricter and mostly unnecessary unless you are funded by a single family or endowment. If you want member control rather than a board-dominated structure, a cooperative or membership LLC might be better. One member, one vote is possible in an LLC if your operating agreement says so. Standard nonprofit bylaws often default to a board with member voting rights that are easier to limit than to expand later.
Basic formation checklist
Here is the sequence I actually use when I help someone set one up, not the order a bar review book would list it: Reserve or confirm the name. Check your state business registry. If you plan to operate under a different name, file a trade name or assumed name certificate early. Most states charge between fifteen and one hundred dollars for initial formation and name reservations.Annual report fees vary widely from zero to several hundred dollars. Get an EIN. The IRS issues this free. You can apply online in about ten minutes. You need it before opening a bank account, hiring anyone, or filing most formation documents. Do not share the EIN publicly until you are ready.
Get the Full Details
File the formation document. For an LLC that means articles of organization. For a nonprofit that means articles of incorporation. File with the secretary of state or equivalent agency. Fees range roughly from sixty to two hundred fifty dollars depending on the state. Processing times range from same day in some states to thirty calendar days in others. Write the operating agreement or bylaws. Do not skip this because someone told you an LLC without members is simple. Single-member LLCs still benefit from a written operating agreement, especially if you ever need to show that the entity is separate from your personal affairs. Courts look at whether you treated the entity as separate. Written agreements help prove that. Open a business bank account. Bring the formation document, EIN letter, and a resolution or authorizing document naming who can sign. Some banks will open an account with just two of those. Others insist on all three. Pick a bank that does not charge monthly fees unless you can maintain the required balance. Small orgs get eaten alive by maintenance fees.
Handle local requirements. Business licenses, tax registrations, and employer filings depend on your city and state. If you plan to hire even one person, you need state workforce registration and federal employment tax setup. Doing this after you hire someone is how people get penalized.
Where people usually mess up
The first mistake I see is mixing personal and organizational money. One coffee shop purchase on the org card and suddenly your liability protection looks thinner. The second mistake is writing vague purpose clauses in the articles. The IRS rejects charitable purpose language that sounds like lobbying or political activity. The third mistake is picking a structure because it is cheaper upfront and then paying ten times that later to change it. Conversions exist in most states, but they trigger new tax events and sometimes require creditor notices that pause everything. A specific edge case I ran into last year involved a small environmental group that formed as an LLC, raised grant money as if it were a nonprofit, and then discovered their funder required 501(c)(3) status before releasing the second tranche. Converting an LLC to a nonprofit is not a simple form swap. Some states allow a statutory conversion. Most require liquidating the LLC and transferring assets to a newly formed nonprofit, which can trigger taxable events and complicate existing contracts. We worked around it by having the LLC assign all programs and assets to the new nonprofit through a triple-net lease and services agreement while the LLC wound down, but it added about four months and roughly three thousand dollars in legal and filing costs that could have been avoided with a different first decision.
Tax and compliance basics
LLCs are pass-through entities by default. That means the organization itself usually does not pay federal income tax. Members report their share of profit or loss on personal returns. If you want the entity taxed as a corporation, you file Form 8832. S corporation election uses Form 2553 and has restrictions on who can be a shareholder. Nonprofits file Form 1023 or 1023-EZ and then Form 990, 990-EZ, or 990-N each year. The 990-N is for very small organizations with gross receipts normally below twenty-five thousand dollars. Sales tax collection depends on your activities and location. If you sell goods or certain services, you may need a seller's permit. Charitable organizations are sometimes exempt from sales tax on purchases related to their exempt purpose, but rules vary by state and you usually must apply for that exemption separately. Do not assume automatic exemption.
Operations that actually matter
Keep a minute book. It does not have to be fancy. Record board or member meetings, elections, key decisions, and any conflicts of interest. For nonprofits, conflict of interest policies are not optional if you want to avoid excise taxes under IRC section 4958. Those rules apply to excess benefit transactions with disqualified persons, and the penalties scale with the excess amount plus a twenty-five percent excise tax on the person who received it. Second-tier taxes can reach two hundred fifty percent if the person does not correct the situation. Set up a simple accounting system from day one. QuickBooks Self-Employed works for single-member LLCs. QuickBooks Online Essentials or Wave covers most small nonprofit needs. Separate charts of accounts for program services, fundraising, and management expenses matter if you ever apply for grants. Grant reviewers look at overhead ratios and program spending percentages. Your numbers need to be defensible. If you plan to raise money publicly, register with your state charity regulator before you solicit. Most states require registration for charitable solicitation, and penalties for unregistered solicitation can include injunctions and restitution demands. The National Association of State Charity Officials publishes a registration guide that lists requirements by state. Costs range from fifty to several hundred dollars per state depending on the jurisdiction.
When this approach breaks down
None of the above helps much if you are trying to run a multi-state advocacy organization on a shoestring budget. State-by-state charity registration alone can cost thousands annually. In that scenario, partnering with an existing fiscal sponsor is usually cheaper and faster. Fiscal sponsorship lets you operate under another organization's tax-exempt status while maintaining programmatic independence. You pay a percentage of raised funds, typically ten to fifteen percent, and you give up some control over how donations are characterized. It is not ideal, but it is realistic for early-stage groups that need credibility before they can stand alone. Another scenario where the standard path fails is international work. If your organization will receive funds from or send funds to foreign entities, you need export control screening, possible OFAC compliance checks, and deeper banking scrutiny. U.S. banks will close accounts for orgs that trigger certain flags without much warning. Get a banking relationship early and tell the relationship manager exactly what your activities are. Hiding international transactions from your bank is a fast way to lose access to your own money.

A practical first-week plan
Day one: draft a one-page mission statement and list your core activities. Day two: check name availability and reserve the name if needed. Day three: apply for the EIN online. Day four: draft the operating agreement or bylaws. Day five: file formation documents with the state. Day six: open the business bank account. Day seven: set up a simple bookkeeping template and schedule your first board or member meeting. That is enough to be legitimate in most jurisdictions without spending more than a few hundred dollars or waiting longer than two weeks. The rest of the work is maintenance. Filings, meetings, accurate books, and clear boundaries between personal and organizational affairs. Pick the right structure first. Everything else gets easier from there.